

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Resilient Growth: Automotive Body Repair Fillers Market to Expand at a 4.85% CAGR from 2026–2032

Automotive Body Repair Fillers Market — Strategic Outlook for 2026: PW Consulting Releases Actionable Industry Intelligence
Executive summary
PW Consulting today publishes a market intelligence brief designed to inform C-suite and commercial leaders preparing strategic initiatives for 2026 and beyond. Our Automotive Body Repair Fillers Market study synthesizes five years of historical performance (2020–2025) and delivers a granular forecast across 2026–2032. The global market reached approximately USD 3.6 billion in 2025 and, under our base-case assumptions, is forecast to grow at a compound annual growth rate (CAGR) of 4.85% through the 2026–2032 horizon — reaching just over USD 5.0 billion by 2032. This release summarizes the practical implications for decision-makers while preserving the proprietary segment-level detail available in the full report.
Automotive Body Repair Fillers Market
Why this matters for 2026 decision cycles
-
Market maturity with pockets of opportunity: The market demonstrates steady expansion rather than explosive growth. This creates an environment where operational excellence, supply-chain resilience and targeted product differentiation deliver more sustainable ROI than broadscale volume plays.
Automotive Body Repair Fillers Market -
Strategic timing: With 2026 planning cycles under way, firms that align 2026 capex and commercial strategies to the report’s mid-term scenarios can both protect margins and capture higher-value share in premium segments.
Automotive Body Repair Fillers Market -
Regulatory and feedstock volatility are game-changers: Raw material and regulatory risk are not hypothetical — they have measurable impacts on product cost, formulation choices and go-to-market tactics.
Market snapshot: scale, concentration and trajectory
Our topline synthesis places the global automotive body repair fillers market at roughly USD 3.6 billion in 2025 with a steady growth trajectory to about USD 5.02 billion by 2032. The industry exhibits moderate concentration — the top three players account for under a third of global value, while a top five cohort contributes a little above 40%. For strategy teams, this concentration profile signals a competitive landscape where national champions and specialized formulators can still capture defensible niches through product performance, distribution strength and service models.
Key demand and product trends to watch in 2026
-
Premiumization and performance: Professional collision repair shops increasingly favor formulations that speed cycle times (faster cure, easier sanding) and reduce rework. Lightweight and specialty fillers that balance workability with finish quality continue to win specification share among professional users.
-
Material substitution and technology adoption: Water-based and lower-styrene chemistries are gaining experimental traction as both OEMs and refinishers test alternatives to traditional polyester systems driven by regulatory and sustainability pressures.
-
Service-led differentiation: Suppliers that pair product portfolios with digital tools (application guides, cure-time calculators), training programs and local technical support are consistently more successful at premium price capture.
Supply-side dynamics and risk vectors
Three structural supply-side factors should shape 2026 strategies:
-
Feedstock volatility: Unsaturated polyester resin pricing experienced severe peak-to-trough swings (exceeding 40% over 2020–2025 according to industry data). Petroleum-linked components remain exposed to global oil market instability. Procurement teams should model multi-year scenarios that include both sustained higher-cost baselines and episodic shock events.
-
Regulatory pressure on styrene: Ongoing evaluations — including potential SVHC (Substance of Very High Concern) classification in Europe — could introduce new authorization burdens for polyester-based products. Regulatory trajectories can materially change raw material availability and reformulation costs in a short window; firms should prioritize chemical risk-mitigation pathways and accelerate low-styrene alternatives where feasible.
-
Consolidation and channel dynamics: Although the market is not highly concentrated, the middle tier is active. Expect continued M&A among specialty formulators, regional distributors and service-oriented players as they pursue scale and distribution density.
Competitive landscape — who to watch
Our competitive review profiles incumbent global players and regional specialists whose strategies set the competitive baseline:
-
ITW Evercoat (Cleveland, Ohio) — A premium-focused portfolio with formulations tailored for professional collision repair; recent product refreshes emphasize lightweight and UV-cure technologies aligned with faster cycles and improved finish characteristics.
-
3M (St. Paul, Minnesota) — A technology-led competitor offering vacuum-processed and lightweight systems for multi-substrate repair, with scale advantages in distribution and brand recognition among professional installers.
-
U.S. Chemical & Plastics (USC) (Ohio) — Supplier of workability-focused lightweight fillers with strong legacy adoption in professional networks.
-
Bondo (3M) — Iconic brand equity in dent-and-ding repair that continues to provide a volume gateway product line alongside 3M’s professional offerings.
-
U-POL (United Kingdom) — European-based supplier emphasizing adhesion and finishability for professional refinishing applications.
-
AkzoNobel (Amsterdam) — Global refinish portfolio with specialty curing options that appeal to collision centres seeking throughput gains.
-
SYNEW (China) — A growing manufacturer supplying both domestic and export channels with cost-competitive formulations for distribution partners and repair shops.
PW Consulting’s report drills into product positioning, channel strengths, and technical differentiators for these firms, together with a playbook for benchmarking competitors against a buyer’s technical and commercial scorecards.
Recent industry movements: product innovation and market signaling
-
Notable launch: In October 2025 ITW Evercoat announced a brand refresh accompanied by three new products, including a premium lightweight filler and a UV-cure primer showcased at SEMA. This underscores two strategic themes: speed-to-finish and premiumization in professional channels.
-
Procurement and partnership shifts: Distributors are pairing technical training with inventory finance arrangements to lock in professional accounts—an effective counter to pure price competition.
What the full PW Consulting report delivers (practical, executable content)
Our market study is structured for immediate application by commercial, product and procurement teams. Deliverables include:
-
Demand scenarios and financial impact models: Three forecast paths (base, upside, downside) with P&L sensitivity analyses customized for typical filler manufacturers and aftermarket distributors.
-
Commercial playbooks: Channel segmentation, pricing elasticity matrices, and go-to-market option sets — from national distributor partnerships to shop-level direct programs.
-
Formulation risk assessment: A prioritized toolkit for raw-material substitution (including low-styrene and waterborne approaches), reformulation cost estimates and implementation timelines.
-
Competitive playbench: Opponent profiles, capability matrices and recommended defensive/offensive moves by company type (global majors, regional champions, private-label players).
-
Operational readiness checklist: Procurement buffers, inventory hedging tactics, and quality controls to preserve margins in a high-volatility feedstock environment.
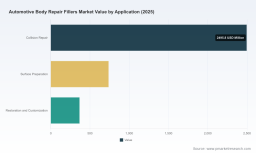
Note: To preserve the analytic integrity of our commercial advisory, the report’s segment-level share tables and monetized regional splits are exclusive to the full publication.
Strategic recommendations for 2026 planning
-
Prioritize margin resilience over volume growth in 2026: Given feedstock volatility and regulatory uncertainty, firms should emphasize product- and service-led margin capture rather than aggressive discounting to chase share.
-
Fast-track low-regret reformulations: Identify the top two product lines where low-styrene or water-based options can be delivered with minimal disruption; create pilot programs with selected collision centers to validate performance and economics.
-
Strengthen distributor partnerships with service bundling: Offer technical training, application audits and co-marketing to deepen penetration in technician-led buying environments.
-
Hedge procurement with layered contracts: Use a mix of fixed-term agreements, index-linked procurement and physical inventory buffers sized against scenario stress tests from our models.
-
Monitor regulatory hotspots: Maintain a cross-functional working group (regulatory + R&D + commercial) to track chemical policy developments and initiate contingency plans for authorization or substitution timelines.
Conclusion — the practical value for 2026 movers
For executive teams preparing 2026 initiatives, this PW Consulting study converts market-scale context into executable business options. The global market’s steady growth and moderate concentration create an environment where focused product innovation, channel sophistication and supply-chain risk management deliver disproportionate returns. Our field-tested tools and scenarios enable procurement, R&D and commercial leaders to prioritize investments that protect margins and position their organizations to capture premium share as the industry evolves.
Accessing the full intelligence
This release is a strategic briefing designed to demonstrate the report’s actionable depth while reserving the full, monetized segment maps and granular regional/application splits for subscribers. For the complete dataset, downloadable models, and proprietary segment detail that will directly inform 2026 budget and product decisions, visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Automotive Body Repair Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com