

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CPE Antenna Market to Jump from USD 1,580 Million (Base Year 2025) to USD 2,755.6 Million by 2032 in 2026–2032 Forecast at 8.27% CAGR — Asia Pacific Leads with USD 646.8M

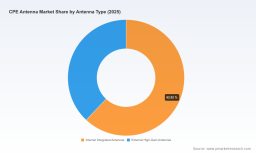
CPE Antenna Market 2026 Strategic Outlook — A PW Consulting Industry Brief
Executive summary
As global broadband strategies pivot toward fixed wireless access (FWA), carrier aggregation and next‑generation Wi‑Fi, CPE antenna technology has become a strategic battleground for operators, device OEMs and component suppliers. PW Consulting’s latest Cpe Antenna Market study (base year 2025, historical review 2020–2025, forecast 2026–2032) shows the market expanding from roughly USD 1.09 billion in 2020 to USD 1.58 billion in 2025 and projecting to grow at a compound annual growth rate (CAGR) of 8.27% through 2032 — reaching approximately USD 2.76 billion by the end of the forecast horizon. This trajectory is being driven by mid‑band spectrum mobilization, rising demand for high‑throughput consumer and enterprise CPEs, and rapid innovation in antenna system integration and AI‑assisted beamforming.
Cpe Antenna Market
Why 2026 is a decision pivot for enterprises
- 2026 is the first full planning year after major regulatory shifts and high‑profile vendor product cycles; strategic choices made this year will determine market share and capex trajectories for the next technology cycle.
- Spectrum policy timelines and auctions scheduled in the mid‑to‑late 2020s materially change the economics of FWA deployments — accelerating the need for mid‑band optimized CPE antennas and modular device architectures.
- Vendor consolidation and selective design wins will shape supply reliability and ability to support differentiated features such as integrated AI antenna solutions and mmWave compatibility.
Market trajectory and what it means for buyers and investors
The market’s steady growth at an 8.27% CAGR reflects a shift from pure coverage‑focused antenna designs toward performance‑optimized systems that deliver spectral efficiency, multi‑band support and gateway‑level integration. For operator procurement teams, this means procurement criteria will increasingly include not just cost and availability but RF performance per watt, upgradeability, and vendor roadmaps for mid‑band and mmWave enablement. For investors, the market size and forecast highlight both scale and the potential upside of targeted R&D and bolt‑on M&A in antenna IP, embedded RF modules and software‑defined antenna control.
Cpe Antenna Market
Competitive dynamics — who is shaping the next wave
The market is moderately concentrated: the combined top‑3 players account for just over one‑third of market revenues, while the top‑5 control roughly half. This concentration profile creates a competitive environment that rewards scale in R&D, proven field deployments and the ability to secure multi‑year design wins with major CPE OEMs and carriers.
Cpe Antenna Market
Key vendor archetypes and strategic moves highlighted in the report:
- Advanced systems integrators (example: Vantiva) are differentiating through proprietary multi‑element indoor antenna systems that deliver high mid‑band gain and efficiency to extend base‑station reach in dense FWA scenarios.
- Large network equipment OEMs (example: ZTE) leverage end‑to‑end platform scale — combining 5G‑A‑ready CPE hardware with AI‑driven antenna control and beam scanning to capture operator roadmap spend.
- Specialist outdoor and industrial antenna manufacturers (example: Poynting) compete on ruggedization, wideband coverage and site‑grade reliability required for rural and enterprise fixed wireless use cases.
- Consumer‑focused networking brands (example: TP‑Link) pursue high‑value, high‑gain directional designs enabling long‑range bridging and last‑mile solutions at aggressive price points.
- Embedded antenna innovators (example: Airgain) are winning multi‑year design contracts with gateway OEMs by delivering compact, high‑performance embedded solutions for next‑generation Wi‑Fi platforms.
Across these archetypes, our competitive analysis identifies three winning capabilities: demonstrable field gains at target bands, software‑enabled beam/AI control, and robust supply chain validation with test evidence from anechoic chamber results and field trials.
Recent developments that reshape strategy
- Product launches from major vendors in early 2026 introduced 8Rx–14 dBi class indoor antenna systems and Sub‑6/mmWave outdoor CPE lines that materially raise the bar on spectral efficiency and throughput for FWA deployments.
- Design wins with gateway OEMs for Wi‑Fi 7/8 embedded antennas have created an early pipeline of high‑volume opportunities for specialist antenna suppliers through 2026–2027.
- Regulatory change — particularly in the U.S. — including the FCC’s reclassification of broadband (Title II) in 2024, proposed repurposing of Upper C‑band mid‑band spectrum and federal directives to identify commercial spectrum, introduces both opportunity (larger mid‑band allocations for FWA) and policy risk (regulatory uncertainty and litigation outcomes that can reframe market access rules).
Regulation, spectrum, and deployment risk
Regulatory dynamics are central to 2026 planning. Spectrum repurposing proposals and planned auctions create a narrow window for operators to align CPE roadmaps with expected mid‑band availability; meanwhile, judicial outcomes and legislative actions in 2024–2025 illustrate how regulatory reversals can compress or expand addressable markets. Our report models multiple spectrum auction scenarios and their implications for unit economics, average revenue per user (ARPU) uplift, and device feature prioritization, enabling leaders to stress‑test go‑to‑market plans.
Strategic implications — actionable guidance for 2026 planners
PW Consulting’s analysis yields practical recommendations across four stakeholder groups:
- Operators and service providers: prioritize mid‑band optimized CPE trials now, establish flexible leasing/upgrade programs, and require multi‑mode modularity in procurement specs to protect against shifting spectrum allocations.
- CPE and antenna OEMs: invest in AI‑enabled antenna control, modular mmWave add‑ons and validated anechoic test evidence to win operator design slots; pursue partnerships for handset‑grade RF IP where scale is lacking.
- Component suppliers and contract manufacturers: accelerate tooling and test automation investments to shorten time‑to‑market for multi‑band reference designs and reduce field failure rates that erode operator confidence.
- Private equity and strategic investors: target mid‑tier players with differentiated R&D or embedded antenna IP; prioritize assets that offer design‑win pipelines with tier‑one gateway OEMs and proven field performance.
Report contents — what decision‑makers will use
To be operationally useful in 2026, market intelligence must be executable. PW Consulting’s report includes:
- Validated historical market sizing (2020–2025) and bottom‑up forecasts (2026–2032) with scenario variants tied to spectrum outcomes and adoption curves.
- Vendor playbooks and competitive scorecards that benchmark technology (gain, efficiency, band coverage), commercial positioning, and supply chain resilience.
- Product and RF performance matrices, including anechoic chamber performance summaries, BOM sensitivity analyses and cost‑to‑serve models for common CPE classes.
- Regulatory and spectrum scenario modeling to quantify impacts on unit economics and deployment timing.
- Supplier due‑diligence templates, procurement RFP language, and migration roadmaps for operators planning hybrid fiber‑to‑home and FWA architectures.
- M&A target screen and valuation ranges for strategic acquirers seeking IP, OEM relationships or manufacturing scale.
How leading companies are positioning themselves
Our company profiles identify distinct strategic postures:
- R&D‑led incumbents are focusing on higher‑order antenna arrays and integrated boosters to improve spectral efficiency in high‑density urban deployments.
- Equipment manufacturers with operator channel access bundle advanced antenna modules with cloud‑native device management to lock in long‑term support contracts.
- Specialist suppliers emphasize ruggedized designs, wideband passive coverage and ease of field installation to capture rural/enterprise FWA demand.
Case in point: recent product launches and design wins in late 2025–early 2026 demonstrate a clear bifurcation — vendors pursuing premium integrated indoor antenna systems aiming at urban FWA throughput gains, and others doubling down on outdoor high‑gain directional and IP‑rated enclosures for long‑range connectivity.
What we intentionally withhold in this brief (and why)
This release follows a “trailer” principle: it provides the strategic conclusions, modeled scenarios and supplier archetypes that decision‑makers need to assess 2026 choices, while withholding full segmentation tables, granular regional/application revenue breakdowns and detailed numerical financial models. Those items are included in the full PW Consulting report to ensure clients receive the validated datasets and proprietary models necessary to underwrite investments and procurement commitments.
Next steps for leaders in 2026
- Run a rapid 90‑day evaluation of current CPE roadmaps against mid‑band and mmWave scenarios modeled in our report.
- Initiate targeted field trials with two complementary vendor classes (one integrated indoor solution, one rugged outdoor supplier) to de‑risk vendor selection.
- Embed regulatory scenario clauses into procurement contracts to preserve optionality in the event of auction timing shifts or spectrum reallocation outcomes.
Access the full intelligence
PW Consulting’s full Cpe Antenna Market report delivers the segmented market tables, vendor scorecards, RF performance appendices and actionable procurement templates necessary to convert insight into competitive advantage. To obtain the full study, download our report or contact PW Consulting for a tailored briefing and model access. Our team is available to run a custom workshop to align the report’s scenario outputs with your 2026 capital and product planning cycles.
For detailed analysis of this topic, please visit the official page: Cpe Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com