

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vertical Rotary Surface Grinders Market to Climb to USD 3,779.99 Million by 2032 at a 5.59% CAGR

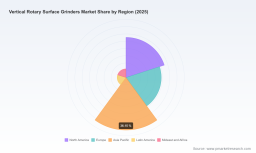
PW Consulting Releases Strategic Brief: Vertical Rotary Surface Grinders Market Outlook 2026 — Actionable Intelligence for Capital and Supply-Chain Decisions
PW Consulting today publishes an executive-level market brief that synthesizes primary research, supplier intelligence, and scenario modeling for the Vertical Rotary Surface Grinders market. Designed for boardrooms and operational leaders preparing 2026 budgets, the brief translates technical product trends and competitive moves into clear strategic options. It demonstrates where to prioritize capital, where to de-risk supply chains, and how to capture aftermarket and retrofit revenue — while reserving granular segment tables for the full report.
Vertical Rotary Surface Grinders Market
Executive snapshot
Our market model benchmarks the industry from 2020 through a 2025 base year and provides a detailed forecast across 2026–2032. Key headline metrics: the market is projected to grow at a compound annual growth rate (CAGR) of 5.59% from the 2025 base, with total industry revenues moving from the 2025 baseline into a materially larger market by 2032 under our base-case scenario. Competitive concentration is moderate: the top three suppliers account for roughly 38.5% of market revenues and the top five for about 52.7%, indicating room for regional specialists and differentiated niche players to compete effectively.
Vertical Rotary Surface Grinders Market
Why 2026 is a tactical inflection point
-
Capital spending cycles in core end markets (automotive, aerospace, tooling and general machinery) are synchronizing with urgent capacity and precision demands, creating windows for OEMs and service providers to capture share through targeted investments.
Vertical Rotary Surface Grinders Market -
Raw-material dynamics—in particular, steel coil price movements and proposed tariffs on specialty inputs—are compressing margins for equipment manufacturers that rely on global sourcing. Our analysis shows these pressures become decision catalysts for reshoring, supplier diversification, and hedging strategies in 2026.
-
Regulatory scrutiny on machine-tool imports continues to shift commercial terms and logistics arrangements; procurement teams that plan now can avoid supply disruptions and cost surprises later in the forecast window.
What PW Consulting’s brief delivers (select highlights)
-
Actionable market sizing and high‑confidence forecasts aligned to real order-cycle patterns across 2020–2025 and into 2026–2032, including sensitivity scenarios for downside (trade friction) and upside (accelerated electrification/automation) outcomes.
-
A supply‑chain heat map identifying single‑source exposure, tariff risk, and lead‑time bottlenecks across casting, machining, spindle manufacture, and turntable systems.
-
Competitive benchmarking that evaluates product architectures (hydrostatic tables, high‑HP vertical spindles, turntable capacity), aftermarket strategies (reman, retrofits, parts and service), and go‑to‑market footprints.
-
Commercial playbooks and investment decision frameworks for OEMs, distributors, and strategic buyers—covering pricing, retrofit service bundles, and targeted capex allocation to maximize ROI in the 2026 planning cycle.
-
Quantitative risk matrices tying macro drivers (material inflation, tariffs, regional policy) to revenue and margin outcomes over 18–36 month horizons.
Competitive landscape — who matters and why
The market architecture blends established OEMs, regional specialists, and a vibrant remanufacturing/aftermarket segment. Our qualitative and quantitative work identifies three strategic archetypes that matter for 2026 planning:
-
Legacy OEMs with brand and service networks: These firms leverage established product lines, heavy‑duty spindle technology and large chuck capacities to serve heavy stock‑removal and precision work. Their strategic strengths are installed base monetization and project engineering capability.
-
Regional/volume manufacturers: Smaller manufacturers focused on cost‑competitive machines and regional service are nimble in local aftermarket offerings and can capitalize on near‑shoring trends.
-
High‑precision specialists: Companies emphasizing hydrostatic turntables, ultra‑rigid frames, or high‑accuracy rotary tables target aerospace and tooling customers where precision commands premium pricing.
Representative vendor intelligence included in the brief (profiles and strategic implications):
-
Bourn & Koch (Rockford, IL) — a longstanding OEM and remanufacturer known for large Blanchard-style rotary grinders. Their role in heavy‑duty capacity and reman programs makes them an obvious partner for tier‑1 suppliers seeking near-term capacity without long lead‑times.
-
DCM Tech (Winona, MN) — American-made IG series grinders that favor domestic supply chains and precision workshops; they are positioned to benefit from procurement shifts toward lower import exposure.
-
Chevalier Machinery (Taiwan/USA) — with hydrostatic turntable offerings and high‑rigidity platforms, Chevalier addresses precision and heavy-load work; product evolution here is instructive for competitors prioritizing cycle time and flatness performance.
-
Okamoto Corporation (Japan) — high‑power spindle vertical grinders and high-accuracy tables that cater to high-removal rate and precision applications; innovation in spindle technology remains a differentiator.
-
Tong Yi / Dowell (Taiwan), Alex Machine Tools (India), Synergy Machine Tools (India), ABL Machine Tools (India), and Kent USA — a mix of regional players with competitive pricing, localized service networks, and presence in die & mold and general engineering markets. Their recent activities, including trade-show participation and new installations, underscore a multi‑regional growth dynamic.
Recent signals and their strategic implications
-
Trade-show activity and product launches reflect ongoing investments in new machine classes and aftermarket offerings. For example, major exhibitors showcased expanded ranges and customization capabilities in early 2026 — a sign that vendors are positioning for differentiated value rather than commoditization.
-
Field installations and incremental capacity additions demonstrate conservative demand recovery strategies: instead of large, speculative factory builds, firms are incrementally adding capacity tied to firm order books.
-
Raw-material cost swings and continued import scrutiny are not abstract risks. Steel input inflation and potential tariffs increase the economic case for regional assembly, strategic inventory, and redesigns that reduce reliance on high‑cost inputs.
Strategic imperatives for 2026 decision-makers
-
Reassess supplier networks now: Identify single points of failure across castings, spindles, and precision bearings. Prioritize dual sourcing or near‑shoring for components where tariff or lead‑time risk is material.
-
Capitalize on the installed base: Invest in remanufacturing and retrofit programs. For many suppliers, aftermarket margins and recurring service contracts will drive profitability while new‑machine sales normalize.
-
Differentiate on technical features that matter to premium end users: hydrostatic turntables, high‑HP vertical spindles, and automation interfaces command pricing power in aerospace and tooling segments.
-
Embed scenario-based capital planning into 2026 budgets: Use sensitivity analysis to set trigger points for lean vs. expansionary capex, particularly where tariffs or raw‑material price thresholds would erode returns.
-
Consider M&A and strategic partnerships selectively: Acquire local service footprints or specialized component suppliers to lock in service revenue and reduce exposure to cross-border trade friction.
Risk outlook and contingency themes
Our stress-testing highlights three risk clusters: (1) trade and tariff escalation that raises landed cost profiles dramatically; (2) rapid raw-material inflation that compresses margin at OEMs reliant on global inputs; and (3) cyclic demand shocks in major end markets that can make high‑fixed-cost expansions unviable. The brief includes quantified scenarios that map these risks to revenue and margin outcomes, enabling CFOs to create contingent budgets and contractual protections.
How PW Consulting’s analysis supports execution
The deliverables accompanying the brief include:
-
Decision trees for capital allocation tied to demand thresholds and tariff scenarios.
-
Supplier risk scorecards with recommended mitigation tactics by component category.
-
Commercial playbooks for aftermarket monetization, retrofit pricing, and cross‑sell strategies aligned to customer lifetime value.
-
Competitive scorecards and product-comparison matrices that help procurement and product teams prioritize supplier partnerships.
Next steps — where to get the full intelligence
This public brief outlines the strategic value of incorporating vertical rotary surface grinder dynamics into 2026 planning. For companies that need to operationalize the insights — with regional split forecasts, application-level growth curves, detailed competitor scorecards, and downloadable datasets — PW Consulting’s full report and accompanying data toolkit provide the granular inputs decision-makers require.
Contact PW Consulting to access the full Vertical Rotary Surface Grinders Market Report, the proprietary model files, and custom advisory engagements that translate these findings into executable initiatives for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Vertical Rotary Surface Grinders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com