

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Built‑In Electric Curtains Market to Surge at a 10.51% CAGR Through 2032

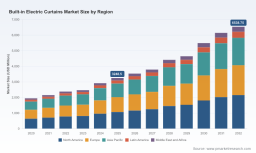
Built-In Electric Curtains Market — Strategic Intelligence Briefing for 2026 Decision Makers
PW Consulting’s new market study on Built-In Electric Curtains synthesizes five years of historic performance (2020–2025) with a seven-year forecast (2026–2032), delivering the decision-grade insights executives need as they plan product roadmaps, supply-chain commitments, and go-to-market moves for 2026. The global market expanded from USD 1,950.4 Million in 2020 to USD 3,248.5 Million in 2025 and is projected to continue at a 10.51% CAGR through 2032, reaching an estimated USD 6,538.8 Million. This briefing highlights the strategic takeaways from the report while deliberately reserving granular segment-level tables to the full report to preserve the “trailer” experience — enough depth to act, but not the raw data that drives competitive advantage without purchase.
Built In Electric Curtains Market
Why this report matters for 2026
- Timing is critical: With the market more than doubling in less than a decade and a sustained high-single-digit to low-double-digit CAGR, procurement cycles and supplier lock-ins initiated in 2026 will determine cost and feature competitiveness into the early 2030s.
- Actionable differentiation: Built-in electric curtains are no longer a niche luxury — they are an integrative layer between smart-home ecosystems, building energy management, and design-led interior systems. The report maps concrete product and integration levers that move a product from “me-too” to “preferred” in channel and specification lists.
- Risk-to-reward clarity: PW Consulting quantifies exposure to trade and material policy shocks, concentration in supply, and standards-driven redesign costs — enabling CFOs to plan hedges, and product leaders to prioritize modularity and compliance budgets for 2026 releases.
What the full report delivers (executive summary of contents)
- Verified market sizing and growth path: historical reconciliations and a transparent forecast model covering 2026–2032 (base year 2025) with scenario toggles for demand shocks and regulatory shifts.
- Demand-driver analysis: segmentation of adoption vectors (residential retrofit vs. new-build commercial/institutional specifications), consumer willingness-to-pay studies, and installer economics.
- Supply-chain & cost build-up: BOM-level cost models, freight and duty sensitivity analysis, supplier tier maps, and cost-to-serve implications for integrated track and recessed solutions.
- Technology & integration playbook: motor architectures, quiet-drive design considerations, wireless interoperability roadmaps (including emerging smart-home standards), and battery/solar trade-offs for installation economics and service cycles.
- Competitive landscape and supplier archetypes: profiles of leading OEMs, ODM suppliers, and specialist track manufacturers — with capabilities matrices and partner-fit scoring (public summary profiles included; full competitive shares and split metrics retained in the report).
- Regulatory and standards impact assessment: compliance cost estimates, timeline for design changes, and recommended mitigation strategies to maintain install velocity and warranty economics.
- M&A, partnership and commercialization playbook: target-screen criteria, valuation multiples seen in analogous automation categories, and partnership templates for smart-platform integration.
Key market dynamics shaping 2026 strategies
- Rapid top-line expansion with concentrated suppliers: The market’s strong compound growth is paired with measurable concentration at the top—our competitive concentration metrics (CR3 and CR5) indicate that a small group of suppliers command a meaningful share of supply and specification influence. This creates both opportunity (scale partnerships) and risk (single-source exposure) for OEMs and integrators.
- Standards and safety as redesign drivers: The prevailing safety standards for window coverings (including ANSI/WCMA A100.1-2022) materially affect conversion strategies from manual to motorized systems. Compliance is not optional; it drives product architecture, testing cycles, and installer training programs.
- Trade & material pressures: Import duties on motors, fabrics, and aluminum extrusions — often ranging substantially by origin — and additional duties on certain structural components raise landed cost volatility. The report models duty bands and recommends procurement tactics (harmonized tariff classification strategies, dual-sourcing plans, and OTR inventory buffers) tailored for 2026 negotiations.
- Interoperability is a market gate: Smart-home standard alignment (Matter/Thread and platform APIs) and low-noise motor solutions are becoming decisive buying criteria in premium residential and specification-led commercial segments. Recent vendor activity (for example, the launch of Motionblinds’ Matter Bridge and smart showroom experience in April 2025) underscores how quickly integration capabilities translate to commercial traction.
Competitive landscape — who matters and why
The market is shaped by global motor and system specialists, shading platform providers, and dedicated track manufacturers. The report’s public summary highlights core firms and their strategic postures:
Built In Electric Curtains Market
- Somfy (Cluses, France) — A global leader in motorized window solutions with deep expertise in recessed and track-based integrated systems and mature smart-home integration stacks.
- Hunter Douglas (Rotterdam, Netherlands) — A premium window coverings maker with proprietary motorization systems targeted at custom and built-in applications across high-end residential and commercial projects.
- Lutron Electronics (Coopersburg, PA, USA) — Focuses on seamless shading and lighting integration, positioning motorized curtains as part of holistic room control systems for high-spec projects.
- Silent Gliss (Bern/Broadstairs) — Specialist track and quiet-motor solutions favored by architects and hospitality specifiers who prioritize acoustics and design integration.
- Coulisse / Motionblinds (Enter, Netherlands) — B2B smart-window player accelerating platform interoperability and UX (recently launched a Matter Bridge and enhanced showroom experiences to demonstrate integrated solutions).
- Dooya (Ningbo, China) — Global OEM/ODM supplier of tubular motors and components, a critical node in the upstream motor supply chain used by multiple system integrators and private-label manufacturers.
How to convert these insights into a 2026 playbook (practical steps)
- Run a supplier exposure audit: Use the report’s supplier heatmaps and duty-impact scenarios to identify single-source risks and quantify near-term landed cost increases under 10–25% duty bands.
- Prioritize integration features by segment economics: Map Matter/Thread and low-noise motor investments against customer lifetime value and specification win rates modeled in the report to allocate R&D budgets efficiently.
- Design for modular compliance: Adopt modular motor and control modules to accelerate requalification against standards like ANSI/WCMA A100.1-2022, reducing redesign cycle time and warranty exposure.
- Negotiate 2026 contracts defensively: Include indexation and duty-pass-through clauses, service-level agreements for retrofit projects, and options for co-investment in showroom or specifier engagement pilots.
- Plan for aftermarket and retrofit revenue: The fastest monetizable channel for many players in 2026 is the retrofit install; our go-to-market templates show how to price subscription-style maintenance and battery replacement services.
Limitations of the public brief & how to get the full dataset
In line with a “trailer” approach, this release showcases the report’s analytical depth but intentionally withholds granular subsegment tables (regional splits, power-source shares, and end-use breakout values) that drive competitive strategy and supplier negotiations. The full report contains those segment-level figures, downloadable forecast models in USD Million, supplier-by-sku matrices, and executable templates for procurement, product and channel leadership.
Built In Electric Curtains Market
Next steps
For corporate leaders preparing 2026 budgets, product roadmaps, or M&A screens: schedule a briefing with PW Consulting to review the full dataset and scenario models. Our clients typically walk away with a prioritized list of 3–5 near-term interventions (procurement, product, and partnership) that materially alter cost curves and specification wins for the 2026–2028 window.
If your team needs a focused pre-read: request the two-page operational annex which summarizes supplier exposure, a mitigation checklist for trade and standards risk, and a short-list of partnership targets tailored to your corporate profile. Visit PW Consulting’s report page or contact our advisory desk to arrange an access briefing and obtain the full Built-In Electric Curtains Market report and accompanying models.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com