

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Paper Coaster Market to Rise from USD 530.0 Million in 2025 to USD 807.51 Million by 2032 at a 6.2% CAGR

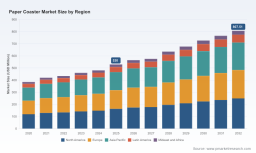
Paper Coaster Market — 2026 Strategic Briefing (PW Consulting)
PW Consulting’s new Paper Coaster Market report (base year 2025; historical 2020–2025; forecast 2026–2032) delivers the market intelligence executives need to make informed, high‑stakes decisions in 2026. The market has expanded from approximately USD 385.5 million in 2020 to USD 530.0 million in 2025 and is modelled to reach roughly USD 807.5 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.2% over the forecast window. This briefing summarizes the strategic takeaways from the full report — revealing methodology, dynamics, and actionable direction — while reserving detailed segment-level figures and proprietary model outputs for subscribers and report purchasers.
Why this report matters for 2026 decision cycles
- Investment prioritization: The steady mid‑single‑digit CAGR signals a market where targeted product, sustainability, and supply‑chain bets can achieve outsized returns versus undifferentiated capacity expansion.
- Cost and margin management: Input price volatility and evolving regulatory cost pools (notably EPR frameworks) are shifting unit economics; manufacturers and brand owners must re‑price, redesign, or re‑negotiate supplier terms to protect margins.
- Opportunity identification: Fragmented concentration (CR3 ~18.5%; CR5 ~28.3%) creates acquisition and partnership windows for scale buyers, especially those that can combine manufacturing, printing technology, and distribution reach.
- Compliance and risk mitigation: Emerging EPR regimes in several U.S. states and evolving international packaging policy demand early compliance planning to avoid retroactive cost exposure and supply disruptions.
What the full report contains (practical, operational deliverables)
- Proprietary market model — top‑down and bottoms‑up scenarios with sensitivity analysis for raw material and demand shocks (available at variable fidelity levels; headline aggregate figures are summarized above).
- Segment economics playbooks — SKU and material profitability templates, cost-to-serve matrices, and design‑to‑cost recommendations for virgin vs. recycled fiber platforms.
- Supply‑chain diagnostics — regional sourcing risk heatmaps, vendor scorecards, and a short‑list of resilient near‑sourcing alternatives to lower lead times and freight exposure.
- Regulatory & EPR readiness framework — compliance timeline, likely fee structures, and a checklist to operationalize producer obligations across phased programs through 2030–2032.
- Commercial go‑to‑market toolkits — channel segmentation, promotional bundling tactics for hospitality and retail channels, and branding/printing options to preserve premium positioning while lowering unit cost.
- Competitive vendor dossiers — capability maps, technology differentiators (e.g., UV spot gloss, foil stamping, Airlaid materials, PE‑backed liners), and acquisition defensibility analyses for the leading suppliers in North America, Europe and China.
- Scenario readiness playbook — three stress test scenarios and recommended mitigations addressing raw material spikes, trade disruptions, and accelerated sustainability mandates.
Market dynamics: drivers, headwinds and inflection points
Demand drivers in the near term remain linked to recovery and reinvestment in hospitality, promotional merchandise budgets, and the broader shift toward single‑use, low‑cost brand touchpoints. On the supply side, several factors are converging:
- Raw material cost dispersion — Paperboard input costs continue to vary materially by region. In March 2026 our tracking found a marked spread between lower‑cost North American paperboard and higher‑cost Southeast Asian suppliers; buyers should revalidate landed cost assumptions in all sourcing decisions.
- PPI stability and manufacturing throughput — The U.S. Producer Price Index for corrugated and paperboard products showed relative stability through early 2026, which dampens the probability of abrupt domestic input cost shocks but does not eliminate downstream margin pressure once EPR fees are included.
- Regulatory acceleration — As of 2025–2026 several U.S. states have enacted comprehensive Extended Producer Responsibility laws covering packaging and paper products. These laws change the cost calculus for producers through mandatory financing of collection and end‑of‑life management and will introduce new administrative and compliance burdens that must be costed into 2026 product plans and pricing.
- Fragmentation and innovation — The sector remains fragmented, with a broad base of regional manufacturers and a small number of larger players. This structure favors nimble manufacturers that can win custom printing contracts, leverage specialty finishes, or deliver sustainable product variants with credible lifecycle claims.
Competitive landscape — who to watch and why
The competitive field is a mix of direct pulpboard manufacturers, specialty material players, and contract printers/distributors. Our qualitative assessment of core players highlights differentiated strategic positions:
- Coaster Factory (United States) — Direct North American manufacturer focused on high‑volume pulpboard coasters with advanced printing and finishing capabilities (UV spot gloss, foil stamping, specialty shapes). Strengths: scale production for hospitality chains and promotional programs, fast turnaround for bulk orders. Strategic implication: ideal supplier for buyers prioritizing customization and short lead times; potential partner for private‑label consolidation.
https://www.coasterfactory.com/ - Alfred Mank (Germany; Linclass® Airlaid expertise) — Specialist in absorbent tissue, Airlaid materials and polymer‑backed products. Strengths: material innovation (superior moisture handling), strong European hospitality credentials. Strategic implication: purchase or partnership consideration for premium, performance‑led coaster SKUs and event/hospitality channels where functionality justifies price premium.
https://www.alfredmank.com/ - Hoffmaster (United States) — Established pulpboard and budgetboard producer with a broad product range and multi‑format offerings. Strengths: product breadth and recognized North American supply relationships. Strategic implication: stable supplier for standardized SKUs and private‑label programs where reliability and scale trump high‑end customization.
https://www.hoffmaster.com/ - Totally Promotional (United States) — Promotional goods specialist offering full‑color imprinting and biodegradable product focuses. Strengths: channel expertise in promos and events, eco‑positioning. Strategic implication: partner of choice for marketing‑led campaigns and promotional buyers seeking design flexibility with sustainability claims.
https://www.totallypromotional.com/ - Singreen Package & Guangzhou Zhi Xiang (China) — Cost‑competitive exporters supplying bulk custom coasters and absorbent variants for global wholesale. Strengths: low unit cost for large runs and flexible customization. Strategic implication: attractive for price‑sensitive large‑volume orders but require diligence on lead times, quality consistency, and sustainability/test certifications for developed‑market buyers.
https://www.singreenpackage.com/
Implications for 2026 strategy and operating plans
PW Consulting’s analysis translates market signals into a short list of priority actions for manufacturers, brand owners, distributors, and private equity investors planning moves in 2026:
- Embed EPR into pricing and contractual terms now — update cost models, contractual cost‑pass through clauses, and customer price lists to reflect phased producer responsibilities rather than waiting for final fee schedules.
- Re‑tool sourcing playbooks — re‑price landed cost scenarios monthly, increase dual‑sourcing for paperboard, and evaluate nearshoring for quick‑turn promotional business to reduce freight and tariff exposure.
- Segment rationalization and SKU simplification — identify low‑velocity, low‑margin SKUs for phase‑out or redesign to recycled/mono‑material constructs to lower recycling fees and simplify compliance reporting.
- Differentiate through finishing and materials — invest selectively in finishing capabilities (spot varnish, foil, Airlaid absorbents) that secure higher margins and make substitution harder for commoditized suppliers.
- Prepare M&A and partnership scouting — with low industry concentration, 2026 is a window for strategic acquirers to add complementary capacity (printing, specialty materials, or distribution) at attractive multiples.
- Operationalize circularity pilots — run regionally limited take‑back and verified recycled content programs now to gather cost and collection data ahead of mandatory EPR timelines.
How PW Consulting’s report supports execution
The full Paper Coaster Market report includes downloadable models, procurement negotiation playbooks, a compliance checklist mapped to state‑level EPR timelines, and vendor scorecards with capability matrices. We intentionally limit the release-level disclosure here (no granular regional or application splits are presented in this briefing) to protect the proprietary benchmarking that enables the rapid translation from insight to action.
Next steps
- For procurement teams: request the supplier scorecard and landed cost scenario pack to run a 90‑day sourcing refresh.
- For product and R&D leads: obtain the material performance matrix and design‑to‑cost templates to pilot two redesigned SKUs with recycled/mono solutions.
- For C‑suite and investors: schedule a strategy workshop to align M&A, pricing, and EPR readiness across corporate planning and FY‑2027 budgets.
To access the full dataset, detailed segment tables, and the interactive forecast model, please contact PW Consulting or visit our Paper Coaster Market report page. The complete report contains the granular regional and application splits, vendor share estimates, and the proprietary spreadsheets necessary to operationalize the insights summarized here.
For detailed analysis of this topic, please visit the official page: Paper Coaster Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com