

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Wafer Purge System Market Poised to Grow at a 9.5% CAGR from 2026–2032

Wafer Purge System Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As semiconductor manufacturers accelerate node transitions and expand capacity, control of in-process contamination has moved from a cost center to a strategic enabler. PW Consulting’s latest Wafer Purge System Market Research Report — grounded in a rigorous 2020–2025 historical analysis and a 2026–2032 forecast horizon — quantifies this shift and translates it into concrete moves for executives planning 2026 capital allocation, supplier strategy, and fab-operational optimization.
Wafer Purge System Market Research
Market snapshot: expanding opportunity, predictable trajectory
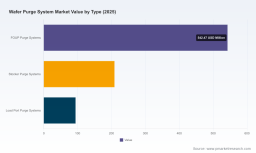
The wafer purge systems market has moved from a niche reliability playbook into an integral part of advanced-node yield engineering and fab ecology. Our analysis places the market at roughly USD 845.5 Million in the 2025 base year, having expanded steadily since 2020, and growing at a compound annual growth rate of approximately 9.5% into the forecast window. Under the scenarios modeled in this report, total market value is projected to continue its upward trajectory through the 2026–2032 period, reflecting rising fab throughput, larger FOUP/stocker fleets, and intensified interest in retrofits and low-energy purge technologies.
Wafer Purge System Market Research
Why this report matters for 2026 decision-making
-
Strategic capital prioritization: With constrained CAPEX cycles in many foundries and IDM expansions, procurement leaders must distinguish between “nice-to-have” and mission-critical purge investments. Our report provides scenario-based ROI horizons tied to node maturity, throughput profiles, and cleaning/yield uplift assumptions — enabling CFOs and fab managers to rank investments by payback and risk.
Wafer Purge System Market Research -
Procurement and supplier risk management: The supplier landscape is increasingly concentrated, with a small set of specialized suppliers capturing a material portion of installed systems. Our concentration analysis and supplier profiles enable procurement teams to construct multi-vendor sourcing strategies and to negotiate terms protecting supply continuity and IP-sensitive integration paths.
-
Operational TCO and sustainability: Nitrogen consumption is both an operating cost and an environmental lever. The report quantifies consumption drivers and presents low-energy technology adoption scenarios — from advanced nozzle design to piezo-based flow control — that materially compress TCO and carbon intensity without compromising oxygen/humidity control.
-
Compliance and trade considerations: Export controls and safety regulations are tightening in key markets. We map regulatory touchpoints (including applicable equipment controls under major export frameworks and SEMI S2 emissions-guidance implications) and outline mitigations for cross-border procurement and aftermarket services.
-
Retrofit vs greenfield calculus: Not every performance uplift requires a full equipment replacement. Our practical decision framework quantifies when retrofits (load port modules, purge smart-charges, or stocker retrofits) deliver faster ROI versus when full-system replacements are justified by throughput and miniaturization demands.
What’s inside the report — operational playbooks, not just slides
-
Methodology and granular market model: Transparent assumptions, scenario variants (conservative, base, accelerated), and an interactive forecast engine that executives can adapt to site-level parameters.
-
Practical deployment checklists: Detailed pre-installation and qualification steps, environmental and interface requirements, and integration guidance for AMHS/EFEM systems to minimize production interruption during commissioning.
-
Supplier dossiers and procurement templates: Independent technical appraisals of leading suppliers, standardized RFP language for purge systems and retrofit modules, and SLA/acceptance-test templates aligned with fab qualification milestones.
-
Operational calculators and TCO templates: Models to quantify nitrogen consumption, OPEX trade-offs, and scenarios showing when reduced purge flow or improved nozzle efficiency can change multi-year payback.
-
Adoption playbooks: Role-based guidance (CFO, Head of Manufacturing, Supplier Management, EH&S) for implementing a staged purge-improvement program across multiple fab sites.
Competitive landscape: capabilities, differentiation, and what to watch
The market’s technology arms race is focused on two parallel vectors: minimizing gas consumption while achieving ultra-low oxygen/humidity at the wafer surface, and delivering modular, retrofit-capable hardware that integrates with existing stockers, load ports, and FOUP handling systems. Below is a synthesized view of the core vendors analyzed in our report and the strategic differentiators they bring to 2026 procurement conversations.
-
Fabmatics (Germany) — Renowned for retrofittable Wafer Pod Purge Systems that serve FOUP and SMIF pods. Their field-proven installations and modular approach make them an attractive partner for fabs seeking minimal-disruption retrofits and broad pod-compatibility in overhead buffer and stocker environments.
-
Murata Machinery (Muratec, Japan) — Focused on thin purge retrofit units, mass flow control, and high-efficiency nozzle designs. Their offerings emphasize integration simplicity for existing stockers and strong control over oxide and moisture metrics.
-
Rorze Corporation (Japan) — Delivers high-density N2 purge stockers and bottom-purge load port modules. Rorze’s nozzle mechanisms and flow-optimization focus are relevant for fabs prioritizing per-FOUP flow efficiency and cleanliness at high automation densities.
-
Palbam Class (Israel) — Specializes in FOUP/SMIF pod purging stations and ultraclean N2 cabinets, with automation and desiccant-combination options for controlled storage. Their automated control stacks help simplify operational adoption in cleanroom environments.
-
Daifuku (Japan) — Integrates nitrogen purge storage with AMHS, positioning for large-scale 300mm fab deployments where systems-level coordination across logistics and storage is required.
-
Sinfonia Technology (Japan) — Offers smart load ports with movable nozzles and filtration options, enabling localized control at the FOUP interface and flexible EFEM/Sorter integrations.
-
Kostek Systems (South Korea) — Load port modules and EFEM-level purge options that emphasize host communications and O2 monitoring — attractive where traceability and process control are non-negotiable.
-
Santa Phoenix Technology (SPTI, Taiwan) — Develops advanced N2 chargers and carrier storage units, with demonstrated deployments at major foundries; their solutions are oriented to high-throughput 300mm environments.
-
SEMI-TS (South Korea) — Presents smart purge systems as part of AMHS stacks and has been visible at trade shows promoting integrated clean conveyor and purge LP solutions.
Collectively, the vendor set demonstrates differentiation across retrofit capability, nozzle/flow innovation, systems integration, and fleet-scale management. Our CR analysis shows that market share is concentrated among a handful of providers — an important negotiating dynamic when planning multi-site rollouts.
Recent signals and technology inflection points
-
Field scale: Documented nitrogen purge applications in overhead buffers and pod purge systems have reached sizable installed bases for some vendors, indicating maturity in retrofit programs and validated operational benefits in real production environments.
-
Energy and gas efficiency: New flow-control hardware — including low-energy piezo-based valves — has demonstrated substantial reductions in nitrogen consumption in laboratory and early production trials. When paired with improved nozzle designs and MFC-enabled pre-purging, these advances materially lower OPEX and increase the feasibility of rolled-out purge programs across constrained budgets.
-
Exhibitions and market visibility: Suppliers are increasingly positioning purge systems as part of broader AMHS and clean-conveyor messaging, signaling a move toward holistic logistics + contamination control solutions rather than point-product sales.
Risks and operational headwinds
-
Raw material cost pressure: Stainless steel and sensor components remain significant cost drivers for purge equipment manufacturing, and recent upward cost trends warrant procurement hedging and supplier cost-pass-through clauses in multi-year agreements.
-
Regulatory overlay: Compliance with SEMI S2-like guidelines and export control regimes requires advance planning for certification timelines and cross-border services, especially for vendors supporting front-end production in controlled destinations.
-
Integration complexity: While retrofits shorten deployment lead times, interface management with AMHS/EFEM and host O2 monitoring systems requires disciplined qualification and acceptance test plans to avoid production disruption.
Five pragmatic actions for 2026
-
Run a rapid pilot using low-energy flow-control modules on a constrained FOUP fleet to validate nitrogen savings and yield impact within a single product line — target a 6–12 month evaluation window to minimize timing risk.
-
Embed purge-system clauses into wafer-handling CAPEX and spare-part contracts to secure long-term pricing and spare availability given supplier concentration dynamics.
-
Prioritize retrofit paths for legacy stockers and load ports where the internal ROI model (including reduced cleaning cycles) shows payback within your 3-year planning horizon.
-
Coordinate EH&S and export-control stakeholders early in procurement to ensure compliance testing and cross-border service agreements do not delay installations or spare delivery.
-
Use a staged rollout plan aligned to node transitions, putting the highest-purity, most automated lines first; defer lower-priority lines until proof from initial deployments is attained.
PW Consulting’s Wafer Purge System Report is designed to be an executive-grade decision tool: deep enough to inform procurement and operations teams, and pragmatic enough to be executable in 2026 budgets and timelines. For detailed vendor scorecards, the interactive forecast model, and the deployment playbooks referenced above — including the full dataset and appendices that break down our segmentation and site-level assumptions — please visit the report landing page on PW Consulting’s website to access the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Wafer Purge System Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com