

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Orthodontic Aids Market to Expand at an 8.45% CAGR as Clear Aligners and North America Drive Growth

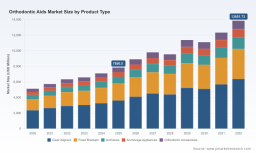
Orthodontic Aids Market — 2026 Strategic Outlook (PW Consulting)
Executive summary
PW Consulting’s latest Orthodontic Aids Market report synthesizes five years of historical performance (2020–2025) and a seven‑year forecast (2026–2032) to deliver prescriptive guidance for executive decision makers entering 2026. The market we track expanded from approximately USD 5.12 billion in 2020 to USD 7.85 billion in 2025, and is projected to grow at a compound annual growth rate (CAGR) of 8.45% over the 2026–2032 forecast window — reaching an estimated USD 13.85 billion by 2032. These headline figures frame a market that is simultaneously maturing and being reshaped by digitization, regulatory tightening, care‑delivery reconfiguration, and new competitive moves from both incumbent device manufacturers and digitally native entrants.
Orthodontic Aids Market
Why this report matters to 2026 strategy
-
Timing: 2026 is a pivot year — investments made now in digital workflows, regulatory preparedness, and reimbursement coding adaptation will determine who captures the next wave of treatment volumes as payors and regulators adjust to new modalities.
Orthodontic Aids Market -
Decision focus: The report converts macro momentum into actionable choices across commercial strategy, R&D prioritization, M&A targeting, and supply‑chain resilience — all calibrated to an 8.45% growth trajectory and observable concentration among leading suppliers.
Orthodontic Aids Market -
Risk mitigation: We map regulatory and reimbursement shifts to product lifecycles so you can preempt go‑to‑market disruption from device reclassification, new CDT codes, or market access constraints.
Market trajectory and structural snapshot
After a steady recovery and expansion between 2020 and 2025, the orthodontic aids market enters a higher‑growth chapter. Our base‑year analysis contextualizes the USD 7.85 billion 2025 market and projects a meaningful acceleration in 2026, with the market crossing well into the multi‑billion USD range in the forecast’s early years. Growth over the period reflects a mix of unit volume gains (driven by rising treatment uptake and expanded indications), product premiumization (a continued tilt toward aesthetic/digital solutions), and rising ASPs in select subsegments tied to proprietary digital platforms.
Industry structure remains moderately concentrated. The top three competitors account for roughly half of the market by revenue, and the top five approach nearly seven‑tenths of the market — a dynamic that shapes pricing discipline, channel leverage, and M&A appetite. At the same time, pockets of fragmentation persist in consumables and regional distribution, creating acquisition targets and partnership opportunities for larger platforms seeking end‑to‑end offerings.
Competitive dynamics — what to watch
-
Platform incumbents: Firms with integrated digital platforms and proprietary workflows (scanning, planning, manufacturing) are turning clinical scale into margin leadership. Regulatory clearances for next‑generation attachments and expanders strengthen their clinical moat and expand the treatable patient set.
-
Traditional device vendors: Established manufacturers with broad fixed‑appliance portfolios continue to defend core channels (orthodontists, DSOs, hospitals) and benefit from recurring consumables demand. Their playbook emphasizes operational efficiency, distribution depth, and selective innovation in aesthetic brackets and archwires.
-
Emerging digital entrants and AI providers: New approvals for AI‑enabled imaging and diagnostic tools enable faster treatment planning and remote monitoring — features that accelerate adoption of aligner‑centric care models and create cross‑selling paths into software and subscription services.
Recent industry developments underscore these themes: leading aligner platform providers have secured regulatory clearances for new attachment and palatal expansion systems, AI imaging solutions obtained 510(k) authorizations that accelerate digital workflow integration, and product launches in aesthetic bracket technologies continue to expand clinician choice. Concurrently, direct‑to‑consumer aligner models have seen regulatory and commercial retrenchment in some markets, reinforcing the value of clinician‑led models and regulatory compliance as competitive differentiators.
Regulatory and reimbursement landscape — operational imperatives
-
Device regulation: Clear aligners, brackets and related appliances are regulated largely as Class II medical devices in major markets. A proactive regulatory roadmap — including 510(k) strategy in the U.S. and MDR/CE conformity in the EU — is table stakes for any product launch or market expansion.
-
Reimbursement changes: The 2026 revisions to CDT codes in the U.S. alter coding pathways for orthodontic services. Manufacturers and providers must align clinical evidence generation and billing workflows to realize capture of incremental value from new or re‑scoped codes.
-
Market access nuance: Regional differences in regulatory proof and payor acceptance mean that a single global product strategy will underperform; successful actors localize clinical evidence, training, and commercial models.
Report contents — what’s inside (practical deliverables)
The PW Consulting Orthodontic Aids Market report is built for executables. Highlights include:
-
Granular market model (2020–2032) with base‑case, upside and downside scenarios; customizable Excel model to support sensitivity testing and M&A valuation run‑downs.
-
Commercial playbooks for aligners, fixed appliances, archwires and consumables, including channel economics, pricing templates, and sales incentive designs.
-
Competitive matrices profiling product portfolios, differentiators, regulatory status and IP positions for the industry’s leading firms.
-
Regulatory checklist and go‑to‑market timing calendar aligned to FDA/MDR expectations and 2026 CDT code updates.
-
Supply‑chain stress tests and sourcing maps that quantify inventory exposure and single‑source risks across manufacturing geographies.
-
Strategic M&A target shortlists with deal rationale, integration considerations and expected synergies tailored to platform and bolt‑on buyer archetypes.
To preserve commercial value for subscribers, the report intentionally withholds a small subset of proprietary segment tables and regional breakdowns in public summaries — deliberate design to ensure actionable, proprietary insight remains available to licensed clients.
Strategic recommendations for 2026 (executive checklist)
-
Prioritize digital workflow integration: Invest in scanner and AI partnerships to shorten time‑to‑treatment, reduce lab costs, and lock in clinicians to platform ecosystems.
-
Accelerate regulatory readiness: Fast‑track 510(k) or MDR dossiers for novel attachments and adjunct devices; allocate budget for post‑market surveillance and clinician training that regulators will expect.
-
Adapt commercial models to new codes: Map updated CDT codes to revenue flows, redesign field incentives, and pilot billing bundles with large DSOs and payors.
-
Target bolt‑on acquisitions in consumables and regional distribution: Use acquisitions to shore up price elasticity in mature channels and obtain on‑the‑ground access in high‑growth geographies.
-
Design clinician retention programs: Shift from transaction to subscription economics by bundling hardware, software and consumables with outcome‑based guarantees or shared savings models.
Scenario implications and KPIs
We model three plausible 2026–2028 scenarios — base (policy and adoption trends continue), upside (accelerated adoption of digital treatment pathways and favorable reimbursement), and downside (regulatory friction and DTC retrenchment). For each, the report maps leading KPIs: average selling price movements, unit volumes by channel, clinician adoption rates for digital tools, and margin sensitivity to raw material and labor cost fluctuations. Senior leaders can use these KPIs to set stretch targets, capital allocation thresholds, and M&A valuation frameworks.
Competitive brief: companies to watch
Our competitive analysis highlights a mix of platform leaders, traditional OEMs, and regional specialists. Platform leaders are extending clinical functionality through cleared attachments and digital add‑ons; traditional OEMs are defending installed bases with incremental product innovations in brackets and archwires; and regional players remain attractive consolidation targets for buyers seeking scale in specific channels. The market’s top three and top five firms capture a material share of revenues — a concentration that favors integrated offerings but leaves whitespace in localized consumables and service offerings.
How to use this research
If you are a CEO, C‑level growth lead, corporate development executive, or head of R&D, this report is structured to support:
-
Board‑level debates on growth vs. consolidation and capital deployment;
-
Commercial pilots with DSOs and hospital networks to validate new bundles;
-
Regulatory and clinical evidence roadmaps to accelerate market clearances;
-
M&A diligence and integration planning using our ready‑to‑use valuation models.
Final note — what we do not reveal here
In this public briefing we present the market trajectory, concentration indicators, and strategic implications that matter for 2026. We intentionally omit a subset of proprietary segmentation tables, precise regional and application revenue splits, and transaction‑level valuations that are included only in the licensed report and interactive Excel model. PW Consulting clients receive the full dataset, drillable dashboards, and direct analyst support to translate findings into executable plans.
Next steps
To obtain the full report, the complete market model, and a tailored half‑day briefing with our lead analysts and industry practice partners, please contact PW Consulting’s Orthodontics practice. We will walk your senior team through the scenarios, stress‑test your strategy, and produce a 90‑day playbook to start capturing growth in 2026.
For detailed analysis of this topic, please visit the official page: Orthodontic Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com