

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Semi Direct Drive Wind Turbine Market to Grow at a 12.02% CAGR — New Market Insights Released

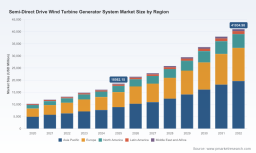
Semi Direct Drive Wind Turbine Generator System Market — Strategic Outlook for 2026 Decision-Making
PW Consulting today publishes a focused industry briefing accompanying our full market research report on the Semi Direct Drive Wind Turbine Generator System (WTGS) market. Grounded in a robust historical series (2020–2025) and a seven-year forecast window (2026–2032), the analysis quantifies a clear growth trajectory: the global semi-direct drive WTGS market is estimated at USD 18,562.15 Million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 12.02% through 2032, reaching USD 41,034.98 Million by that year. This briefing explains why the dataset, scenario workstreams, and competitive benchmarking in the full report are indispensable inputs for strategic decisions in 2026.
Semi Direct Drive Wind Turbine Generator System Market
Executive snapshot — strategic headlines
- Growth momentum: Double-digit CAGR through 2032 reflects accelerating adoption of medium-speed drivetrains in large-megawatt offshore projects and an expanding role in selected onshore applications.
- Technology positioning: Semi-direct drive solutions now occupy the value sweet spot between full direct-drive and high-speed geared systems — delivering lower rare-earth exposure per MW, improved transmission efficiency, and suitability for both fixed-bottom and floating platforms.
- Competitive structure: The market displays meaningful concentration among a small set of OEMs, yet technical complexity and supply-chain specialization create windows for component specialists and regional challengers.
- Material & supply-chain sensitivity: Permanent magnet material dynamics (including NdFeB pricing and rare-earth content reduction strategies) are a primary cost and risk lever for OEMs and suppliers.
- Investment implications: Capital allocation decisions hinge on trade-offs between scale (large-capacity platforms), integration (in-house vs. supplier partnerships), and exposure to magnet price volatility.
Why this report matters for 2026 decisions
- Portfolio prioritization for developers: Use our market-sizing and deployment scenarios to decide whether to prioritize semi-direct drive platforms for new offshore tenders or to retain a diversified drivetrain mix.
- OEM product strategy: Our technology readiness and cost model helps OEMs evaluate investments in medium-speed architectures, hybrid drivetrains, and generator-gearbox integration to optimize LCOE and serviceability targets.
- Supply-chain risk management: The report provides supplier maps, critical-path component concentration analyses, and material-price sensitivity testing to inform procurement, hedging, and vertical-integration choices.
- Investor diligence: Private equity and infrastructure investors can leverage our scenario-driven valuation templates to test downside scenarios linked to magnet pricing, permitting delays, or slower-than-expected floating wind adoption.
- M&A and partnership scouting: Competitive benchmarking and capability matrices identify attractive targets — component innovators, gearbox specialists, and niche turbine OEMs — that can accelerate time-to-market for semi-direct concepts.
- Regulatory & policy navigation: The analysis highlights how evolving grid codes and offshore permitting regimes affect technology selection and project timelines across major sourcing markets.
What the full report delivers — practical, transaction-ready content
- Transparent market model: Historical (2020–2025) actuals and a granular forecast (2026–2032) with scenario toggles (base, constrained supply, accelerated adoption) and sensitivity to magnet pricing.
- Go-to-market playbooks: Step-by-step decision frameworks for developers and OEMs covering product positioning, regional entry sequencing, and partner selection.
- Cost and LCOE module: Component-level build-up of capital cost, O&M trajectories, and break-even pathways under alternative material-cost regimes.
- Supply-chain maps and risk heatmaps: Identification of single points of failure, supplier concentration metrics, and mitigations including inventory strategies and dual-sourcing options.
- Competitive benchmarking & scorecards: Dealer and OEM profiles, innovation indexes, and manufacturing footprint assessments tied to strategic options (license, joint-venture, acquisition).
- Technology readiness and R&D priorities: Comparative assessment of drivetrains, grid-interface solutions, and floating-platform integration challenges with recommended R&D roadmaps.
- Investment cases & M&A pipeline: Valuation proxy tables, integration cost estimates, and a prioritized list of acquisition or JV targets (qualitative previews included in this briefing; full targets and valuation worksheets available in the report).
- Regulatory & permitting playbook: Country-by-country checkpoints for offshore permitting, environmental constraints, and local content implications for procurement and project finance.
Competitive landscape — what leading and emergent players signal
-
Ming Yang Smart Energy Group Co., Ltd. — Ming Yang has positioned itself as a global focal point for semi-direct drive innovation, with product architectures targeted at medium-speed compact drivetrains and models engineered for extreme conditions. Recent product disclosures, including an expanded medium-speed compact drive (MCD) family and a conceptual 50 MW floating platform, indicate an aggressive push up the value chain: combining platform scale with drivetrain specialization. Strategic implication: partners and investors should watch Ming Yang for system-level innovations that can reset cost and installation benchmarks in floating offshore segments.
Semi Direct Drive Wind Turbine Generator System Market -
Dongfang Electric Corporation (DEC) — DEC’s work on third-generation fully integrated semi-direct drive systems exemplifies a vertically integrated approach, combining shaft systems, gearboxes, and in-house permanent magnet generators into highly integrated prototypes. The installation of large-capacity prototypes demonstrates technical maturity and signals a competitive move toward very large turbines where integration provides lifecycle advantages. Strategic implication: alliances or supplier contracts with integrated OEMs may yield faster route-to-market for large-platform projects, but buyers should carefully evaluate lock-in and supplier negotiation leverage.
Semi Direct Drive Wind Turbine Generator System Market -
Goldwind Science & Technology Co., Ltd. — Goldwind’s transition in parts of its portfolio from pure PM direct-drive to medium-speed hybrid drivetrains reflects broader industry hedging: balancing magnet usage, weight, and gearbox complexity. This mixed-architecture strategy gives Goldwind flexibility across project types and suggests that OEMs adopting hybrid portfolios can sustain competitiveness across shifting material-price and logistical landscapes.
-
Yinchuan Weili Transmission Technology Co., Ltd. — As a specialist in integrated speed-increaser components, Yinchuan Weili highlights where component innovation can unlock system-level performance gains. Compact, lightweight medium-speed gearbox solutions that effectively bridge the impeller and permanent magnet generator reduce nacelle mass and can lower balance-of-plant constraints for large turbines. Strategic implication: component suppliers with proven integration IP are attractive partners for OEMs seeking to accelerate design cycles without internalizing full manufacturing risk.
Supply chain, raw materials and regulatory dynamics
Two material facts require immediate attention in procurement and R&D planning. First, semi-direct drive permanent magnet generators typically require materially less NdFeB mass relative to full direct-drive equivalents; published engineering comparisons indicate an approximate 25% reduction in magnet mass per generator when leveraging medium-speed architectures. Second, mid-grade sintered NdFeB pricing in 2025 sat in a narrow range that materially affects component cost curves — creating a clear arbitrage and hedging imperative for OEMs and buyers. Separately, industry dynamics show medium-speed drivetrains increasing market share over recent years, driven largely by adoption among major Chinese manufacturers and a broader industry shift toward designs that reduce rare-earth intensity. For 2026 planning this means procurement strategies should include price scenario modeling, recycled-rare-earth sourcing, and engagement with magnet manufacturers on long-term offtake or co-investment structures.
Market concentration and competitive implication
The semi-direct drive WTGS market demonstrates notable concentration: the top three players control a majority share of the market, and the top five represent a substantial further tranche of market capacity. This structure produces a mixed strategic environment: on one hand established OEMs have scale advantages in certification, supply-chain certainty, and balance-sheet capacity for capex-intensive pilots; on the other hand the complexity of drivetrain integration and the emergence of component specialists create niches where focused entrants can capture premium margin or strategic supplier positions. For acquirers, this points to a prioritized target list: component innovators, engineering services with marine/wind integration expertise, and geographically differentiated manufacturing capabilities.
How to use the report in your 2026 playbook
- Embed the report’s scenarios in your 2026 budgeting cycle to test capital allocation across platform R&D, secured component supply, and pilot projects.
- Run one-page investment memos for each strategic initiative (e.g., floating semi-direct pilot, co-developed generator modules, or a magnet recycling JV) using our valuation templates.
- Initiate supplier dialogues with structured term sheets based on the procurement levers and price-sensitivity outputs provided in the report.
- Prioritize regulatory and consenting resources for offshore projects where semi-direct drive platforms are slated for tender participation in 2026–2027 windows.
Next steps & how to access the full intelligence
This briefing provides a concise strategic frame. For decision-makers requiring transaction-level detail — including full regional and application splits, vendor scorecards, configurable market-model spreadsheets, and M&A valuation worksheets — please refer to the full PW Consulting report and data pack. The full report contains the granular tables and scenario matrices necessary to operationalize the strategies outlined above and is designed to be used directly in board-level and investment-committee decision cycles for 2026 planning.
PW Consulting’s semi-direct drive WTGS research is the practical intelligence tool for 2026: supporting capital allocation, product strategy, procurement risk mitigation, and M&A scouting in a market where technology, materials, and platform-scale will determine the next wave of winners.
For detailed analysis of this topic, please visit the official page: Semi Direct Drive Wind Turbine Generator System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com