

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Multi‑Use Cleaner Market Forecast (2026–2032) — Set to Rise from USD 8.8 Billion in 2025 to USD 12.06 Billion by 2032 at a 4.61% CAGR; Liquids, Residential Demand and North America Lead as Top 5 Firms Capture 52%

PW Consulting Strategic Brief: Multi‑Use Cleaner Market — What 2026 Leaders Must Know
Executive summary
The global multi‑use cleaner market stands at a pivotal inflection point. According to PW Consulting’s latest market model, the market reached approximately USD 8,800 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.61% across the 2026–2032 forecast window, with a 2032 endpoint that underscores meaningful upside for well‑positioned players. For executive teams planning 2026 budgets, product roadmaps, M&A screening, or procurement strategies, this report delivers the empirically grounded, scenario‑based guidance needed to convert macro momentum into defensible, near‑term advantage.
Multi Use Cleaner Market
Why 2026 is decisive
-
Cost and margin pressure have become structural. Feedstock volatility — exemplified by divergent Linear Alkyl Benzene (LAB) pricing across trading hubs (Industry Market Data, Mar 2026) — is compressing gross margins for formula‑intensive SKUs and forcing re‑trade conversations across supplier chains. Leaders that pre‑emptively model these swings will preserve margin and commercial flexibility.
Multi Use Cleaner Market -
Regulatory and sustainability signals are accelerating product‑level reformulation. Certification programs such as the U.S. EPA Safer Choice are moving from differentiator to procurement prerequisite in several institutional channels, reshaping specification and tender outcomes.
Multi Use Cleaner Market -
Channel and format evolution is fragmenting historic volume pools. E‑commerce penetration, refill/refillable packaging experiments, and format innovation (concentrates, sprays, wipes) are changing cost‑to‑serve dynamics and creating new capture levers for both incumbents and agile challengers.
-
Competitive consolidation is moderate but strategic: the market shows meaningful scale concentration among a small set of global players while still leaving runway for niche specialists and regional champions to grow via targeted innovation or channel mastery.
What the PW Consulting report delivers (practical, decision‑ready content)
-
Market architecture and demand model — a purpose‑built bottom‑up model that reconciles consumption, channel flows, and price trajectories across our 2026–2032 scenarios.
-
Scenario planning toolkit — three operational scenarios (baseline, downside raw‑material shock, accelerated sustainability premium) with P&L and working capital impacts by product family.
-
Raw material risk matrix — quantified exposure to surfactant feedstocks and packaging resins, with actionable hedging and supplier diversification playbooks.
-
Regulatory and procurement playbook — mapping of major certification regimes and their procurement implications for commercial tenders and retail shelf entry.
-
Go‑to‑market and product portfolio optimization — SKU rationalization frameworks, pricing elasticity tests, and channel mix optimization models tailored for 2026 priorities.
-
Competitive benchmarking and M&A screening — a proprietary scoring system that ranks targets by synergy potential, integration risk, and value creation timeline.
-
Executive dashboards and workshop materials — ready‑to‑use slides and an interactive model to accelerate board‑level decisions.
Competitive landscape — what the leading players are doing (and what it means for you)
The multi‑use cleaner arena is defined by a mix of global consumer goods giants, specialist institutional providers, and regional formulators. Market concentration metrics indicate a meaningful presence of scale — enough to influence distribution and trade economics, but not so consolidated as to prevent disruption. Against that backdrop, companies are pursuing distinct, often overlapping strategies:
-
The Procter & Gamble Company (Cincinnati, OH) leverages brand equity and R&D scale to defend premium household tiers, pushing concentrated formats and cross‑category bundling to improve basket economics.
-
The Clorox Company (Oakland, CA) and Reckitt Benckiser (Slough, UK) prioritize disinfectant credentials and institutional channels, translating efficacy claims into procurement advantages in health‑sensitive segments.
-
Henkel and Unilever use their global supply‑chain footprints to optimize cost across price tiers while accelerating reformulation toward milder chemistries and sustainability claims.
-
S.C. Johnson, 3M, and Church & Dwight play hybrid roles — defending core consumer channels while selectively investing in adjacent institutional or technology‑led offerings.
-
Ecolab, Diversey, Zep, Spartan, Betco and other professional‑market specialists focus on performance, dilution economics, and service bundles, keeping margins resilient even when raw‑material costs rise.
Strategic implication: the incumbents’ playbooks are increasingly bifurcated — brand‑led premiumization vs. performance/service‑led pricing in commercial channels — creating differentiated routes to growth. Successful challengers will combine formulation credibility, channel specificity, and nimble procurement to carve defensible niches.
Segment dynamics and input‑cost realities
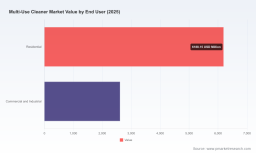
Form factor, end‑user mix, and channel choice remain the primary levers shaping unit economics. While the report offers detailed split analysis, the strategic takeaway for 2026 is clear: product formulations with high surfactant intensity are most exposed to feedstock volatility; concentrated and refillable formats provide the most immediate margin and sustainability upside; institutional customers increasingly reward demonstrable environmental and health credentials.
Real‑world price data illustrates the point: LAB traded at approximately USD 1,826/MT in the U.S. during Q1 2025, USD 1,678/MT FOB in China in early 2026, and reached near USD 2,806/MT FOB in India in March 2026 (Industry Market Data, Mar 2026). Such regional divergence creates both risk and arbitrage opportunities: companies with flexible global sourcing, tolling arrangements, or backward integration can convert feedstock volatility into relative advantage. PW Consulting’s raw‑material stress tests quantify how these inputs affect EBITDA under each scenario.
Regulation, sustainability and procurement — moving from checkbox to revenue driver
Certification programs such as the U.S. EPA Safer Choice are shifting from marketing badges to procurement thresholds in many institutional and retail procurement processes. For manufacturers, the operational consequences are multi‑dimensional: reformulation timelines, validation investment, and supply‑chain traceability requirements all need to be budgeted into 2026 product roadmaps. The report provides a compliance calendar, cost‑impact estimates, and a prioritized list of SKUs for certification that maximizes near‑term tender success.
Actionable strategic recommendations for 2026
-
Re‑run 2026 P&L under a +30% surfactant price shock and prioritize SKUs by margin fragility; implement targeted price escalators where contractually feasible.
-
Accelerate certification for high‑velocity institutional SKUs; win rates in tenders show material uplift where certification is present.
-
Pursue concentrated and refill formats in selected channels to reduce packaging cost and logistics footprint while capturing premium sustainability positioning.
-
Implement dynamic sourcing: blend regional LAB suppliers, consider tolling in low‑cost hubs, and lock strategic volumes through flex contracts with key suppliers.
-
Screen M&A targets using PW’s two‑stage filter: strategic fit (channel/formulation) and integration debt (systems and distribution). Prioritize targets with service capability in the professional segment or unique formulation IP.
-
Build a channel playbook for e‑commerce and subscription models to improve customer lifetime value and smooth demand seasonality.
-
Deploy a verification program for sustainability claims to avoid greenwashing risk and to protect brand value in litigious markets.
How PW Consulting supports your 2026 decision cycle
Our Multi‑Use Cleaner Market report is designed as an operational decision kit, not a static PDF. Deliverables include the interactive forecast model, sensitivity dashboards (including a LAB price‑to‑EBITDA mapper), competitor heatmaps and M&A target dossiers, plus a 2‑day executive workshop to convert findings into a 90‑day action plan. We intentionally reserve the granular segmentation tables, regional and SKU‑level estimates, and the full target list for the report itself — this ensures strategic confidentiality and gives subscribers a clear reason to access the primary dataset.
Next steps
For leadership teams preparing 2026 plans: start with a focused diagnostic — map your exposure to surfactant feedstocks, prioritize certification needs for your fastest‑growing channels, and validate your SKU portfolio against our margin‑fragility matrix. PW Consulting can deploy a rapid 6‑week engagement to integrate our model with your ERP and S&OP processes and to produce a board‑ready growth and cost‑mitigation roadmap.
To access the full dataset, segmentation breakdowns, and the candidate M&A list, visit the PW Consulting report landing page or contact our Multi‑Use Cleaner practice lead for a confidential briefing. The market’s trajectory over 2026 will reward speed, clarity of scenario planning, and disciplined execution — the components PW Consulting’s report is built to deliver.
For detailed analysis of this topic, please visit the official page: Multi Use Cleaner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com