

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cochloroether Rubber Eco Market Poised for 4.51% CAGR Growth — New Report Reveals Opportunity Hotspots

PW Consulting Releases Strategic Briefing: Cochloroether Rubber (ECO) Market — Actionable Intelligence for 2026 Decision-Makers
PW Consulting today publishes an executive-level briefing accompanying its forthcoming Cochloroether Rubber (commonly referenced as “ECO” or epichlorohydrin rubber) market research report. Built for executives, procurement leaders, product chiefs and M&A teams, this briefing synthesizes the market’s macro trajectory, competitive dynamics and the practical playbooks our full report delivers — while deliberately preserving detailed subsegment metrics to guide readers to the full report for proprietary line-item intelligence.
Cochloroether Rubber Eco Market
Headline market view: steady growth, concentrated supplier power
Our consolidated model shows the global Cochloroether Rubber market expanding from the mid‑hundreds of millions (USD Million) in 2020 to an estimated base-year size in 2025, with continued growth through the 2026–2032 forecast window. PW Consulting’s demand projection uses a compound annual growth rate (CAGR) of 4.51% over the forecast horizon. Under our central scenario, market value advances meaningfully by the early 2030s, reflecting resilient demand from automotive systems, industrial sealing, and selected high‑value technical applications.
Cochloroether Rubber Eco Market
Two structural characteristics define the landscape for 2026 planning:
Cochloroether Rubber Eco Market
- Supply concentration: the top three suppliers control a clear majority of market volume, with the top five representing an even larger share — a structure that magnifies the strategic importance of supplier selection, contractual protections and contingency capacity.
- Feedstock dynamics: epichlorohydrin — the principal upstream feedstock — is experiencing capacity additions and technology transitions (notably glycerol–derived and other low‑carbon routes), which create both opportunity and price volatility as new capacity comes online.
Why this matters for 2026 decisions
2026 will be a pivotal year for commercial and capital decisions because three concurrent forces are shaping risk and return:
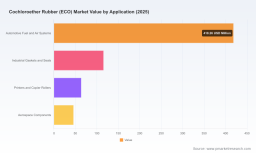
- Demand mix is evolving. While traditional automotive fuel-system applications remain a major base market today, electrification trajectories, biofuel adoption and regulatory emissions tests are altering component specifications and lifecycle requirements.
- Upstream supply is shifting. Recent industry developments show meaningful additions to global epichlorohydrin capacity and a visible move toward bio‑based production routes. These shifts affect cost curves, lead times and the pricing leverage of integrated producers.
- Regulatory and safety standards are tightening. OEMs and tier suppliers are increasingly prioritizing lead-free and non‑ETU curing systems, and piece‑part traceability is becoming table stakes in global automotive and aerospace supply chains.
Competitive landscape: profiles that define strategies
The market’s competitive topology is dominated by established producers that combine integrated upstream access, multi‑grade product portfolios and geographic manufacturing footprints. Our report’s competitive chapter provides detailed supplier scorecards; below is a high‑level synthesis of the strategic positioning of five industry leaders:
- Osaka Soda Co., Ltd. — A vertically integrated supplier with a long heritage in epichlorohydrin‑based elastomers. Integration from monomer to finished polymer delivers tactical advantages in margin capture and product consistency. Recently announced price actions by the firm underscore how integrated producers can transmit upstream cost pressure to the market, setting a pricing reference that others follow.
- Mitsui Plastics, Inc. — A legacy producer offering high‑purity ECO lines and customizable grades targeted at automotive sealing and niche industrial uses. Mitsui’s heritage manufacturing practices and product breadth make it a de‑risked partner for OEMs seeking tight specification control.
- Zeon Corporation — A global player with regionalized production emphasis. Its product mix and targeted grade development (including US production capacity for certain elastomer lines) position Zeon as a strategic supplier for customers requiring local content and proven low‑temperature performance.
- BRP Manufacturing — A US‑based compounder focused on application‑ready ECO compounds that meet key ASTM and OEM standards. BRP exemplifies the US localized supply alternative for customers seeking short lead times and application engineering support.
- RADO Gummi GmbH — A European technical compounder emphasizing regulatory‑friendly curing systems (lead‑free / ETU‑free) and formulation choices that target low permeability and extended storage life — attributes attractive to safety‑sensitive automotive and industrial programs.
Collectively, these suppliers illustrate the range of competitive advantages in the market: upstream integration, regional production capacity, formulation engineering and compliance‑forward chemistry. PW Consulting’s full supplier matrix ranks these and other participants on technical fit, capacity reliability, pricing transparency and M&A attractiveness.
Raw‑material dynamics — the epichlorohydrin story
Epichlorohydrin remains the dominant upstream risk factor for ECO economics. Recent industry metrics show global production capacity reaching notable scale and several rounds of capacity additions in recent years — including capacity brought online with a focus on glycerol‑derived, lower‑carbon manufacturing routes. These developments create a nuanced picture:
- Near‑term easing of unit costs is possible as new capacity dilutes tightness, but timing and ramp rates vary by technology and region.
- Bio‑based production pathways improve the decarbonization profile of downstream ECO grades and can become a differentiator in procurement criteria driven by OEM sustainability mandates.
- Price transmissions from feedstock producers to finished‑good suppliers remain asymmetric; integrated producers are better positioned to manage volatility, while independent compounders must adopt hedging or long‑term contracting strategies.
What the PW Consulting report contains — practical, transaction‑ready modules
Adhering to our “action over adjectives” research philosophy, the full report delivers executable tools for 2026 planning across commercial, technical and M&A activities. Highlights include:
- Proprietary demand model and scenario stress tests: demand-by-application trajectories under multiple EV/ICE penetration and fuel‑policy scenarios (interactive datasheets included).
- Price and margin curve analysis: finished‑good and feedstock cost stacks with sensitivity matrices for common contract structures.
- Supplier scorecards and negotiation playbook: technical fit‑for‑use ratings, capacity lead‑time risk, and a phased negotiation checklist for locking multi‑year supply while retaining upside options.
- Product substitution and formulation guidance: engineering tradeoffs between homopolymer, copolymer and terpolymer grades, including low‑temperature and ozone resistance strategies.
- Regulatory and compliance checklist: ETU‑free / lead‑free pathways, documentation templates and audit protocols aligned to automotive and aerospace OEM expectations.
- M&A and inorganic growth playbooks: target screening criteria, accretion/dilution scenarios, and integration step‑plans for bolt‑on capacity or technology acquisition.
- Decarbonization roadmap: practical steps to evaluate bio‑based epichlorohydrin and supplier partnerships that can credibly reduce Scope 3 exposure.
Strategic recommendations for 2026 — what leaders should do now
PW Consulting’s advisory stance for management teams and boards facing 2026 choices centers on three priorities:
- Secure optionality, not just supply: Move from transactional spot buys to layered contracting (short‑term flex + a limited portfolio of firmed capacity) to balance cost, service and business continuity. Prioritize suppliers that can demonstrate integrated feedstock positions or credible hedging mechanisms.
- Embed technical differentiation into procurement KPIs: Procurement success metrics should incorporate formulation innovation, low‑temperature performance and regulatory readiness. Where feasible, co‑develop application‑specific compounds with suppliers to capture performance premiums and defend against substitution risk.
- Pursue targeted inorganic motions and partnerships: Given market concentration, selective M&A can be accretive — either to secure regional capacity or to acquire formulation IP (e.g., ETU‑free cures, bio‑feedstock integration). Our M&A playbook shows where value is created and where integration risk is highest.
Risks to monitor (and how to hedge them)
- Upstream feedstock timing risk: monitor capacity ramp schedules and secured offtake agreements; use tranche‑based contracts with volume flex rather than full fixed‑volume exposure.
- Regulatory tightening: prioritize suppliers with proven ETU‑free and lead‑free solutions and insist on third‑party certification clauses in long‑form supply agreements.
- Demand pivots from electrification: deploy rapid‑response scenario planning for OEM platform shifts, and maintain cross‑application capability to redeploy capacity to industrial or secondary markets.
Why the full report is essential
This briefing outlines the structural drivers and tactical implications for Cochloroether Rubber through 2026 and beyond, but the complete PW Consulting report contains the proprietary, line‑level intelligence that materially alters deal outcomes and procurement economics — including our detailed supplier rankings, price sensitivity tables, M&A target scoring and interactive demand models. We intentionally withhold subsegment breakouts in this public summary to protect the proprietary value of the underlying analysis and to ensure decision‑makers rely on validated, auditable numbers when crafting contracts, investments and product roadmaps.
For senior teams planning FY‑2026 budgets, contract renegotiations or strategic investments, the report converts ambiguity into executable options and quantified downside exposures. PW Consulting’s analysts remain available for bespoke briefings, model walkthroughs and scenario workshops tailored to board and executive needs.
Next steps
- Schedule a tailored briefing with PW Consulting to review the supplier scorecards and our demand model under your specific regional and application mix.
- Authorize an accelerated due diligence package if you are evaluating capacity buyouts, minority investments or strategic supply partnerships in 2026.
- Deploy the report’s procurement checklist and regulatory annex to current sourcing rounds to capture early‑mover advantage on capacity and sustainable raw‑material sourcing.
Access to the full Cochloroether Rubber Eco Market: 2026–2032 report, including interactive workbooks and supplier benchmarking tools, is available via PW Consulting’s report portal. Stakeholders who require validated segment detail, proprietary pricing curves, or the M&A target shortlist should contact PW Consulting to obtain the full dataset and secure a confidential briefing.
— PW Consulting, Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: Cochloroether Rubber Eco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com