

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Robot Joint Actuator Market to Surge at 18.52% CAGR — From USD 20,185.55 Million in 2025 to USD 66,310.66 Million by 2032

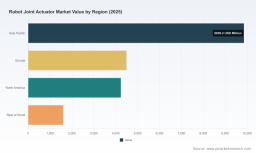
Robot Joint Actuator Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s new Robot Joint Actuator Market report (base year 2025; forecast 2026–2032) delivers a focused, actionable intelligence package to guide supplier selection, product roadmaps, and capital-allocation decisions for the coming strategic planning cycle. The global market has accelerated sharply in the first half of the decade — expanding from under USD 9 billion in 2020 to roughly USD 20 billion in 2025 — and our model projects continued rapid growth at a compound annual growth rate of 18.52% through 2032. This trajectory, driven by a shift to integrated, high-torque, zero-backlash joint modules and fast-rising demand from humanoid, collaborative and service robotics, creates discrete windows of opportunity and risk that 2026 executive teams cannot afford to ignore.
Robot Joint Actuator Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a bifurcation year — standards updates, new supply agreements, and product introductions are converting technical demonstrations into production programs. Our report maps the timing and likely commercial impact of these inflection points so you can prioritize commercial pilots and capacity commitments.
Robot Joint Actuator Market -
Risk-adjusted growth: At an 18.52% CAGR, market expansion is large but heterogeneous; the report quantifies demand momentum, identifies margin pressure scenarios, and shows where strategic vertical integration or outsourcing delivers immediate value.
Robot Joint Actuator Market -
Practical playbooks: Beyond topline forecasts, the study delivers procurement scorecards, supplier readiness matrices, and a manufacturing-capex framework that shorten the time from insight to contract negotiation.
Market dynamics shaping 2026 decisions
-
Integrated actuator adoption: The industry is moving from component procurement to integrated actuator modules (motor + gearbox + sensors + controls + thermal management). This unbundling-to-rebundling shift concentrates technical risk into fewer suppliers but simplifies systems integration for OEMs — a key consideration for product managers deciding whether to insource or partner.
-
Cost and design pressure in humanoids: Demonstrations at major shows indicate actuators are now a dominant line-item in humanoid production economics, driving demand for ultra-high torque density, low-backlash solutions. This alters R&D priorities (mechanical power density, sensing redundancy, thermal solutions) and increases the strategic value of early access to prototype actuators.
-
Standards and compliance: Recent ISO revisions and the updated ANSI/A3 standard introduce new guidance covering collaborative operation, cybersecurity, and classification that directly affect actuator functional safety and software interfaces. Compliance timelines are embedded in our regulatory-ready action plans.
-
Raw-material and durability constraints: Key gearbox components continue to rely on high-carbon steel alloys for long fatigue life in flexspline elements. The report’s supply-risk module quantifies exposure by manufacturing topology and recommends hedging and alternative-material development paths.
-
Concentration and supplier bargaining power: Market concentration metrics show a moderately consolidated supplier base that favors established precision-gear and integrated-actuator OEMs; our competitor economic profiles indicate where pricing leverage will persist and where challengers can disrupt with performance or cost innovations.
Competitive landscape — what to watch in 2026
Our vendor mapping synthesizes product, IP, channel and manufacturing capability across established precision-gearing companies, modular-actuator specialists, and rapid-innovation challengers. Selected strategic reads:
-
Harmonic Drive brands (Harmonic Drive LLC; Harmonic Drive Systems Inc.) — market leaders in zero-backlash strain wave gearing and integrated rotary actuators. Their incumbency in precision gearbox IP and established adoption across industrial robotics gives them a defensive edge in high-precision use cases.
-
Maxon Group, Kollmorgen, Moog, ABB — firms combining motor, gearbox, encoder and control stacks with strong systems engineering and global aftermarket networks. Their value lies in turnkey, certified modules and services for volume OEMs.
-
China-based integrators (CubeMars, ZeroErr, RealMan Robotics, Hangzhou RoboCT, Arcsec Drive, Foxtech) — aggressive on torque density, system integration and price-performance. Several firms have moved from prototyping to trade-show production samples, narrowing the gap with incumbents.
-
Specialist modular providers (HEBI Robotics, iNetic Motion, ROBOTIS) — emphasize modularity, series-elastic design or education/service segments; they are attractive acquisition or partnership targets for companies seeking product line breadth or quick market entry.
Recent events validate these trends: demonstrations of fully integrated modules at CES 2026, new product introductions claiming IP67-rated joint actuators, and supply agreements between large robotics OEMs and actuator suppliers have accelerated the conversion of demand signal into firm purchase pipelines. For example, high-profile supplier agreements and product launches in early 2026 have already started to re-shape sourcing calendars and capacity planning across multiple OEMs.
Practical strategic plays — recommended actions for 2026
-
Secure test-and-evaluate slots with second-tier integrators now. The report’s procurement playbook shows how to structure short-term evaluation purchase orders that preserve negotiation leverage while accelerating validation cycles.
-
Adopt a two-track sourcing strategy: qualify a “strategic partner” for integrated modules and a “cost feeder” for commodity drive components. Our supplier-scoring matrix ranks candidates by technical readiness, capacity scalability and compliance posture.
-
Invest selectively in thermal and sensor integration. As torque density rises, thermal management and dual-encoder architectures become differentiators for reliability and safety certification — our technology roadmap prioritizes these investments by ROI horizon.
-
Pursue targeted M&A or JV to secure capacity and IP. The report surfaces categories of inorganic targets (modular actuator specialists, gearbox specialists, sensor/control integrators) and lays out valuation heuristics and integration risk factors.
-
Execute standards-aligned productization. Use the included regulatory checklist to align product testing, cybersecurity architecture, and safety case documentation with the latest ISO/ANSI revisions ahead of anticipated certification audits.
What the report contains (practical, executable modules)
-
Topline market model (2020–2032) with scenario forecasts and sensitivity analyses tied to adoption curves, robotic unit volumes, and typical BOM mixes.
-
Supplier ecosystem map and readiness scoring (manufacturing footprint, IP, certification status, capacity risk); includes a three-tier short-list for immediate sourcing and a watch-list for strategic partnerships.
-
Technology deep dives — harmonic vs. cycloidal vs. planetary strategies; series-elastic vs. rigid actuation trade-offs; integration of controllers and encoders; thermal management approaches and design benchmarks.
-
Cost and margin models — component-level cost drivers, raw-material exposure, and commercial negotiation levers tailored to actuator BOMs.
-
Regulatory impact and compliance playbooks tied to ISO 10218-1/2 (2025 revisions) and ANSI/A3 R15.06-2025; certification timelines and test-plan templates are provided.
-
M&A and partnership playbooks — target archetypes, valuation metrics, integration checkpoints, and a due-diligence checklist specific to actuator IP and supply continuity.
-
Go-to-market and aftersales strategies — channel options, aftermarket service planning, and retrofit upgrade pathways to monetize installed bases.
How executives should use these insights in 2026
-
Chief Procurement Officers — compress supplier qualification cycles using the report’s scorecards; lock conditional capacity with option contracts timed to suppliers’ ramp schedules.
-
CTOs and Product Heads — prioritize actuator capabilities that materially reduce system integration cost and time-to-certification; allocate R&D to high-leverage integration features (dual-encoder architectures, thermal paths, sealed housings).
-
Corporate Development — deploy the M&A playbook to identify tuck-in targets that accelerate time-to-market for integrated actuators or consolidate supply risk.
-
Operations and Quality — use the regulatory checklist to pre-certify modules and shorten product launch cycles while reducing rework from evolving safety and cybersecurity requirements.
PW Consulting’s Robot Joint Actuator Market report gives you the contextual analysis, tactical tools, and quantified scenarios needed to make defensible commercial and technical decisions in 2026. The executive brief above highlights the strategic takeaways; the full report contains the underlying models, supplier scorecards, and segment-level forecasts that operational teams will use to execute. To access the complete dataset, segmentation breakdowns, supplier scoring worksheets and downloadable models, visit PW Consulting’s report page or contact our advisory team to schedule a tailored briefing.
For detailed analysis of this topic, please visit the official page: Robot Joint Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com