

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: DDR RAM Market Poised to Reach USD 264.72 Billion by 2032, New Research Reveals

PW Consulting: Ddr Ram Market Research — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s Ddr Ram Market Research provides a focused, decision‑grade view of the global DDR memory market as firms plan capital, procurement, and product roadmaps for 2026. The market continues to expand from a 2025 base year of USD 118.4 Billion, with our consolidated forecast projecting growth to roughly USD 265 Billion by 2032 at a compound annual growth rate (CAGR) of 12.18% (forecast period 2026–2032). That trajectory, however, sits atop pronounced near‑term volatility and structural shifts in supply allocation, standards, and geopolitics that will directly affect enterprise cost, availability, and architecture choices in 2026.
Ddr Ram Market Research
Why this preview matters for 2026 planning
Enterprises committing inventory purchases, system designs, or supplier partnerships in 2026 face a market driven by three simultaneous forces: accelerated demand from AI and cloud workloads, constrained wafer allocation as manufacturers prioritize high‑margin HBM and advanced nodes, and evolving standards that change product roadmaps. PW Consulting’s report translates these forces into pragmatic, executable guidance: procurement playbooks, scenario price curves, supplier risk heat maps, and architecture migration blueprints. This article distills the strategic takeaways while withholding the granular segment tables and pricing models — full detail and downloadable financial models are available in the complete report.
Ddr Ram Market Research
Market snapshot and recent trajectory
-
Base year: 2025 (USD 118.4 Billion).
Ddr Ram Market Research -
Forecast window: 2026–2032. Our model estimates market expansion to approximately USD 264.72 Billion by 2032 at a CAGR of 12.18% across the forecast period.
-
Historical context: the market displayed pronounced year‑to‑year swings in 2020–2025, reflecting demand shocks (cloud and AI investment cycles), inventory corrections, and supplier capacity reallocation.
-
Concentration: the DDR market remains highly concentrated; the top three suppliers account for the overwhelming majority of industry output while the top five approach near‑total market share — a dynamic that amplifies the impact of strategic capacity decisions by leading manufacturers.
Primary dynamics shaping 2026
-
Supply reallocation to HBM and advanced products: Major manufacturers have shifted wafer capacity toward HBM to serve AI accelerators and high‑margin segments. That reallocation constrains standard DDR supply and is a root cause of recent spot tightness.
-
Production adjustments and lifecycle management: Leading producers extended certain legacy DDR4 production lines into late 2026 to ease tightness, while simultaneously prioritizing DDR5 and HBM. That selective extension creates intermittent windows of availability and pricing divergence between DDR4 and DDR5.
-
Standards acceleration: JEDEC updates in 2025 introduced DDR5 improvements (including increased reliability/security and SPD enhancements) and released a new LPDDR6 standard. These changes accelerate vendor roadmaps and introduce performance tiers buyers must consider when specifying future platforms.
-
Price shock dynamics: Contract and spot DDR5 pricing experienced extraordinary hikes in late 2025 and carried momentum into early 2026; buyers should expect elevated volatility in the first half of 2026 as demand outpaces redirected supply.
-
Geopolitics and export controls: Government actions on critical mineral imports and continued export controls on advanced semiconductor equipment create asymmetric risks to capacity expansion and component flows. Firms with concentrated supplier exposure or single‑source regions must factor in regulatory risk as a first‑order procurement variable.
What the PW Consulting report delivers (practical, actionable content)
-
Scenario‑based demand/supply models: multi‑scenario forecasts (baseline, tight‑supply, HBM‑priority) that map price sensitivity to capacity decisions.
-
Proprietary pricing curves and volatility matrices: daily/quarterly spot and contract proxies calibrated to 2020–2025 history and 2026 market signals (available as downloadable Excel models).
-
Supplier scorecards and risk maps: strategic profiles of global DRAM suppliers, technology roadmaps, capacity allocation plans, and counterparty risk assessments.
-
Procurement playbooks: negotiation frameworks, contract clause templates (escalation, relief, force majeure), hedging approaches, and inventory targets tied to scenario thresholds.
-
Architecture migration blueprints: decision trees for DDR4 → DDR5 upgrades, LPDDR and HBM adoption pathways for mobile and AI workloads, and cost/benefit timelines for platform architects.
-
M&A and sourcing opportunities: identification of niche suppliers and consolidation targets, plus recommended diligence checklists for strategic acquisitions or supply agreements.
-
Regulatory and supply‑chain contingency register: practical mitigation steps for export control shocks, critical material restrictions, and cross‑border latency in procurement.
Competitive landscape — how leading vendors are positioning
Market concentration remains a defining structural reality: a few large producers drive global output and their capacity decisions ripple across price and availability. PW Consulting’s assessment of principal vendors identifies distinct strategic postures:
-
Samsung Electronics (Suwon, South Korea) — maintains leadership in scale and is actively balancing DDR5 ramp with HBM expansion. Strategic implications: Samsung’s allocation choices will remain a primary driver of short‑term availability and price movements.
-
SK hynix (Icheon, South Korea) — focused on high‑performance DDR5 and HBM, selectively extending legacy DDR4 lines to stabilize markets through 2026. Strategic implications: suppliers and buyers should monitor SK hynix’s HBM commitments as a signal for DDR supply tightness.
-
Micron Technology (Boise, USA) — prioritizing higher‑margin enterprise and data‑center DDR5 offerings and higher‑density SKUs. Strategic implications: Micron’s product and pricing strategy will strongly influence enterprise procurement for data‑center migration and cost modeling.
-
CXMT (ChangXin, China) — advancing DDR5 at newer nodes and emerging as a regional alternative supplier. Strategic implications: CXMT’s growth provides diversification potential but comes with latency and regulatory considerations for multinational buyers.
-
Nanya Technology (Taiwan) — plays a complementary role with focused DDR output, benefitting from legacy consolidation. Strategic implications: Nanya is a candidate for niche sourcing and tactical purchases where availability is constrained.
-
Winbond Electronics (Taiwan) — concentrates on specialty and embedded DRAM segments; valuable for embedded and industrial designs requiring close supplier collaboration.
Practical recommendations for enterprise leaders in 2026
-
Lock tactical coverage now, keep strategic flexibility: Secure multi‑quarter commitments for critical SKUs to avoid first‑half 2026 price spikes, while preserving contract flexibility for architecture pivots as JEDEC standards evolve.
-
Adopt a dual‑track architecture strategy: Accelerate proof‑of‑concepts for DDR5 adoption on forward‑looking product lines, but retain DDR4 fallbacks where validated — this reduces product‑launch risk under tight supply conditions.
-
Diversify supplier mix with risk controls: Introduce alternative suppliers for non‑core elements, but use vendor scorecards and regulatory compliance checks to manage geopolitical and export‑control exposure.
-
Price and inventory engineering: Negotiate indexed pricing mechanisms and include inventory release clauses tied to verified production events; consider financial hedges for prolonged price volatility.
-
Invest in visibility and scenario exercises: Build cross‑functional war‑rooms (procurement, engineering, legal) trained on the report’s scenarios to accelerate decision cycles during sudden supply shocks.
-
Monitor standards adoption: Integrate JEDEC’s DDR5 and LPDDR6 implications into product roadmaps now — early compliance reduces downstream rework and supplier swaps.
Timing and near‑term actions (what to do in Q1–Q3 2026)
-
Q1 2026: finalise multi‑quarter procurement blocks for critical memory lines, activate contingency suppliers where lead times exceed acceptable risk thresholds, and deploy price‑index clauses in new contracts.
-
Q2 2026: complete DDR5 validation across priority platforms; begin staggered migration where performance provides clear TCO improvements; reassess inventory cover as spot markets evolve.
-
Q3 2026: review capex commitments and strategic partnership options for 2027–2028; revisit M&A or alliance opportunities identified in the report if supply tightness persists.
Closing — the strategic value of the full report
This article is a strategic preview designed to surface the decisive levers and immediate actions enterprises must consider when planning for 2026. PW Consulting’s full Ddr Ram Market Research contains the granular segmentation, unit‑level pricing models, vendor scorecards, downloadable financial scenarios, and the proprietary methodology that underpin the recommendations summarized here. To execute with confidence in 2026 — securing supply at competitive prices while aligning product architecture to evolving standards — the full dataset and playbooks in our report are essential.
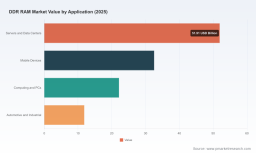
Note: this preview intentionally omits the detailed regional, type, and application splits, as well as unit price schedules and vendor share tables, to preserve the integrity of our subscription offering. Access the complete report and the accompanying Excel scenario models on the PW Consulting report page to obtain the full intelligence required for operational execution.
For detailed analysis of this topic, please visit the official page: Ddr Ram Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com