

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Sodium Nitrate Market Tops USD 520 Million in 2025 as Asia Pacific Leads Global Demand

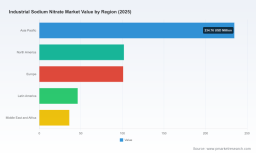
Industrial Sodium Nitrate Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a strategic preview of its forthcoming Industrial Sodium Nitrate Market study (base year 2025, forecast 2026–2032). The market reached an estimated USD 520.0 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.02% over the forecast horizon, underpinned by resilient demand from traditional industrial applications and emerging thermal energy storage use cases. This preview outlines the report’s practical value for executive teams and investors planning decisions in 2026, while deliberately withholding detailed segment-level figures to encourage access to the full report for transaction-grade intelligence.
Industrial Sodium Nitrate Market
Why this report matters for 2026 decision-making
-
Near-term planning: The market’s mid-single-digit CAGR masks uneven short-term dynamics across feedstock pricing, regional demand cycles and regulatory exposure. Procurement, operations and commercial leaders must bake these micro-variations into 2026 budgets and contracts; our full study translates macro forecasts into actionable planning buffers and scenario triggers.
Industrial Sodium Nitrate Market -
Capital allocation: Producers evaluating capacity expansions, brownfield upgrades or greenfield projects require rigorous total-cost-of-ownership analyses that incorporate upstream feedstock volatility (notably nitric acid and soda ash), logistics risk and attainable operating rates. The report includes a financial-model template and sensitivity matrices to accelerate board-level decisions.
Industrial Sodium Nitrate Market -
M&A and JV diligence: With market concentration metrics indicating a moderately consolidated supply base (CR3 and CR5 at 42.5% and 58.2%, respectively), strategic buyers must assess consolidation upside versus execution risk. We provide a playbook for target screening, integration value levers, and post-deal synergies—critical for deals contemplated in 2026.
-
Buy-side optimization: Industrial end-users can leverage our pricing and sourcing intelligence to structure multi-year contracts, optimize inventory strategies, and identify alternative supply routes—material to margin protection amid commodity swings.
Market snapshot (strategic summary)
Industrial sodium nitrate remains a modestly sized specialty salts market, with steady compound growth projected through 2032. Total market value expanded to USD 520.0 million in 2025 and the PW Consulting forecast anticipates continued growth toward the end of the decade, reflecting both steady industrial demand and targeted adoption in thermal energy storage systems. Pricing exhibits regional dispersion and short-term volatility driven by feedstock costs and demand cycles; our report dissects these price drivers and their sensitivity to macroeconomic conditions.
What the PW Consulting report delivers (practical, transaction-ready content)
-
Top-down and bottom-up market sizing with scenario-based forecasts (base year 2025; forecast 2026–2032).
-
Detailed pricing models and regional price trackers with vendor-adjustable inputs for nitric acid and soda ash cost movements.
-
Supply-chain and logistics risk maps highlighting pinch points in production, ports and inland distribution.
-
Regulatory impact analysis covering environmental limits on nitrate discharges, compliance capex requirements, and likely policy trajectories through 2030.
-
Commercial intelligence packages: supplier scorecards, product-grade comparators, terms benchmarking, and negotiation playbooks.
-
Investment and M&A playbooks including valuation multiples, synergy frameworks and integration checklists tailored to sodium nitrate value chains.
-
Competitive landscape with vendor positioning, strategic intent assessments, and stress-tested scenarios evaluating capacity moves and price wars.
Competitive landscape — synthesis and implications
The supply base mixes legacy resource-based producers, integrated chemical majors and regionally focused manufacturers. Global players with natural deposit access continue to exert pricing and quality leadership, while diversified chemical groups and regional manufacturers supply flexibility and proximity to end markets.
-
SQM S.A. (Chile) — As a long-standing producer leveraging natural caliche deposits, SQM combines scale with high-purity product capability. Recent production updates and declared expansion efforts in 2025 signal a continued focus on lifting capacity while managing environmental footprints. For corporates, SQM’s moves represent both a source of competitively priced high-purity feedstock and a barometer for industry operating best practices in resource stewardship.
-
BASF SE (Germany) — The integrated chemical major supplies sodium nitrate as part of a broader industrial portfolio. BASF’s strength lies in global commercial channels and capability to bundle offerings across adjacent chemistries—an attractive route for customers seeking supplier consolidation and technical support.
-
Deepak Nitrite Limited (India) — The company’s recent capacity expansion (announced July 2025) with a new facility in Oman underscores a strategic push to diversify production footprint and serve export markets. This highlights an ongoing trend: regional players scaling through overseas capacity to mitigate domestic feedstock constraints and serve global demand corridors.
-
Regional Chinese producers and groups — Several China-based manufacturers continue to supply industrial grades into domestic and export markets. Their competitive advantages include manufacturing scale, cost position and proximity to downstream industrial clusters. For global buyers, they offer tactical sourcing options but require due diligence on quality, logistics and regulatory compliance.
-
Others — European and other global suppliers provide specialty grades, tailored logistics and regulatory-compliant supply chains, serving customers with higher technical or compliance requirements.
Taken together, these company-level dynamics drive a market where strategic partnerships, geographic diversification and grade differentiation are central to long-term competitiveness. The CR3/CR5 concentration figures (42.5% and 58.2%) indicate meaningful but not prohibitive market power among top suppliers—creating opportunities for mid-sized producers to gain share through focused investments.
Market dynamics and near-term risk drivers
-
Feedstock cost linkage: Production economics are tightly coupled to nitric acid and soda ash prices. Historical movements show that soda ash softness in late 2024 depressed spot prices in parts of Asia, while firm upstream costs supported price firmness in Europe and pockets of North America.
-
Regional price movements: Regional price divergences have been material in early 2026—European spot levels exhibited modest upward adjustments in March 2026, while North American levels reflected a meaningful softening from late-2025. These divergent regional paths create arbitrage opportunities but also complicate contract negotiations and inventory optimization.
-
Regulatory pressure: Environmental regulations governing nitrogen compounds are tightening in several jurisdictions, raising compliance capex and operational complexity. Producers face increasing expectations to invest in cleaner processes and effluent control—factors that need to be factored into 2026 capex planning.
-
End-market variability: Traditional end-uses such as glass manufacturing and metal treatment remain demand anchors, but the pace of adoption in newer applications—most notably thermal energy storage for concentrated solar power—will influence long-term structural growth and grade requirements.
Recommended strategic moves for 2026
-
For producers: Prioritize flexible capacity and feedstock hedging. Invest in effluent control and certification to win regulated contracts. Assess selective brownfield expansions in low-cost jurisdictions to capture export demand while controlling capital intensity.
-
For buyers/end-users: Reconfigure procurement to include a blend of contracted volumes and spot exposure, tied to clear feedstock cost pass-through clauses. Evaluate supply continuity clauses and multi-supplier strategies to mitigate regional price shocks.
-
For investors: Target mid-tier producers with clear differentiation (grade purity, logistics, regulatory compliance) and potential to consolidate in fragmented regional markets. Use PW Consulting’s valuation templates and downside scenarios when assessing bids.
-
For traders and distributors: Exploit regional price spreads with disciplined risk limits, and develop value-added services (just-in-time logistics, technical support) to command premiums as manufacturers seek to streamline vendor bases.
How PW Consulting’s analysis is uniquely useful
This report combines granular market mechanics—price-sensitivity models, supplier scorecards and regulatory impact matrices—with executive-ready strategic recommendations and transaction tools. We blend primary interviews with producers and buyers, proprietary pricing datasets and scenario-based financial models so clients can move from insight to action within weeks, not months.
Our approach follows a “preview-to-transact” model: the public summary establishes the strategic picture and immediate imperatives; the full report provides the discrete datasets, segment-level analyses and vendor dashboards required to execute sourcing, investment or M&A strategies with conviction.
Recent developments to watch (selection)
-
Deepak Nitrite Limited announced in July 2025 a new production facility in Oman to expand nitrite/nitrate capacity—an example of capacity diversification aimed at improving access to export markets.
-
SQM S.A. reported production updates in March 2025, noting expansion activity alongside environmental performance initiatives—illustrative of incumbent producers balancing scale with sustainability investments.
-
Regional price signals in early 2026 show Europe experiencing slight upward price pressure in March, while North American spot lines softened significantly from late-2025—trends that create both procurement risk and arbitrage potential.
Next steps
For procurement leads, strategy teams and investors preparing 2026 action plans, PW Consulting’s Industrial Sodium Nitrate Market report is designed to convert market intelligence into executable moves. To access the full dataset, supplier scorecards and transaction playbooks, please visit our report page (link available in the official release) or contact PW Consulting’s industrial chemicals practice for a tailored briefing.
Our full report preserves the depth and granularity required for operational and financial decisions while maintaining the commercial confidentiality necessary for transaction execution. PW Consulting stands ready to support clients with bespoke model customization and due-diligence support as they implement the 2026 strategies outlined above.
For detailed analysis of this topic, please visit the official page: Industrial Sodium Nitrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com