

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Uterotonic Agent Market to Expand at a 6.19% CAGR Through 2032, Led by Oxytocin Demand and Asia-Pacific Growth

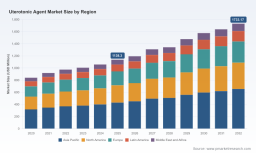
Uterotonic Agent Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s new market study on uterotonic agents delivers a forward-looking, action-oriented intelligence package designed to inform executive decisions across pharma manufacturers, procurement agencies, multilateral donors, and investors ahead of 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report quantifies the market’s current scale and trajectory (base-year market value: USD 1,138.3 Million in 2025; forecast to USD 1,733.17 Million by 2032) and models a compound annual growth rate of 6.19% through the forecast period. This preview highlights the strategic takeaways and operational levers that corporate and public-sector leaders should prioritize — while reserving the detailed country-level and segment tables exclusively for the full report.
Uterotonic Agent Market
Executive summary — why 2026 is an inflection year
-
Maternal health policy momentum and procurement reform are converging with new product-level innovations (notably heat-stable uterotonics) to reshape procurement priorities and supply chains. These shifts create selective growth pockets even as pricing pressure persists in commoditized product lines.
Uterotonic Agent Market -
Market scale and steady mid-single-digit growth (6.19% CAGR) reflect a dual dynamic: durable demand driven by global maternal health programs and periodic volatility tied to cold-chain integrity and tender outcomes.
Uterotonic Agent Market -
Competitive dynamics are moderately consolidated — the largest three firms account for a meaningful share of market value, while a broader base of generic and regional manufacturers play critical roles in supply security and public-sector procurement. The report quantifies concentration metrics, enabling clients to evaluate consolidation risks and partnership strategies.
Key market dynamics
-
Regulatory and guidance drivers. WHO recommendations continue to define clinical standard of care: oxytocin remains the first-line uterotonic for prevention of postpartum hemorrhage where quality and cold chain can be assured, while heat-stable carbetocin and misoprostol serve as strategic alternatives in settings with compromised cold chain or limited capacity.
-
Quality and cold-chain risk. Standard oxytocin formulations require refrigerated storage, exposing global supply chains — particularly in tropical, low-resource settings — to potency loss and product failures. Procurement strategies that emphasize lowest unit cost without quality safeguards have historically produced substandard outcomes; our supply-risk modelling shows how this materially impacts effective coverage.
-
Product innovation and access. Heat-stable carbetocin, now recognized on essential medicines lists and subject to expanded licensing, is changing the economics of maternal health programs in environments where refrigeration is unreliable. Strategic licensing and technology-transfer arrangements are accelerating availability in public-sector channels.
-
Procurement and pricing pressure. Public tenders, donor procurement lists, and price-competitive generics keep downward pressure on unit prices, while value-based procurement (quality + reliability) is an emergent procurement theme in middle-income markets. Manufacturers and distributors must balance margin compression against scale-backed efficiency gains.
-
Supply base diversity. A layered supplier ecosystem — comprising global innovators, multinational generics, WHO-prequalified producers, and local manufacturers in Asia and Africa — underpins resilience. The report maps supplier capabilities, prequalification status, and strategic footprints to help buyers de-risk sourcing.
What the PW Consulting report contains (practical, actionable deliverables)
-
Top-down and bottom-up market sizing and scenario models: five-year and seven-year forecast options with sensitivity to cold-chain disruption, procurement policy shifts, and product substitution scenarios.
-
Decision-grade commercial playbooks for manufacturers: go-to-market models for branded heat-stable formulations vs. generics, tender-response templates, pricing architecture, and channel segmentation tactics.
-
Regulatory and prequalification roadmap: step-by-step pathways for WHO prequalification, dossier templates, common inspection pitfalls, and time-to-procurement estimates for public-sector entry.
-
Manufacturing and supply-chain optimization blueprints: API sourcing strategies, cold-chain cost models, fill-finish optimization, and small-batch strategies for regional manufacturing to improve lead times and procurement responsiveness.
-
Procurement & contracting recommendations: outcome-based tender frameworks, coverage-risk scoring tools, supplier performance KPIs, and contract clauses that align price incentives with product quality and delivery reliability.
-
M&A, licensing and partnership playbooks: target screening criteria, valuation heuristics for asset purchases and technology transfers, and model term-sheets for licensing heat-stable formulations in public markets.
-
Interactive annexes and data packs: searchable supplier roster (WHO prequalification status included where applicable), product lifecycle trackers, and a suite of downloadable Excel tools for scenario analysis. Note: detailed regional and application-level numeric tables are available only in the full report to authorized subscribers.
Competitive landscape — strategic positioning to watch
-
Innovator leadership and differentiated access: Companies that have invested in heat-stable formulations and strategic licensing (including collaborative agreements with multilateral partners) are positioned to capture higher-quality procurement channels and donor-funded tenders. These firms are increasingly monetizing intellectual property through conditional licensing to expand access while preserving branded market segments.
-
Large multinational producers: Established pharma companies supplying oxytocin and misoprostol retain strong relationships with hospital systems and national procurement agencies. Their strengths include global distribution networks, regulatory experience, and the ability to supply multi-product portfolios into tender bundles.
-
Generics and WHO-prequalified producers: A broad set of manufacturers provides price-sensitive volumes in public-sector tenders. WHO prequalification remains a critical credential; recent prequalification and quality-assured supplier list publications have reshaped buyer shortlists and accelerated supplier selection for many countries.
-
Regional manufacturers and supply security: Local players in Africa and Asia fill critical gaps, reducing lead times and import dependency. These producers are central to national resilience strategies and donor-funded localization programs.
-
Consolidation indicators: Market concentration metrics point to a moderately consolidated market where the top three and top five suppliers exert meaningful influence on pricing and availability. This concentration profile informs competitive response strategies — from alliance formation to vertical integration.
Recent developments that change the calculus for 2026
-
Regulatory and procurement shifts: Recent prequalification of additional oxytocin injectable products and the publication of quality-assured supplier lists have expanded buyer choice but also raised the bar on documentation and quality surveillance.
-
Licensing and access arrangements: Conditional licensing and technology transfer agreements for heat-stable formulations are unlocking new public-sector channels and altering how manufacturers commercialize innovations in low-resource markets.
-
Ongoing policy reinforcement: Continued global endorsement of heat-stable alternatives where cold chain integrity is uncertain, combined with misoprostol’s defined role where oxytocin is unavailable, requires companies to maintain multi-product strategies rather than single-product bets.
Strategic recommendations for executives preparing decisions in 2026
-
Prioritise quality and reliability in bid strategies. Winning tenders increasingly depends on demonstrating supply security and product integrity — not only lowest unit price.
-
Accelerate product differentiation where feasible. Investing in heat-stable formulations, simple packaging innovations, or cold-chain-assurance services can create premium procurement channels and reduce loss rates in the field.
-
Diversify supplier networks and de-risk API sourcing. A layered supplier strategy combining multinational, regional, and local producers mitigates interruption risks and shortens lead times for programmatic deliveries.
-
Pursue WHO prequalification early. For manufacturers targeting public markets, prequalification unlocks donor-funded tenders and national procurement lists; our report provides a practical timeline and resource estimate for the process.
-
Evaluate licensing and partnership models aggressively. Innovator firms can scale access through conditional licensing while preserving premium volumes; generics and regional manufacturers should target technology transfers that enable local production of heat-stable options.
-
Embed quality-surveillance and cold-chain telemetry into commercial offers. Buyers are willing to pay for demonstrable reductions in product degradation risk; manufacturers and distributors that bundle monitoring services can capture differentiated margins.
How PW Consulting supports your 2026 decisions
-
Customized strategic due diligence and acquisition support for corporates and investors evaluating entry or expansion into the uterotonic value chain.
-
Procurement advisory and tender-readiness programs for ministries of health, multilateral donors, and large buyers seeking to implement quality-linked procurement frameworks.
-
Regulatory and prequalification program management, including dossier review, gap remediation plans, and inspection readiness.
-
Scenario modelling workshops that convert our forecast ranges into board-ready financial plans, break-even analyses, and risk-adjusted valuation decks.
PW Consulting’s full Uterotonic Agent Market report contains the granular tables, country-level forecasts, and supplier-by-supplier profiles that operational teams will need to finalize budgets, procurement strategies, and M&A decisions for 2026 and beyond. To access the complete dataset, segmented models, and executable playbooks — including the full annex of WHO prequalification statuses and supplier scorecards — please visit our report page or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Uterotonic Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com