

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Submarine AIP Systems Market to Grow at a 3.8% CAGR Through 2032

PW Consulting Release: Submarine AIP System Market — Strategic Intelligence for 2026 Decision-Makers
Executive summary
As navies and submarine builders navigate a changing security and procurement environment, PW Consulting’s latest Submarine AIP System Market report delivers actionable intelligence timed for strategic planning in 2026. The global AIP systems market has demonstrated steady expansion over the past half-decade, rising from a baseline in 2020 to an estimated USD 392.21 Million in 2025, and our modeled trajectory projects the market to reach approximately USD 509.21 Million by 2032, reflecting a compound annual growth rate (CAGR) of 3.8% across the 2026–2032 forecast window. These macro dynamics mask important tactical inflection points—technology substitution, supplier concentration, supply‑chain stressors and emerging sovereign integration programs—that will materially affect platform design, lifecycle cost and procurement timelines in the coming 12–36 months.
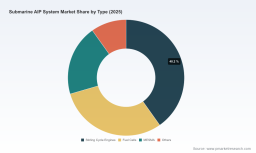
Submarine Aip System Market
Why this report matters for 2026
- Procurement timing: 2026 is a decision year for several navies finalising mid-life upgrades and new-build specifications. Our scenario-based timelines detail when AIP suppliers can realistically deliver validated systems and the lead times that prime contractors must embed into RFPs.
- Technology trade-offs: The report quantifies operational trade-offs between Stirling engines, fuel cells and reformer-based solutions in discrete mission profiles (patrol endurance, acoustic signature, logistics footprint), enabling program managers to translate system-level performance into procurement requirements without overpaying for marginal endurance gains.
- Supply-chain risk overlay: We map raw-material exposure (notably metals and specialized hydrogen storage components) against supplier concentration to forecast price and delivery volatility that will influence contract structuring and IV&V schedules.
- Competitive positioning: For OEMs and component suppliers, the report outlines where to prioritise R&D, strategic partnerships and regional business development to capture share in an industry where the top three vendors account for over half of market revenues and the top five approach a substantial majority.
Report contents — practical deliverables
The PW Consulting study is designed as a hands-on toolkit for commercial and defence stakeholders. Key deliverables include:
Submarine Aip System Market
- Market model and forecast (2026–2032) with base-year calibration and sensitivity analyses to test low / base / high demand paths.
- Technology assessment matrix contrasting lifecycle costs, acoustic signatures, maintainability, and integration risk for Stirling, PEM fuel cells, MESMA and hybrid approaches.
- Supplier benchmarking and capability heatmaps: manufacturing capacity, IP ownership, integration track-record, and aftermarket footprint.
- Procurement playbooks: contract structures (fixed-price vs. cost-plus), milestone-based acceptance criteria, acceptance-test templates and warranty regimes aligned to AIP-specific failure modes.
- Supply‑chain risk register: critical materials, single‑source dependencies, and mitigation options (inventory strategies, second-source qualification, material substitutions and advanced contracting terms).
- Scenario workshops and war-gaming inputs: modular scenarios for planners assessing escalation-driven refit cycles and export market shocks.
- Confidential appendices available to subscribers: vendor-level scorecards, validated supplier financial models, and granular segmentation data by region, platform type and retrofit vs. line-fit adoption (not disclosed in public summary to protect client value).
Competitive landscape — who matters and why
The global AIP market is characterised by a limited set of technology specialists and a handful of vertically integrated yards. Market concentration metrics indicate a market where the top three suppliers capture a majority of revenues and the top five suppliers hold an even larger cumulative share—an environment that favours established primes but creates opportunities for disruptive component innovators.
Submarine Aip System Market
- Saab AB (Kockums) — Sweden ( https://www.saab.com): A proven Stirling engine AIP provider with operational deployments on Gotland-class and A26 platforms. Saab’s strengths lie in acoustic performance and mature integration practices, making it a preferred partner where stealth and operational endurance are primary requirements.
- thyssenkrupp Marine Systems (TKMS) — Germany ( https://www.thyssenkrupp-marinesystems.com): TKMS pursues PEM fuel cell solutions in collaboration with systems integrators. With experience in Type 212A/214 derivatives and several export programs, it is positioned where navies prioritise established fuel-cell technology with defense-grade industrial chains.
- Siemens AG — Germany ( https://www.siemens.com): A leading developer of PEM fuel cell modules for marine integration. Siemens’ role is frequently as a technology partner and module supplier to shipyards and prime contractors, translating automotive and stationary fuel-cell learnings into submarine-compatible systems.
- Naval Group — France ( https://www.naval-group.com): Brings MESMA and second-generation fuel-cell concepts to market, including onboard hydrogen production via diesel reforming in certain design sets. Naval Group’s R&D focus is on broadening operational autonomy and integrating hybridized energy systems.
- Hanwha Ocean — South Korea ( https://www.hanwhaocean.co.kr): Integrates hybrid AIP architectures on domestic KSS-III builds and is actively developing exportable submarine platforms with AIP options. Recent approvals and launches signal growing competitiveness in Asia-Pacific markets.
- Navantia — Spain ( https://www.navantia.es): Pursues alternative AIP approaches such as bioethanol reforming and maintains strategic collaborations on S-80 platforms and export programs where flexible fuel approaches are attractive.
- China Shipbuilding Industry Corporation (CSIC): Delivers indigenous AIP-equipped submarines and continues to evolve fuel-cell and AIP technologies within domestic production lines. CSIC is a major regional force with implications for regional demand and supplier competition.
Recent industry developments and implications
The market is dynamic through 2025–2026, with several catalysts rapidly altering procurement calculus:
- DRDO and Indian Navy reported progress toward integrating an indigenous fuel‑cell AIP into a Kalvari-class refit program, signalling a push for strategic autonomy and potential acceleration of domestic retrofit pipelines.
- Hanwha Ocean’s approval-in-principle for a 2,000-ton export design and the launch of KSS‑III Batch‑II with hybrid AIP systems underscore South Korean ambitions to export AIP-capable platforms and strengthen regional competition.
- Commercial orders and follow-on options for PEM‑equipped submarines continue to support European and Asian yards; any production disruptions among key European suppliers would ripple across schedules due to concentrated supplier capacity.
- Geopolitical measures, including sanctions affecting shipments of titanium and nickel, have introduced supply‑side fragility for certain propulsion components and pressure on lead times and cost-builds.
Supply‑chain and materials risk
AIP systems are materially sensitive to a narrow set of specialized inputs—hydrogen storage media (metal hydrides, cryogenic systems), catalysts and select structural alloys. Our analysis highlights three practical mitigation levers:
- Structural hedging: incorporate long‑lead purchase options and strategic inventory terms into prime contracts, calibrated to forecast volatility windows.
- Dual sourcing and qualification: accelerate parallel qualification of alternate vendors for critical components and run cross-compatibility testing during early-stage integration to shorten recovery timelines.
- Design-for-substitutability: specify modular interfaces that allow later replacement of storage or power modules without full platform rework, reducing technical debt for upgrades.
Policy, geopolitics and procurement strategy
Sanctions, localisation imperatives and sovereign technology drives are reshaping programme risk. The growing emphasis on indigenous AIP solutions—highlighted by state-led integration programmes—will change decision matrices for export approvals, industrial co-operation clauses and long‑term sustainment contracts. Our report provides checklist-driven guidance for contracting officers drafting offset obligations, IP-sharing agreements and in-country sustainment commitments.
Recommendations for 2026 decision-makers
- Embed realistic supplier lead times and validation milestones into any 2026 RFPs; assume multi-year qualification for new hydrogen storage technologies.
- Prioritise acoustic performance and integration risk over headline endurance figures when selecting AIP type for littoral platforms; marginal endurance gains can trigger outsized cost and schedule exposure.
- Negotiate modularity and upgrade paths into contracts to preserve flexibility as fuel-cell and hydrogen handling technologies evolve.
- Use supplier scorecards and financial covenants to reduce vendor default risk where the market shows high concentration by revenue share among leading firms.
- Consider strategic partnerships or minority equity positions in component suppliers to secure access to critical technology and to smooth procurement cycles under sanctions or material constraints.
Accessing the full report
This release is a strategic preview. PW Consulting’s full Submarine AIP System Market report contains the granular segmentation, vendor scorecards, and downloadable market models that procurement teams, platform primes and technology investors need to finalise decisions in 2026. To preserve client value and maintain advisory exclusivity, detailed region- and application-level splits are available only in the subscriber edition.
For licensing, data extracts or to arrange a briefing with PW Consulting’s submarine propulsion practice, contact our industry desk. The intelligence contained in the full report is structured to inform procurement timelines, capital budgeting cycles and R&D prioritisation for the 2026 planning window and beyond.
For detailed analysis of this topic, please visit the official page: Submarine Aip System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com