

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Light Commercial Vehicle Transmission Market Poised to Expand at a 5.71% CAGR (2026–2032)

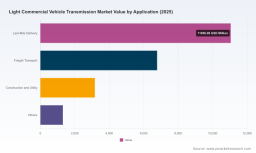
Light Commercial Vehicle Transmission Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on Light Commercial Vehicle (LCV) transmissions delivers an operationally focused intelligence package for executives, product strategists, procurement leads, and M&A teams making critical 2026 decisions. Our analysis synthesizes historical performance (2020–2025), a forward forecast (2026–2032) and scenario-led strategic playbooks to convert near‑term disruption into durable advantage.
Light Commercial Vehicle Transmission Market
Executive snapshot
The global LCV transmission market was valued at approximately USD 22,320 Million in 2025 and is projected to grow through our 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.71%. By the end of the forecast period the market trajectory points toward a materially larger addressable base as vehicle powertrain diversity and regulatory pressure reshape product and supply chain economics. Market concentration remains moderate: the top three suppliers account for roughly 38.5% of global revenues, while the top five capture approximately 52.7% — a dynamic that creates both consolidation opportunities and niches for focused innovators.
Light Commercial Vehicle Transmission Market
Why 2026 is a pivotal year
-
Regulatory inflection points (fuel economy and emissions) coming into force across major markets are accelerating demand for advanced multi‑speed and electrified transmission systems.
Light Commercial Vehicle Transmission Market -
Component cost volatility—notably in steel and aluminum—means product cost curves must be revalidated against new sourcing and design strategies this year to protect margin targets.
-
Trade policy shifts, including recent tariff actions affecting imported vehicle parts, are forcing OEMs and suppliers to reassess footprint, inventory policy, and near‑term supply contracts.
-
Major OEMs and tier‑1 suppliers are moving from announcement to deployment (product launches and production ramps), creating windows for competitive positioning ahead of full market adoption.
Data‑driven implications for strategy
-
Portfolio prioritization: With a predictable market expansion at ~5.7% CAGR, firms should accelerate investment in powertrain variants that align to regulatory and operational cost drivers—particularly electrified modules and multi‑speed automatics—while pruning low‑margin legacy platforms.
-
Supply‑chain hedging: Raw material volatility requires a two‑track approach—short‑term procurement hedges combined with medium‑term design migration to materials and architectures that reduce exposure to metal price swings.
-
Manufacturing footprint: Tariff regimes and regional demand shifts justify revisiting plant location strategies and dual‑sourcing for transmission cores to limit single‑point risks and tariff exposure.
-
Aftermarket and services monetization: As LCV fleets scale electrified and automated drivetrains, service, software and upgrade pathways become critical recurring revenue streams that can offset tighter hardware margins.
Competitive landscape — who matters and why
The competitive set combines legacy transmission specialists and diversified powertrain suppliers. Below are concise strategic reads on market participants that matter for 2026 planning.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany — https://www.zf.com): ZF continues to press its multi‑speed automatic leadership into the LCV segment with product launches geared to medium‑duty use cases. Its strategy emphasizes platform scalability and system reliability, enabling OEMs to accelerate fleet uptime and lower lifecycle costs.
-
Aisin Corporation (Kariya, Japan — https://www.aisin.com): Aisin’s strength lies in compact, high‑efficiency automatic and dual‑clutch architectures with options for hybrid integration. Their product roadmap is oriented toward packaging density and integration with RWD and hybrid powertrains, making them a go‑to partner for OEMs seeking balance between cost and electrification readiness.
-
Allison Transmission Holdings, Inc. (Indianapolis, USA — https://www.allisontransmission.com): Allison’s 1000/2000 series remain benchmarks for durability in delivery, shuttle and utility markets. Their competitive edge is mission‑proven durability and strong aftermarket networks, positioning them to defend core segments even as drivetrain electrification progresses.
-
Eaton Corporation (Dublin, Ireland — https://www.eaton.com): Eaton is transitioning robustly toward automated and dual‑clutch solutions for light‑duty commercial vehicles. Recent introductions reflect a focus on reduced driver load and improved fuel efficiency—attributes that fleet managers will value under stricter regulation and total cost of ownership scrutiny.
-
BorgWarner Inc. (Auburn Hills, USA — https://www.borgwarner.com): As a specialist in electrification modules and hybridized transmissions, BorgWarner is positioned to capture demand where electrified drive modules are specified. Their modular approach reduces integration complexity for OEMs moving to EV/HEV LCV variants.
-
Dana Incorporated (Maumee, USA — https://www.dana.com): Dana focuses on drivetrain component systems and e‑transmissions, combining mechanical expertise with power electronics. Their strategy supports both OEMs and tier‑1 suppliers in adapting traditional architectures to hybrid and fully electric LCV platforms.
-
Magna International Inc. (Aurora, Canada — https://www.magna.com): Magna pursues a systems integration play—DCTs, e‑drives and electrified powertrain modules—targeting OEMs that prefer single‑supplier systems capable of rapid vehicle integration and scale.
Recent developments shaping 2026 actions
-
ZF launched an 8‑speed PowerLine transmission application for medium‑duty platforms in early 2026 — illustrating continued investment in high‑gear‑count automatics for efficiency gains.
-
Eaton’s Advantor‑6 automated manual (introduced 2025) targets lighter duty trucks and buses, signaling competition in automated transmissions beyond traditional AT vs MT dichotomies.
-
Aisin’s 2025 announcement of a compact DCT tailored for light trucks underscores supplier focus on electrification‑friendly, high‑efficiency solutions.
-
OEM production starts (e.g., SOLLERS in 2025) highlight that vehicle programs are moving from development into series production—accelerating parts demand and creating near‑term supply windows.
Report deliverables — what’s inside (practical, not platitudes)
-
Quantitative market sizing and a transparent forecast model (2026–2032) with scenario toggles for regulatory, material‑cost, and adoption‑rate sensitivities.
-
Supply chain heatmaps and supplier risk scoring designed to prioritize dual‑sourcing and on‑shoring investments.
-
Competitive benchmark dashboards covering product architectures, go‑to‑market positioning, and aftermarket reach for the leading suppliers.
-
Commercial playbooks including pricing sensitivity analysis, contract clause templates for tariff mitigation, and procurement hedging scenarios.
-
M&A screening framework and priority target lists based on capability gaps (e‑drive modules, compact DCTs, control software) and cultural integration risk metrics.
-
Investment case templates for CAPEX decisions, including a three‑tier prioritization matrix (protect, optimize, pivot) for product lines and plants.
Actionable recommendations for 2026
-
Rebase product roadmaps around regulatory milestones and fleet economics. Prioritize electrified and multi‑speed automatic modules where TCO improvements are measurable within 3–5 years.
-
Implement a two‑layer procurement strategy: tactical hedges to manage immediate metal price risk, and strategic supplier partnerships to move to lower‑intensity materials and modular architectures.
-
Reassess manufacturing footprint now in light of new tariff regimes; evaluate near‑market micro‑factories and flexible cells that reduce exposure to cross‑border duties.
-
Monetize software and servicing: build or partner for telematics, predictive maintenance and over‑the‑air update capabilities to create annuity revenue as fleets adopt new powertrain technologies.
-
Pursue bolt‑on M&A for missing capabilities (compact DCTs, e‑transmission modules, rapid‑integration control software) and use JV structures where local content rules or tariffs make full acquisition unattractive.
Constraints and what we deliberately withhold
To preserve the integrity of our published offering and to encourage investment in primary data, this release intentionally omits granular regional and application split figures and detailed segment dollar tables. The executive framework and recommendations above are fully actionable; however, the underlying micro‑segmentation data, supplier share matrices by region and application, and the model’s sensitivity tables are available exclusively in the full PW Consulting report.
Next steps — how to operationalize this intelligence
-
Download the full report to access the complete forecast model, supplier share matrices and playbooks for procurement and M&A teams.
-
Book a 90‑minute executive briefing with PW Consulting to run your specific scenarios (tariff exposure, plant relocation, product cut‑over timelines) using our interactive model.
-
Engage our integration team for a rapid 8‑week diagnostic on your transmission product portfolio, manufacturing footprint and supplier risk exposure to translate insights into a 2026 implementation roadmap.
PW Consulting’s Light Commercial Vehicle Transmission Market report is built for executives who must make 2026 decisions that matter — balancing near‑term cost pressures, evolving regulation, and the rapid march toward diversified powertrains. For the full data set, segmented analysis, and downloadable forecast model, visit the PW Consulting report page or contact our industry practice to schedule a confidential briefing.
For detailed analysis of this topic, please visit the official page: Light Commercial Vehicle Transmission Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com