

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2,5‑Dimethyl‑2,4‑Hexadiene Market Poised to Grow at a 4.51% CAGR Through 2032

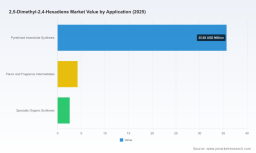
PW Consulting Strategic Brief: 2,5‑Dimethyl‑2,4‑Hexadiene Market — 2026 Strategic Guidance for Market Leaders
As companies refine their chemical portfolios and procurement strategies for 2026, PW Consulting’s latest market study on 2,5‑Dimethyl‑2,4‑Hexadiene (2,5‑DM‑2,4‑HD) delivers a focused, decision‑grade view on a specialty intermediate whose strategic footprint is expanding across agrochemical synthesis, flavors & fragrances, and specialty organic pathways. The market has expanded steadily from the early 2020s, growing from approximately USD 34 million in 2020 to about USD 42.5 million in our base year of 2025, and the PW forecast projects continued expansion through our 2026–2032 horizon to roughly USD 57.8 million by 2032 at a compound annual growth rate of 4.51%. This trajectory underscores the compound’s resilient demand profile amid shifting upstream and regulatory conditions.
2,5-Dimethyl-2,4-Hexadiene Market
Why 2026 is a Pivotal Year for Strategic Decision‑Makers
-
Portfolio prioritization. Buyers and producers face a juncture where tactical procurement moves must be converted into medium‑term structural choices: selective vertical integration, contractual exclusivity with specialty suppliers, or exposure to price swings through spot purchasing.
2,5-Dimethyl-2,4-Hexadiene Market -
Supply‑side concentration. Market concentration metrics indicate a meaningful role for established producers and distributors: the top three suppliers control a material share of supply, and the top five amplify that concentration further. This creates both competitive leverage for incumbents and negotiation pressure for downstream buyers.
2,5-Dimethyl-2,4-Hexadiene Market -
Upstream feedstock exposure. The predominant synthesis routes trace back to C4 hydrocarbon streams—notably isobutylene and isobutyraldehyde—linking 2,5‑DM‑2,4‑HD economics to petrochemical refining cycles and the availability of C4 derivatives.
-
Regulatory and substitution risk. Use of the intermediate in insecticide synthesis and specialty organic chemistry places the molecule at the intersection of pesticide regulation, fragrance ingredient safety review, and greener‑chemistry adoption—factors likely to shape demand and acceptable product specifications in 2026 and beyond.
What the PW Report Delivers — Practical Intelligence, Not Just Numbers
-
Robust macro sizing and forward‑looking scenarios. Clear baseline sizing (2020–2025), an expert‑validated forecast (2026–2032) and three scenario pathways that translate market drivers into material outcomes for procurement and investment planning.
-
Supply‑risk heatmaps. Identification of single‑point dependencies (both geographic and feedstock), supplier concentration mapping, and contingency strategies to defend operations against availability shocks.
-
Price‑scenario models. Dynamic models that convert crude/C4 derivatives and processing cost inputs into delivered price sensitivities under a range of demand and feedstock volatility assumptions.
-
Competitive benchmarking and capability matrices. Actionable supplier profiles (technical capabilities, typical packaging/purity tiers, geographical reach, and quality certification posture) to support sourcing decisions and RFP design.
-
Operational playbooks. Step‑by‑step guidance for contract negotiation, quality assurance protocols for on‑spec deliveries, small‑scale versus bulk procurement tradeoffs, and on‑site capacity build versus toll synthesis economics.
-
M&A and partnership signal map. A prioritized list of capability gaps, potential bolt‑on targets, and partnership archetypes to accelerate access to high‑purity manufacturing, downstream formulation expertise, or regional distribution networks.
-
Regulatory and sustainability roadmap. Anticipated review cycles, likely compliance cost scenarios, and practical levers to reduce lifecycle impact and enhance customer acceptance in sensitive applications.
Competitive Landscape — Who Matters (and How to Read the Field)
The supplier universe for 2,5‑DM‑2,4‑HD is a mix of established international reagent distributors, specialty chemical manufacturers, and a sizeable cohort of China‑based bulk suppliers and traders. Each archetype brings different value propositions and strategic considerations:
-
Global reagent and distributor players (examples include long‑standing life‑science and specialty chemical houses) typically supply research‑grade material in small pack sizes, often offering stabilized grades or documentation tailored for laboratory and synthesis markets. Their strengths are brand recognition, regulatory traceability, and service levels for small‑volume, high‑value customers.
-
Regional manufacturers and traders, particularly those based in Asia, provide scale, high‑purity variants, and flexible packaging from laboratory to bulk. These suppliers create a cost‑competitive alternative for industrial users but require disciplined quality and supply‑chain qualification by buyers.
-
Mid‑market suppliers and distributors in North America and Europe occupy a middle ground—offering logistical convenience and faster lead times for regional consumers, often with the necessary documentation for regulated applications.
Strategically, companies should balance supplier portfolios across these archetypes—locking in quality and traceability where regulatory or formulation sensitivity demands it, and leveraging cost and scale from bulk suppliers where tolerances permit. Our analysis highlights where premium pricing, logistical reliability, and technical support justify a higher total cost of ownership versus where price‑leadership is the paramount criterion.
Supply‑Chain & Raw‑Material Dynamics
The dominant industrial synthesis pathway for 2,5‑DM‑2,4‑HD stems from acid‑catalyzed condensation chemistry involving isobutylene (or tert‑butanol intermediates) with isobutyraldehyde. These feedstocks are downstream products of C4 hydrocarbon fractionation in petrochemical refining. The practical implication is a direct sensitivity of intermediate costs and availability to refinery throughput, cracker margins, and seasonal maintenance cycles.
For 2026, two risk themes should be prioritized: 1) feedstock squeeze scenarios driven by refinery capacity adjustments or cracking economics; 2) logistics and packaging constraints as demand shifts between laboratory sizes and industrial bulk volumes. The PW report includes mitigation strategies—feedstock hedging frameworks, tolling and co‑processing options, and targeted investments in in‑house purification—to reduce exposure to upstream cycles.
Regulatory, Sustainability and Technology Trends
-
Regulatory scrutiny of pesticide intermediates and fragrance ingredients is increasing in several jurisdictions. Companies should expect more rigorous impurity profiling and documentation requests from formulators and regulators.
-
Green‑chemistry and process intensification present dual opportunities: lowering unit costs through catalytic route optimization, and creating market differentiation via lower environmental footprints. Technical literature and patent activity indicate incremental improvements in catalytic condensation and selective processing that can be de‑risked through pilot trials.
-
Traceability and life‑cycle transparency will become competitive advantages: suppliers that can deliver robust QC data, carbon‑intensity estimates, and verified chain‑of‑custody will unlock preferred supplier status with multinational formulators.
2026 Strategic Playbook — Prioritized Actions
-
Immediate (0–3 months): Conduct a concentrated supply‑risk audit. Map single‑sourced inputs, quantify exposure to C4 feedstock price moves, and secure short‑term supply through contracts with at least two supplier archetypes (specialty distributor + bulk manufacturer).
-
Near term (3–12 months): Implement a procurement dual‑track. Combine longer‑term offtake frameworks with spot allocations and establish quality‑assurance clauses for high‑purity grades. Run pilot purification or blending trials to increase tolerance to supplier mix.
-
Medium term (12–24 months): Evaluate vertical or horizontal moves—tolling arrangements, minority stakes in regional producers, or bolt‑on acquisitions to secure feedstock or capacity. Invest in process R&D that lowers dependence on volatile C4 streams or enables co‑product valorization.
-
Ongoing: Monitor three lead indicators—C4 crude spreads, regulatory developments in target end‑use jurisdictions, and in‑market purity/specification requests from key customers. Use these signals to trigger contract renewals, price‑index adjustments, or capex reallocation.
Why PW’s Report is Decision‑Grade for 2026
Our study moves beyond static figures to deliver scenario‑based decision frameworks, supplier scorecards, and cost modeling templates you can operationalize immediately. The macro outlook and concentration measures make the strategic stakes clear: organized buyers who combine supplier diversification, feedstock risk management, and selective investment in processing capability will capture margin and secure supply in a moderately concentrated market.
The report is intentionally structured as a “trailer” of insight here—demonstrating the depth and practical applicability of the analysis while reserving granular regional and application splits for the full publication. Those segment and regional detail pages include granular demand drivers, price elasticity matrices by end use, and downloadable supplier qualification templates designed to be plugged directly into RFP and procurement workflows.
For companies preparing budgets and capital plans in 2026, PW Consulting’s 2,5‑Dimethyl‑2,4‑Hexadiene market study provides the nexus between market intelligence and executable strategy. Access the full report to obtain the detailed segment and regional intelligence, downloadable models, and supplier dossiers that will materially shorten your path from insight to action.
For detailed analysis of this topic, please visit the official page: 2,5-Dimethyl-2,4-Hexadiene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com