

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biomass For Power Generation Market to Expand at 6.89% CAGR Through 2032

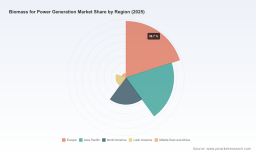
Biomass for Power Generation 2026: Strategic Imperatives for Corporate Decision‑Making
PW Consulting is pleased to release a focused briefing from our upcoming Biomass for Power Generation Market report, designed to equip corporate leaders, investors and policy teams with the strategic intelligence they need to act in 2026. The global market for biomass-based power has shown steady expansion through the mid-2020s and — under a range of realistic policy and commodity scenarios — is forecast to continue growing at a mid‑single‑digit compound annual growth rate (CAGR). Our base-year view (2025) places the market firmly above the hundred‑billion‑dollar threshold, with near‑term projections indicating a meaningful step up in 2026 and sustained expansion through 2032.
Biomass For Power Generation Market
Why this matters in 2026
-
Policy momentum and capital reallocation are converging. New and expanded tax credit frameworks, targeted appropriations, and proposals to broaden carbon‑credit eligibility are changing project economics for both retrofits and greenfield biomass plants.
Biomass For Power Generation Market -
Feedstock markets are maturing. Commercial scale densified fuels, agricultural residues and industrial residues are now price‑actionable inputs for project underwriting — but regional cost and logistics variance materially affect competitiveness and risk.
Biomass For Power Generation Market -
Technology and system integration expectations are rising. Investors expect robust carbon accounting, optionality for carbon capture, and resilience of local fuel supply chains as preconditions for financing.
Market trajectory — a concise snapshot
From 2020 through 2025 the sector expanded consistently, and our forecast for 2026 reflects that momentum: a step change versus 2025 driven by new commissioning activity, policy incentives, and improving fuel logistics. Across our 2026–2032 forecast window, we apply a central CAGR of 6.89% to reflect a balanced view of demand growth, substitution dynamics versus other renewables, and the increasing role of biomass in dispatchable, firm low‑carbon power mixes. By 2032 the market is expected to be materially larger than in 2025, underlining multi‑year commercial opportunity for project developers, utilities and equipment suppliers.
What the PW Consulting report delivers — practical, decision‑ready content
-
Investment Prioritization Frameworks — a repeatable method to rank greenfield versus conversion opportunities by return profile, policy sensitivity and feedstock risk.
-
Project Finance Playbooks — lender due‑diligence checklists, covenant structures and sensitivity templates that reflect recent tax‑credit regimes and appropriations language.
-
Supply‑Chain Stress Tests — scenario models covering feedstock price inflation, transport bottlenecks and seasonal availability, with mitigation options (contract structures, storage, dual‑feedstock designs).
-
Carbon and Lifecycle Accounting Tools — standardized templates and sample disclosures aligned with leading market and regulatory expectations, including pathways to demonstrate lifecycle GHG parity or net‑zero performance where achievable.
-
Operational Benchmarks — capex/opex ranges, heat‑rate baselines, availability and maintenance norms for common technology routes, plus modular approaches for CHP and hybridization.
-
Commercial Contracts and Offtake Templates — draft clauses for feedstock supply, fuel quality specifications and long‑term power offtake agreements that reflect real‑world contract failure modes.
-
M&A and Partnership Screening — target‑scoring matrices that factor in asset scale, feedstock control, regulatory exposure and integration upside.
-
Country Playbooks — actionable entry and exit rules for prioritized markets, including permitting timelines, local content expectations and hydrogen / CCUS interface points.
Competitive landscape — how incumbent and new entrants are positioning
The biomass power sector features a mix of large utilities retrofitting legacy assets, specialized fuel producers, EPCs and equipment vendors all working across complementary parts of the value chain. Market concentration remains modest by global energy standards, with top firms together holding a minority share of installed capacity — a structure that favors strategic partnerships, regional scale plays, and targeted roll‑ups.
-
Drax Group Plc (UK): A vertically integrated model combining large converted power stations and a global pellet supply chain. Their strategy underscores the advantage of feedstock control when seeking scale and bankability.
-
Ørsted A/S (Denmark) and major European utilities (including ENGIE, RWE, Vattenfall and EDF): Utilities are pursuing selective biomass operations often as part of coal‑to‑biomass conversions or mixed‑fuel portfolios that provide dispatchable balancing capacity alongside variable renewables.
-
Enviva and other pellet producers: Specialized fuel suppliers are advancing densification and logistics solutions that enable longer‑haul trade and project viability in import markets.
-
Equipment and services firms (Babcock & Wilcox, Mitsubishi Heavy Industries, JFE Engineering): Deliver engineering expertise and modular technology options that accelerate plant conversions and optimize combustion/gasification performance.
-
Regional developers and project owners (ACCIONA, Ameresco, EPH, Erex, POWERCHINA and several new entrants): These firms are executing geographically targeted projects and, in several cases, integrating local feedstock processing to improve resilience and margins.
Recent project milestones demonstrate two clear dynamics: (1) Capable EPCs and developers continue to commission medium‑to‑large projects across Europe and Asia, and (2) upstream processing capacity (for feedstocks such as palm kernel shell and densified wood fuels) is expanding where local markets support industrial‑scale fuel processing. These developments create practical near‑term opportunities for off‑takers, financiers and equipment suppliers — but they also raise the bar for due diligence on fuel sustainability and lifecycle emissions.
Regulation, incentives and the carbon lens — implications for 2026 actions
Policy is an active driver for this sector in 2026. In key markets, biomass generators can now access technology‑neutral clean electricity tax credits and investment credits when they demonstrate sufficiently low lifecycle GHG emissions. Parallel legislative proposals seek to expand carbon‑crediting mechanisms to include products derived from forest residues for wildfire mitigation. At the same time, appropriations language in some jurisdictions includes explicit support for biomass sustainability measures and deployment incentives.
Strategic implications:
-
Companies should model project returns both with and without prospective tax credits and factor time‑to‑qualification into construction schedules and contract timing.
-
Carbon accounting capacity is now a competitive necessity. Projects that can credibly demonstrate lifecycle emissions reductions (including through feedstock sourcing and supply‑chain decarbonization) capture a pricing premium in financing and offtake negotiations.
-
Opportunities to pair biomass plants with emerging CCUS or productization pathways (e.g., biochar, bioproducts) are increasingly valuable — both for economics and for meeting evolving regulatory tests.
Feedstock economics and operational risk
Feedstock price variation and logistics remain the most material operational risks to project economics. Recent reporting shows that densified biomass markets exhibit price differentials between domestic consumption and export streams, and local gate prices for mixed residue feedstocks can be an order of magnitude different from densified export fuel prices depending on harvest timing, preprocessing and transport dynamics.
For 2026 decision‑making we recommend:
-
Locking early on diversified supply pools (local residues + densified imports) where feasible to reduce single‑source exposure.
-
Investing in local processing or strategic equity in fuel processors when feedstock cost or reliability is a primary value driver.
-
Designing contracts with indexed pricing, fallback sourcing and quality corridors to protect plant availability and performance metrics.
Where strategic value for executives and investors lies
-
Timing and structuring of capital: Projects that can demonstrate near‑term eligibility for incentives and robust feedstock security can achieve lower cost of capital — a decisive advantage in 2026‑2028 procurement cycles.
-
Integration and vertical control: Securing parts of the value chain — fuel processing, logistics hubs, pellet manufacturing — materially de‑risks operations and enhances negotiating leverage.
-
Technology choices: Selecting combustion, gasification or hybrid approaches should be guided by fuel quality, project scale and optionality for CCUS or co‑products — our report provides techno‑economic comparators and decision trees.
-
M&A lenses: Because the largest players collectively hold only a minority share of the market, targeted M&A and platform builds remain effective routes to rapid scale and regional dominance.
What we are intentionally holding back (and why)
This briefing intentionally presents the strategic contours and executable implications of the biomass power market without disclosing the granular regional, source‑type and technology split tables contained in the full report. Those detailed segment shares, country‑level unit economics, and company market‑share matrices are essential to project‑level decisions and are reserved for subscribers and purchasers of the full study. Our “trailer” approach is designed to give readers a confidence‑building preview of analytic depth while encouraging access to the full dataset that underpins underwriting models and M&A screening tools.
How to use this insight in your 2026 planning cycle
-
Update project underwriting to include scenario runs that reflect policy qualification timing and feedstock volatility.
-
Pursue partnerships with regional pellet/processors and EPCs where speed to market matters.
-
Embed carbon‑lifecycle accounting into commercial and technical due diligence as a gate for investment approval.
-
Consider optionality for CCUS/productization as a value‑creating bolt‑on for larger assets.
PW Consulting’s full Biomass for Power Generation Market report contains the country, feedstock and technology splits, granular price tables, company profiles, and downloadable financial models that sophisticated investors and operators need to execute in 2026. For access to the complete dataset and executable annexes, please visit our report page or contact our client services team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Biomass For Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com