

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High-Performance Fibers for Defense Market Poised to Grow at an 8.52% CAGR, New Report Finds

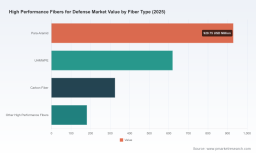
High Performance Fibers for Defense: Strategic Imperatives for 2026
Executive snapshot
The global market for high performance fibers serving defense applications has moved from a niche, capacity-constrained segment into a predictable, investable market poised for sustained expansion. Our PW Consulting market model, built on 2020–2025 observation and benchmarked supplier intelligence, shows the market growing from roughly USD 1,385 million in 2020 to USD 2,056.35 million in the 2025 base year. Under our central forecast (2026–2032), the market is expected to expand at a compound annual growth rate (CAGR) of 8.52%, reaching an estimated USD 3,644.74 million by 2032. Market concentration is meaningful: the top-three and top-five players jointly account for nearly half and over sixty percent of the market respectively, creating a competitive environment defined by scale, qualification reach, and supply security.
High Performance Fibers For Defense Market
Why this matters for 2026 corporate decisions
-
Procurement and program risk: Defense OEMs and prime contractors face multi-year qualification cycles (typically 2–5 years) — decisions made in 2026 about suppliers, specifications, and test programs will determine program readiness through the next generation of platforms.
High Performance Fibers For Defense Market -
Supply-side scarcity and capital intensity: Production routes for para-aramid and UHMWPE fibers require specialized chemistries and high-capex processes (e.g., gel-spinning with solvent recovery). Capacity decisions and alliances made now materially affect lead times and cost exposure in 2027–2029.
High Performance Fibers For Defense Market -
Raw-material and regulatory exposure: Para-aramid precursors are petrochemical-derived and sensitive to upstream benzene/xylene price swings; UHMWPE processes depend on solvent systems and recovery operations. Export controls and trade restrictions further complicate cross-border sourcing strategies.
-
Technology-led differentiation: Advances in carbon fiber grades and next-generation aramids are reshaping weight-performance tradeoffs for armor and structural composites. Early access to newly qualified fibers can be a decisive competitive advantage for platform integrators.
What this PW Consulting report delivers (practical contents)
Designed as both a strategic brief and an operational playbook for 2026 decision-makers, the report combines transparent market modelling with field-validated supplier intelligence and executable tools. Key deliverables include:
-
Dynamic market model (2020–2032): granular topline scenarios, sensitivity testing by demand drivers, and modular inputs so corporate planners can re-run scenarios with proprietary assumptions.
-
Supply-chain maps and qualification calendars: supplier footprints, lead‑times per technology family, and an end-to-end ― from precursor to finished fiber ― timeline that highlights the 2–5 year certification window for defense use.
-
Cost-driver analysis and TCO templates: componentized cost models showing the impact of raw-material volatility, solvent recovery performance, and throughput improvements on unit economics.
-
Risk and mitigation playbooks: recommended hedging structures, inventory policies, and contracting formats (e.g., capacity reservation, indexed pricing, and strategic offtake) tailored to different organizational risk appetites.
-
Technology and product roadmaps: evaluation framework for next-gen para-aramids, UHMWPE, and high-modulus carbon fibers, including qualification pathways and companion testing protocols.
-
Competitive and M&A scanner: profiles of incumbent leaders, challenger technology entrants, and bolt-on targets that align with bolt-on capacity or critical IP; a short list of value-creation levers for potential acquisitions.
Competitive landscape — what to watch in 2026
The industry is anchored by a small set of globally integrated suppliers that combine materials IP, defense qualifications, and scale manufacturing. Several archetypes are visible:
-
Technology/IP leaders with broad defense qualifications — companies with long-established para-aramid or UHMWPE brands continue to command premium placement on ballistic- and armor-related programs. They leverage decades of testing data and qualification pathways to remain preferred suppliers for military and law-enforcement contracts.
-
Carbon-fiber specialists focused on aerospace/structural composites — firms supplying high-strength, high-modulus carbon fibers are increasingly competing for weight-critical defense structures and missile/aero components by offering integrated prepreg and composite solutions.
-
Regional players and challengers — several East Asian producers deliver high-tenacity yarns and are closing technical gaps, increasing regional sourcing options for defense primes sensitive to single-vendor exposure.
Recent market developments underline these dynamics: long-term supply agreements to secure capacity; launches of higher-modulus carbon fiber grades that materially shift weight-performance tradeoffs; and product portfolio expansions among aramid incumbents to support ongoing military qualifications. For buyers and investors, the strategic question is not whether suppliers will innovate — it is which suppliers will successfully scale and qualify those innovations for defense use ahead of program demand.
Key risk vectors and operational constraints
-
Raw-material volatility: Petrochemical feedstocks and solvent systems remain primary cost drivers. Manufacturing economics are sensitive to both price and availability of precursors.
-
Qualification and certification friction: Multi-year testing and supplier auditing create a lead time that must be anticipated in program timelines; early engagement with suppliers and testing labs shortens time-to-field.
-
Export controls and trade policy: Restrictions on certain specialty fibers and technology transfers can limit sourcing flexibility; compliance-driven delays should be assumed in cross-border procurement strategies.
-
Capital intensity and process complexity: UHMWPE gel-spinning and advanced carbon-fiber production require specialized capex and environmental controls (e.g., solvent recovery), limiting the pool of viable new entrants.
Recommended strategic actions for 2026 (prioritized)
To translate market insight into defensible positioning, PW Consulting recommends the following actions for corporates, primes, and investors as they finalize plans in 2026:
-
Secure qualified supply early: For new programs, initiate supplier pre-qualification and co-development agreements now to align qualification windows with platform delivery schedules. Favor contractual structures that combine capacity reservation with performance milestones.
-
Adopt a tiered sourcing strategy: Combine preferred suppliers for critical, high‑confidence items with regional backups for risk mitigation. Where feasible, negotiate long-term indexed contracts to smooth price exposure to feedstock volatility.
-
Invest in qualification capability: Establish or partner on ballistic and materials test facilities to shorten certification timelines and control program risk.
-
Pursue targeted vertical partnerships or minority stakes: For manufacturers and investors, selectively backing upstream feedstock or specialty fiber capacity can secure preferential access without full greenfield exposure.
-
Operationalize raw-material hedging and process improvements: Implement solvent-recovery upgrades for UHMWPE lines, and adopt material substitution protocols where lifecycle analyses support performance and cost benefits.
-
Make M&A work for integration: Look for bolt-ons that add qualification data, regional manufacturing, or unique grades (e.g., higher-modulus carbon fiber) rather than commoditized volume only.
-
Embed export-control and compliance capability in procurement: Anticipate and model likely restrictions in sourcing scenarios and maintain an auditable compliance trail for cross-border programs.
Conclusion — the strategic value of the report for 2026
For boards, chief procurement officers, product and program leaders, and financial sponsors making decisions in 2026, the interplay of multi-year qualification cycles, concentrated supplier economics, and raw-material exposure makes planning both urgent and high-impact. Our report translates these technical and commercial levers into executable strategies: who to partner with, when to lock capacity, what technology bets are defensible, and how to structure contracts to preserve optionality.
PW Consulting’s High Performance Fibers for Defense Market report provides the datasets, scenario tools, supplier maps, and playbooks that organizations need to convert market foresight into operational advantage. For full segmentation, underlying tables, supplier scorecards, and our downloadable model, access the full report on the PW Consulting research page or contact our advisory team for a tailored briefing and scenario run for your programs.
For detailed analysis of this topic, please visit the official page: High Performance Fibers For Defense Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com