

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Closed Caption Services Market Poised to Reach USD 954.9 Million by 2032

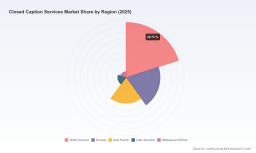
Closed Caption Services Market — Strategic Imperatives for 2026
Executive snapshot
As organizations prepare budgets and vendor strategies for 2026, the closed caption services market has moved from niche compliance support into an operationally critical layer of media and communications infrastructure. Our baseline assessment (base year 2025; historical window 2020–2025; forecast period 2026–2032) shows the market at roughly USD 550.0 Million in 2025, growing at a compound annual growth rate (CAGR) of 8.2% and projected to approach USD 954.9 Million by 2032. This trajectory reflects a confluence of regulatory mandates, faster adoption of automated workflows, and rising demand for accessibility across live and on‑demand formats.
Closed Caption Services Market
Why this market matters to enterprise decision‑makers in 2026
-
Regulatory inflection point: A near‑term compliance deadline for device and service providers is accelerating procurement and implementation timelines. Organizations that treat captioning as a checklist risk last‑minute cost surges and operational friction; those that plan now can convert compliance into differentiated accessibility capabilities.
Closed Caption Services Market -
Technology bifurcation: Automated captioning (AI-driven) is rapidly improving in accuracy and throughput, while professional human‑mediated services remain the gold standard for high‑risk live and legal contexts. The tradeoffs between speed, cost, and accuracy are shifting faster than procurement cycles—requiring new sourcing models and human‑in‑the‑loop designs.
Closed Caption Services Market -
Fragmented supplier landscape: Market concentration remains low (CR3 ~18.5%; CR5 ~24.8%), indicating a competitive and fragmented vendor set. That fragmentation creates supplier choice but also uneven service quality and inconsistent SLAs—enterprises must therefore invest in vendor evaluation frameworks rather than rely on a small incumbent set.
-
Cost and resilience pressures: Rising energy demands in data centers and evolving legislative landscapes (including state and federal shifts on internet rules) introduce cost volatility for cloud‑hosted caption workflows and potential routing complexities for real‑time services.
-
Labor dynamics: Skilled live captioners and court reporters remain a constrained pool with steady openings projected; this limits how quickly purely human solutions can scale and raises the value of hybrid delivery models.
What the PW Consulting report delivers — practical, transaction‑ready intelligence
This market briefing is intended as a strategic preview. The full PW Consulting Closed Caption Services Market report provides operational toolkits and decision support designed for procurement, operations, and compliance teams. The report includes:
-
Vendor scorecards and capability matrices (live, offline, language, SLA, accessibility certifications).
-
Total cost of ownership (TCO) models comparing automated, human, and hybrid architectures across common usage profiles.
-
Implementation playbooks for broadcasting, corporate communications, and education clients that cover latency targets, QC workflows, and escalation paths.
-
Regulatory compliance checklists tied to the upcoming deadlines, mapped to technical requirements and testing templates.
-
Scenario models (base, accelerated AI adoption, regulatory shock) that quantify operational and budgetary impacts through 2032.
To honor the “trailer” principle and preserve the tactical value of our full study, this summary intentionally omits the full segment tables and region/application splits—these granular models and unit‑level forecasts are available in the full report.
Competitive landscape — who moves the market
The provider ecosystem combines specialist accessibility firms, broadcast‑focused incumbents, AI‑native entrants, and nonprofit service providers. Key players to monitor (profiles condensed):
-
3Play Media (Boston) — Known for premium captioning with strong accuracy guarantees and hybrid delivery models suited to education and enterprise video platforms; positions itself where quality and integration matter most.
-
Rev (Austin) — Fast turnaround professional services with an emphasis on web and social video workflows, appealing to content teams that prioritize speed and compliance for consumer platforms.
-
VITAC (part of Verbit) (Canonsburg) — A leading provider for broadcast and live programming with extensive live‑hours capacity; a strategic choice for high‑volume broadcasters and MVPD integrations.
-
CaptionMax (Minneapolis) — Specializes in multilingual captioning and described video services for production and broadcast environments, often chosen for localized and regulatory‑sensitive workflows.
-
Media Captioning Services (Carlsbad) — Longstanding real‑time captioning specialist for news programming and fast‑tempo broadcast; legacy relationships remain a competitive moat.
-
AI‑Media Technologies (Sydney) — Represents the AI‑first cohort delivering live and recorded captioning with integrated transcription and translation—key to scaling multi‑language experiences.
-
National Captioning Institute (NCI) (Chantilly) — A nonprofit provider with institutional trust in broadcast and film; often engaged for public service and large broadcast contracts.
What to watch in 2026: partnerships between AI vendors and human‑centric providers, strategic pricing experiments by automated platforms, and targeted acquisitions by mid‑sized players seeking scale in live captioning. Given the low concentration metrics, consolidation could meaningfully reshape competitive dynamics over a short window—but the timing and scale of such moves remain uncertain.
Regulatory and infrastructure dynamics shaping near‑term strategy
-
Compliance deadlines for “readily accessible” caption controls on devices and multi‑video programming distributors are set to drive implementation activity and demand spikes; organizations supplying endpoints or content‑delivery systems should prioritize interoperability testing and discoverability features.
-
Regulatory uncertainty at the federal level (including recent judicial decisions affecting overarching internet rules) increases the likelihood of state‑level variability—larger enterprises should build jurisdictional compliance flexibility into contracts and product roadmaps.
-
Infrastructure cost headwinds: projected energy demand increases in U.S. data centers will raise the marginal cost of cloud processing for real‑time captioning and transcription; teams should evaluate energy‑aware routing and hybrid on‑prem/cloud designs to stabilize OPEX.
-
Market access shifts: public notices on automated solutions for specialized services (e.g., IP CTS) suggest regulatory bodies are increasingly open to automation—enterprises must balance the speed/cost advantages of automation with quality and legal risk tolerances.
Priority recommendations for 2026
-
Conduct a compliance and risk triage now: map all content‑touchpoints to applicable rules, and run vendor interoperability tests ahead of rollout windows to avoid expensive rework.
-
Adopt hybrid delivery as default: pilot automated captioning with human review for high‑exposure content; use human‑only for legal or high‑stakes live events where accuracy and defensibility matter.
-
Rework procurement metrics: include energy intensity, latency profiles, error‑handling SLAs, and language coverage in RFP scorecards rather than simple price per minute.
-
Design workforce contingencies: create a scalable pool of vetted captioners and cross‑train in QA tooling; invest in tooling that reduces human effort via pre‑editing and guided correction interfaces.
-
Monitor M&A and partnership signals: a vendor consolidation event could compress supplier choice—maintain flexible contracts and keep onboarding capability active so you can switch providers within defined timelines.
Scenario lenses to stress‑test 2026 plans
Use three scenarios to test procurement and operational plans: (1) Baseline growth consistent with the 8.2% CAGR and steady automation adoption, (2) Accelerated AI adoption where automated captioning gains higher share and compresses per‑minute pricing, and (3) Regulatory surge driven by tightened display/accessibility requirements that force accelerated purchasing and implementation. Each scenario materially changes staffing, SLA, and CAPEX/OPEX profiles—our full scenario models quantify these impacts and provide trigger points for planned responses.
Conclusion — how PW Consulting helps you convert compliance into competitive advantage
For 2026, closed captioning is no longer a back‑office obligation; it is a cross‑functional capability that intersects compliance, user experience, and media operations. PW Consulting’s full Closed Caption Services Market report translates the market’s macro trajectory, vendor landscape, and regulatory inflection points into transaction‑ready guidance—vendor shortlists, contract language templates, TCO tools, and staged implementation playbooks.
To access the complete segmentation, regional and application tables, price curves, and the full set of vendor scorecards that underpin the scenarios summarized here, download the full report or contact PW Consulting’s industry team to schedule a tailored briefing. Our advisory work helps clients convert compliance timelines and market growth into durable operational capability and measurable ROI.
For detailed analysis of this topic, please visit the official page: Closed Caption Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com