

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Helicopter Crash-Resistant Seats Market at USD 1,650.45 Million in 2025, Set to Reach USD 2,331.65 Million by 2032 on a 5.06% CAGR (2026–2032)

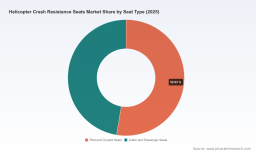
Helicopter Crash Resistance Seats Market — Strategic Imperatives for 2026
PW Consulting’s latest industry brief furnishes an evidence-based roadmap for executives, procurement leads, product managers and M&A teams confronting the evolving market for helicopter crash resistance seats. Using 2025 as the baseline and a dedicated forecast window from 2026 through 2032, our proprietary model projects the global market to expand at a compound annual growth rate (CAGR) of 5.06%. In plain terms, the market is projected to grow from an estimated USD 1,650.45 Million in 2025 to approximately USD 2,331.65 Million by 2032 — a trajectory that reflects both steady replacement cycles and emergent platform demand.
Helicopter Crash Resistance Seats Market
Why 2026 is a Pivotal Year
-
Regulatory inflection points: Ongoing certification demands (FAA 14 CFR §27.562, EASA CS-27.562 and military standards such as MIL‑STD‑1290) are raising the technical and documentation bar for seat manufacturers and integrators. Compliance is no longer a checkbox — it is a market differentiator that shortens procurement cycles for certified suppliers and lengthens them for newcomers.
Helicopter Crash Resistance Seats Market -
Aftermarket and retrofit momentum: Heightened safety requirements and lifecycle extension programs are increasing demand for certified retrofit solutions across legacy fleets. Supplemental Type Certificates (STCs) and type-acceptance tracks — demonstrated recently by certified upgrade programs — accelerate aftermarket monetization opportunities.
Helicopter Crash Resistance Seats Market -
Materials and supply pressure: Raw-material dynamics matter. Aluminum honeycomb core costs spiked (~15% in recent cycles) and composites adoption yields weight savings (industry estimates show ~25% weight reduction potential when compared with traditional constructions). These forces reshape cost structures, design choices and supplier relationships.
-
Consolidation vs. specialization: Market concentration metrics indicate that a handful of firms capture a material share of the addressable market, creating a dual landscape where tier-one integrators coexist with nimble STC specialists and component innovators.
What the PW Consulting Report Delivers (Operationally Focused)
-
Integrated market sizing and scenario forecasts (2026–2032) with sensitivity runs for material-price shocks, regulatory tightening and platform demand variability.
-
Competitor benchmarking and capability heatmaps — technology stacks, certification portfolios, program wins and aftermarket footprints — enabling side-by-side supplier selection and partnership screening.
-
Certification playbooks and program schedules for FAA/EASA/MIL standards, highlighting typical test campaigns, failure modes to preempt and realistic certification timelines aligned to product roadmaps.
-
Procurement and contracting templates tailored to OEMs, prime contractors and fleets — including pricing levers, performance-based warranties and retrofit/upgrade clauses that protect margin while accelerating deployment.
-
Supply-chain risk assessments with actionable mitigations: supplier diversification matrices, material hedging approaches, and nearshoring vs. offshore cost/lead-time tradeoffs.
-
M&A and partnership candidate shortlists with commercial fit scores and post-transaction integration checklist focused on tech transfer, certification retention, and cross-selling synergies.
-
Field-validated unit economics models and service-revenue playbooks for aftermarket consumables, maintenance, and field-support contracts.
Competitive Landscape — How the Leaders Are Positioned
The competitive topology for crash-resistant seats is characterized by firms that combine deep certification expertise, platform-specific integration knowledge and innovations in energy‑absorbing technologies. Our analysis focuses on several core players and the strategic takeaways from their recent moves.
-
Martin‑Baker Aircraft Co. Ltd. — A long-established specialist with strong credentials in military certification and energy-absorbing systems. Its military pedigree provides trusted access to defense programs where MIL‑STD compliance and historical performance weigh heavily in procurement decisions.
-
Safran Seats — A prime example of a supplier that spans both civil and military domains, leveraging type-certification knowledge (EASA/FAA) and OEM relationships to access civil retrofit and new‑build opportunities.
-
IPECO Holdings Ltd. — Focuses on modular, platform-tailored seating solutions (frangible pan, stroke mechanisms) for widely deployed helicopter models. Its modular approach shortens integration time and appeals to fleets seeking low‑disruption retrofits.
-
DART Aerospace — An aftermarket-oriented player with demonstrated capability to secure supplemental type certifications across multiple rotorcraft types. Recent certified STCs underscore the revenue potential within upgrade kits and mission‑specific assemblies.
-
SKYDEX Technologies Inc. — A materials and systems innovator supplying cellular composite energy absorbers. Its technology has been validated via defense contracts, evidencing a pathway for material‑centric entrants to scale through prime-system integration.
-
Gentex Corporation — Produces integrated crew seating systems that meet military crash standards, positioning it as a supplier where system-level integration and proven survivability records are critical.
Market concentration metrics point to a semi-consolidated arena: leading players command a notable share of commercial and defense procurements, but the available pockets of aftermarket, STC-driven upgrades and component specialization keep the market accessible to focused entrants. Recent developments such as multiple STC awards and defense validation contracts confirm that certification-driven wins materially alter supplier trajectories.
Strategic Recommendations for 2026 Decision‑Makers
Below are prioritized actions distilled from our analysis to guide corporate strategy through 2026 and into the forecast window.
-
Secure certification pathways early. Allocate budget and program management capacity to certification campaigns up front. Winning the certification race reduces time-to-market and creates entry barriers for competitors.
-
Pivot to material-led differentiation. Evaluate composites and advanced energy‑absorbing architectures to achieve weight and lifecycle advantages. Mitigate raw‑material price volatility through supplier contracts and dual-sourcing for aluminum honeycomb or equivalent absorbers.
-
Prioritize aftermarket playbooks. Design STC-friendly, low-disruption retrofit solutions and pursue focused STC campaigns on high-rotor-count platforms. Aftermarket capture can materially uplift margins vs. OEM new-build contracts.
-
Scale services and field support. Extend warranties with service packages, data-driven maintenance offers, and depot capabilities to monetize installed bases and create recurring revenue streams.
-
Use M&A selectively to close capability gaps. Target bolt-on buys for certification expertise, materials IP, or STC portfolios rather than broad horizontal consolidation — integration risk scales with complexity in aviation safety systems.
-
Build resilience into supply chains. Invest in inventory strategies, demand signal sharing with key raw-material suppliers, and near-term contracts to smooth cost and lead-time volatility.
-
Align product roadmaps to platform modernization timelines. Synchronize R&D milestones with prime contractor timelines and fleet upgrade windows to maximize win probability for both military modernization and civil renewal cycles.
How to Use This Report in Your 2026 Decision Cycle
-
Boards and C‑suite — validate capital allocation toward certification and aftermarket capabilities, and use the report’s scenario outputs to stress-test three‑year investment plans.
-
Business development — build target lists from the competitive mapping and use our STC and procurement playbooks to shorten sales cycles.
-
Product and engineering leadership — adopt our materials and test-failure analyses to prioritize design-for-certification and weight-efficiency measures that improve win rates.
-
M&A teams — use the M&A shortlists and valuation frameworks to prioritize assets that deliver immediate certification leverage or fill technological white spaces.
Why PW Consulting’s Analysis Is Actionable
Our approach combines longitudinal market-tracking (historical window 2020–2025), exhaustive primary interviews with OEMs, regulatory authorities and tier suppliers, and a proprietary demand model that reconciles platform build rates, fleet retirement curves and aftermarket retrofit adoption. The report includes scenario stress-tests that quantify revenue and margin outcomes under alternative regulatory and material‑cost evolutions — the very inputs executives need to finalize 2026 capex, R&D and M&A decisions.
Note: This article highlights the report’s strategic takeaways and key market dynamics. Detailed segment tables (regional splits, application-level percentages, and granular platform-by-platform forecasts) are intentionally withheld in this release to preserve the actionable intelligence within the full report. Access to the complete dataset, Excel model, and supplier scorecards is available from PW Consulting’s report portal.
For executives preparing procurement strategies, R&D roadmaps, or transaction diligences in 2026, this report is designed to be both a decision accelerator and a tactical manual. Contact PW Consulting to obtain the full Helicopter Crash Resistance Seats Market report, schedule a briefing with our senior analysts, or commission a tailored workshop using your company’s base cases and constraints.
For detailed analysis of this topic, please visit the official page: Helicopter Crash Resistance Seats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com