

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Robot Joint Precision Reducers Market to Expand at a 15.81% CAGR Through 2032

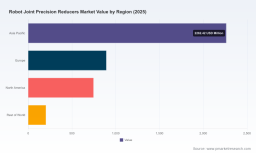
Robot Joint Precision Reducers Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
The global Robot Joint Precision Reducers market stands at a pivotal inflection point. Our latest PW Consulting market study (base year 2025, forecast 2026–2032) models the sector as a rapidly expanding, yet concentrated industrial ecosystem. The market crossed approximately USD 4,102.5 Million in 2025 and, under our central case, is forecast to approach USD 11,462.3 Million by 2032 at a compound annual growth rate (CAGR) of 15.81% for the 2026–2032 period. This trajectory reflects accelerating automation demand across industrial, humanoid, service and collaborative robot segments, tighter performance tolerances required by Industry 4.0 initiatives, and renewed investment in domestic production capacity among established manufacturers.
Robot Joint Precision Reducers Market
Why this report matters to 2026 corporate strategy
- Timing: 2026 is a make-or-break year for teams defining supplier roadmaps, capacity commitments, and differentiated automation strategies. Suppliers that lock in validated design wins this year will capture outsized lifetime value as volume ramps in the late 2020s.
- Risk management: Precision reducer supply is sensitive to raw-material and manufacturing bottlenecks. Our study quantifies the cost and lead-time exposure drivers that should be integrated into procurement and product planning cycles for 2026 and beyond.
- Partner selection: The market’s high concentration among top-tier reducer suppliers means OEM selection decisions have strategic consequences for product differentiation, aftersales, and service margin. The report provides the diagnostic framework to choose partners aligned to specific product roadmaps (high-torque, low-backlash, lightweight, compact).
- M&A and investment prioritization: For private equity and corporate development teams, the combination of robust top-line growth and clear scale advantages suggests targeted roll-up or vertical-integration plays. The report profiles where value can be captured — from actuator integration to localised manufacturing and aftermarket services.
What PW Consulting’s report delivers (practical, actionable content)
We built this research around executive questions that shape 2026 strategy. The product is intentionally operational and transaction-ready:
Robot Joint Precision Reducers Market
- Top‑down market sizing and validated bottom‑up checks for 2020–2025 historicals and a 2026–2032 forecast run by scenario (base, downside, upside).
- Demand-driver analytics that map robotics application trends to reducer performance requirements (precision, torque density, backlash, life-cycle cost), enabling product roadmap prioritisation.
- Supply‑chain stress tests and cost pass-through modelling (including sensitivity to raw material price shocks, labour cost differentials, and logistics constraints).
- Commercial due diligence templates for OEM/supplier partnerships, including KPIs for qualification, test cycles, and service-level agreements tuned to reducer life and mean-time-between-failure (MTBF) dynamics.
- Competitive intelligence dossiers and capability matrices for the leading reducer manufacturers, including manufacturing footprints, product families, and go-to-market positioning.
- M&A heatmaps and valuation scenarios for targets across the precision-reducer stack (component suppliers, actuator integrators, service & repair specialists).
- Regulatory and standards review relevant to robot joint safety and precision, with recommended compliance priorities for 2026 implementations.
Market structure and concentration — what leaders should infer
The Robot Joint Precision Reducers market exhibits meaningful concentration: our concentration metrics indicate that the top three suppliers account for a strong majority of industry volumes, with the top five controlling an even larger share. This structure creates both advantages and constraints for buyers and investors:
Robot Joint Precision Reducers Market
- Advantage: Scale incumbents offer validated quality, broad aftermarket support, and engineering depth — critical where uptime and repeatability are non-negotiable.
- Constraint: High share held by a few suppliers raises switching costs and creates leverage in pricing negotiations, particularly for specialized high-precision designs.
- Strategic implication: Mid-sized OEMs should balance reliance on tier‑one reducers with strategic dual-sourcing or co-development agreements to mitigate supply shocks and preserve negotiating leverage.
Competitive landscape: core players and what they signal for 2026
Our competitive analysis focuses on incumbent strengths, product differentiation, and recent strategic moves. Below are the high-level profiles and implications for partners and rivals:
- Nabtesco Corporation (Tokyo, Japan) — Recognized globally for RV cycloidal reducers that emphasize high torque, rigidity and low backlash. Recent product introductions and capacity investments underline a strategy to capture semiconductor, automotive and humanoid robot demand. For buyers, Nabtesco represents a de‑risked choice where performance margin is prioritized over unit cost.
- Harmonic Drive Systems Inc. (Tokyo, Japan) — A pioneer in strain‑wave harmonic drives, noted for zero‑backlash, compact high‑precision gearings. Product line expansions targeting smaller joints and new FPA series releases signal a push into lighter‑weight and collaborative robot niches, creating an opening for partners targeting space- or weight-constrained designs.
- Sumitomo Heavy Industries, Ltd. (Tokyo, Japan) — Offers high‑precision cycloidal variants engineered for speed, low vibration and efficiency. Their positioning is attractive to high-cycle industrial automation customers seeking lifecycle efficiency.
- Wittenstein SE (Igersheim, Germany) — European engineering leader in planetary and cycloidal reducers, with strengths in premium automation and demanding motion-control applications; an important supplier for customers requiring tight integration with European automation ecosystems.
- SPINEA s.r.o. (Haniska, Slovakia) — Specialist maker of TwinSpin cycloidal gears and integrated actuators, emphasizing zero‑backlash architectures and bearing integration. Their catalog refresh shows capability-led product development attractive to robotics integrators.
- Chinese manufacturers (Leaderdrive, Nidec‑Shimpo, Zhejiang Laifual, and several domestic producers) — Represent a fast‑maturing cohort focused on cost-competitive harmonic and cycloidal variants and scale manufacturing. Recent trade‑show visibility and expanded catalogues indicate an expanding global role, especially for high-volume applications.
Collectively, these firms demonstrate two evolving competitive vectors: (a) premium differentiation through engineering (zero-backlash, torque density, integrated actuators), and (b) scale‑driven cost plays for high-volume robotics applications. Suppliers that bridge both vectors — delivering engineered performance at scale — will redefine market share dynamics toward the end of this decade.
Supply‑chain dynamics & cost headwinds
Raw-material and capacity dynamics are immediate levers affecting 2026 outcomes. Key observations:
- Steel pricing and availability: The sector has seen cyclic steel-price pressure in early 2026, increasing production cost volatility for precision gear manufacturers. Buyers should expect periodic margin squeeze unless suppliers and OEMs negotiate indexed pass-through mechanisms or adopt alternative material/process options.
- Capacity expansion by incumbents: Major Japanese manufacturers are investing in domestic capacity expansion to support semiconductor, automotive and humanoid robot demand. This reduces single-source risk for buyers focused on high‑precision requirements but may tighten supply for smaller local providers.
- Localization and lead times: As automation customers demand shorter lead times and tighter service-levels, manufacturers are moving to localised manufacturing and repair centres — a trend that has implications for total landed cost and post‑sales support models.
Strategic playbook for 2026
Based on our analysis, leadership teams should prioritize the following actions this year:
- Fast-track supplier qualification matrices: Define test protocols that map reducer performance metrics to final application tolerances. Prioritize on‑robot validation where possible to collapse qualification timelines.
- Hedge procurement exposure: Implement staged contract frameworks that combine volume-based pricing with contingency capacity options and indexed material adjustments.
- Invest in modularization: Where product architecture permits, design for modular actuator‑reducer interfaces to enable supplier substitution without extensive redesign.
- Scan for strategic acquisitions: Target service networks or actuator integration players to capture aftermarket margins and lock in installed base economics.
- Adopt a two-track sourcing model: Combine a high-performance primary supplier for mission-critical axes with a cost-optimized secondary supplier for non-critical axes or high-volume applications.
Report access & the “trailer” approach
This briefing is intended to surface the strategic conclusions and operational priorities from PW Consulting’s full Robot Joint Precision Reducers Market Report. To preserve the commercial value of our proprietary segmentation modeling and subsegment-level forecasts, detailed regional, type and application splits are intentionally reserved for the full report and online dashboard. Those datasets include drill-downs for combination scenarios, supplier share at the product-family level, and model-based demand cascades that support procurement and M&A valuation work.
How to engage with PW Consulting for 2026 strategy
- Request a bespoke executive briefing to walk through scenario-specific implications for your product lines or procurement portfolio.
- Commission a supplier due-diligence addendum to evaluate potential partners against the report’s capability matrices and stress-test their factory-level resilience.
- Engage our transaction team for target-screening and valuation modeling informed by the market’s growth profile and concentration dynamics.
Contact PW Consulting to schedule a confidential walkthrough of the full report and to obtain the proprietary data tables and interactive dashboards that underpin the findings summarized here. For executives preparing budgets, supplier strategies, or M&A pipelines in 2026, this study is designed to convert market insight into executable advantage.
For detailed analysis of this topic, please visit the official page: Robot Joint Precision Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com