

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steering Auxiliary Lamp Market — USD 1,400.0 Million in 2025, Forecast to Hit USD 2,167.3 Million by 2032 at a 6.45% CAGR

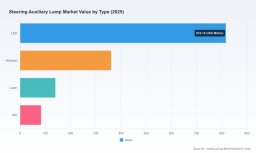
Steering Auxiliary Lamp Market — Strategic Imperatives for 2026
As automotive OEMs, tier suppliers, and aftermarket specialists plan capital allocation for 2026, the Steering Auxiliary Lamp market presents a clear, actionable growth narrative — but one that requires disciplined, data-driven choices. PW Consulting’s latest market research, built on a 2020–2025 historical foundation with a base year of 2025 and a 2026–2032 forecast horizon, shows a structurally expanding market at a compound annual growth rate (CAGR) of 6.45%. In monetary terms, the global market expanded from under USD 900 Million at the start of the decade to approximately USD 1.4 billion in 2025, with a projected climb to roughly USD 2.17 billion by 2032. This trajectory signals persistent demand for improved visibility solutions closely tied to vehicle safety, electrification, and evolving regulatory expectations.
Steering Auxiliary Lamp Market
Why this market matters for 2026 decision-making
-
Timing of investments: With steady mid-single-digit CAGR through 2032, 2026 is a strategic inflection point for firms that need to choose between scaling product families (LED, laser, adaptive systems) or consolidating niche performance positions (off-road, commercial fleets). The market’s predictable growth creates windows for both organic R&D and targeted M&A that can be executed with measurable payback horizons.
Steering Auxiliary Lamp Market -
Supply-chain sensitivity: Manufacturing economics are concentrated in lens and housing materials. Our supply-model sensitivity highlights that polycarbonate and allied plastics represent a dominant share of manufacturing operating expense; volatility or constraints in these inputs materially affect margin profiles and pricing strategies.
Steering Auxiliary Lamp Market -
Regulatory posture and product design: Active safety standards and vehicle lighting regulations in major markets already constrain auxiliary-lamp mounting, aiming, and luminous intensities. Compliance is non-negotiable — both to access OEM channels and to limit aftermarket liability — and product roadmaps must embed compliance engineering early in 2026 development cycles.
What PW Consulting’s report contains — practical, operational intelligence
-
Market sizing and scenario forecasts (2020–2032) with base-year calibration and seven-year outlooks under multiple macro scenarios.
-
Demand-driver decomposition linking vehicle production, electrification rates, ADAS penetration, and aftermarket replacement cycles to lamp adoption timelines.
-
Supply-side mapping: BOM-level cost models, material exposure (including plastics), contract-manufacturing dynamics, and capacity risk matrices.
-
Regulation and homologation playbook: practical checklists and engineering guards for FMVSS-style requirements and jurisdictional variations that impact fitment, aiming, and marketing claims.
-
Competitive landscape: qualitative and quantitative benchmarking across leading OEM suppliers and specialty brands, including capability heatmaps, route-to-market archetypes, and partnership templates.
-
Commercial toolkit: pricing models, margin recovery strategies, aftermarket vs OEM go-to-market decision frameworks, and distributor/channel tactics for 2026 launches.
-
M&A and partnership screening: shortlists of “acquirer-friendly” assets, integration targets, and valuation sensitivities tailored to strategic buyers and private-equity sponsors.
-
Playbooks for technology choices (LED vs laser vs hybrid optics), including engineering trade-offs, production complexity, and expected lifecycle cost implications.
Competitive landscape — who to watch and why
The market shows a moderate level of concentration: the top three firms capture a meaningful but not overwhelming share of industry revenues, while the top five extend that dominance. This creates a dual-layer opportunity: scale advantages for incumbents and nimble niches for specialty players. Key firms profiled in our study illustrate the competitive archetypes:
-
HELLA GmbH & Co. KGaA (Lippstadt, Germany): A full-spectrum lighting systems provider with strong capabilities in dynamic steering-integrated auxiliary lamps and recent product introductions emphasizing high-lumen LED auxiliary series. HELLA represents the incumbent platform supplier archetype — deep OEM relationships, broad product breadth, and continuous catalog refreshes to sustain aftermarket traction.
-
OSRAM GmbH (Munich, Germany): A technology-forward supplier known for high-performance LED and halogen solutions. OSRAM’s strength lies in component-level innovation and scalability into both OEM and aftermarket channels.
-
Koninklijke Philips N.V. (Amsterdam, Netherlands): Offers branded automotive auxiliary lighting with strong aftermarket recognition and catalog-driven distribution strategies that complement OEM-oriented portfolios.
-
Koito Manufacturing Co., Ltd. (Tokyo, Japan): A major OEM-focused headlamp and auxiliary systems supplier with integration experience for steering-responsive cornering lighting — a strategic partner for platform-level lighting programs.
-
Valeo S.A. (Paris, France): Positions itself on intelligent and adaptive lighting, including auxiliary solutions tied to vehicle assistance systems and comfort features.
-
Specialists (PIAA, KC HiLiTES, Rigid Industries): These players target performance- and off-road segments, offering differentiated beam patterns and ruggedized solutions that capture aftermarket enthusiasts and commercial/off-road fleets.
Recent strategic moves to monitor
-
HELLA’s mid-2024 and subsequent catalog activity refreshed its auxiliary LED product stacks, signaling continued investment in high-lumen, modular designs that can be adapted across vehicle classes.
-
Philips’ 2024–2025 catalog updates reflect a parallel push to combine branded aftermarket offerings with OEM-aligned technologies, an approach that pressures mid-tier suppliers to clarify channel strategies.
Market dynamics and risk vectors
-
Regulatory friction: Active regulations that govern auxiliary lamp mounting and aiming create both barriers and competitive moats. Our compliance scenarios show that firms that factor homologation timelines into product development reduce time-to-market slippage and litigation risk.
-
Material exposure: Polycarbonate and related plastics dominate lamp lens and housing costs. PW Consulting’s sensitivity analysis shows that material cost inflation or supply interruptions can compress gross margins rapidly unless firms implement hedging, alternative materials, or supplier diversification in 2026.
-
Technology substitution: LED has already established a clear performance and efficiency advantage, but laser and hybrid approaches create premium niches. The strategic decision is not binary; leading firms pursue modular architectures that enable incremental upgrades without full platform requalification.
-
Channel bifurcation: OEM programs reward scale and engineering integration; the aftermarket rewards brand strength and distribution reach. 2026 plans must explicitly allocate resources and KPIs to avoid channel conflict while maximizing aggregate lifetime revenue per platform.
Actionable strategic recommendations for 2026
-
Prioritize modularity in product architecture. Design auxiliary lamps as upgradeable modules to ease OEM integration and aftermarket retrofits while containing homologation cycles and production complexity.
-
Implement a materials risk program. Lock in multi-year supply agreements for polycarbonate (or validated alternatives), and evaluate nearshoring or dual-sourcing to reduce lead-time risk and input-cost exposure.
-
Calibrate R&D mix toward adaptive and sensor-integrated auxiliary solutions that support ADAS-era use cases (e.g., steering-responsive illumination linked to camera/LiDAR inputs).
-
Segment routes-to-market: maintain OEM partnerships for platform-level revenue while building branded aftermarket propositions — but deploy distinct product families and channel economics to prevent internal cannibalization.
-
Use M&A selectively to acquire gap technologies or capacity rather than market share alone. Targets that add proprietary optics, thermal management, or production scale can accelerate time-to-market and margin improvement.
Conclusion — the decision point for 2026
PW Consulting’s Steering Auxiliary Lamp market analysis delivers both high-level certainty (a mid-single-digit CAGR and a clear enlargement of total addressable market value through 2032) and actionable nuance (material exposure, regulatory constraints, and a mixed competitive structure that favors both large integrators and focused specialists). For executives planning 2026 budgets, the imperative is simple: move beyond product-feature speculation and implement integrated strategies across sourcing, compliance, and channel design. Our report provides the tactical playbooks, scenario models, and competitor intelligence to convert the macro growth opportunity into measurable shareholder value.
Where to get the full data and drilldowns
This release intentionally highlights core strategic takeaways while reserving the detailed regional, type- and application-level splits, pricing curves, and model-level adoption timelines for the full report. For access to the complete dataset, scenario models, and executable go-to-market playbooks, please visit the PW Consulting report landing page or contact our industry engagement team for a briefing.
For detailed analysis of this topic, please visit the official page: Steering Auxiliary Lamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com