

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Coco Amine Ethoxylate Market to Grow at a 5.5% CAGR in 2026–2032 Forecast

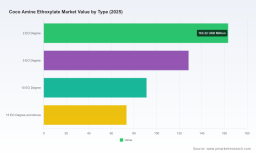
Coco Amine Ethoxylate Market — Strategic Outlook for 2026: Why this PW Consulting Report Matters to Decision-Makers
PW Consulting’s Coco Amine Ethoxylate Market study (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with an actionable, forward-looking playbook for decisions that will determine competitiveness through 2026 and beyond. The global market reached approximately USD 456.0 Million in 2025 and is modeled to grow at a 5.5% CAGR through the 2026–2032 forecast window, arriving at an estimated USD 663.3 Million by 2032. These headline dynamics mask important micro-shifts—raw material volatility, regulatory friction, and supplier repositioning—that make 2026 a pivotal year for procurement, M&A, and product strategy. This release summarizes the report’s strategic value for corporate leaders while preserving the full segmented intelligence for readers who access the complete study.
Coco Amine Ethoxylate Market
Why 2026 Is a Decision Point
-
Transition from cost-centred sourcing to resilience-centred procurement: Recent feedstock price swings and transport/regulatory complexities require more than spot buying—firms must reconfigure supply contracts, inventory strategies, and supplier portfolios.
Coco Amine Ethoxylate Market -
Product portfolio pressure: End-use sectors are shifting formulation priorities (performance, biodegradability, and regulatory compliance). Companies that re-prioritize R&D and launch differentiated grades in 2026 will capture outsized share in the next cycle.
Coco Amine Ethoxylate Market -
Consolidation window: Market concentration metrics show an intermediate level of supplier concentration (CR3 ≈ 42.5%, CR5 ≈ 58.7%), indicating room for strategic consolidation and bolt-on acquisitions—especially by regional players aiming to scale into formulation and logistics capabilities.
Key Drivers and Market Dynamics (operational lens)
-
Demand-side momentum: Growth is underpinned by agricultural adjuvants, industrial surfactants, and specialty formulation demand across textiles, home care, and personal care. The pace of growth reflects both volume expansion and premiumization of mid-to-high EO grades in selected formulations.
-
Feedstock volatility: Coconut oil—the primary upstream feedstock for coco amine synthesis—experienced significant movement in 2025 and into early 2026. Global averages and regional spikes during 2025 highlight price risk that materially impacts gross margins for ethoxylate producers and formulators.
-
Logistics & transport risk: Coco amine ethoxylates are commonly classified under transport regulations as Amines, Liquid, Corrosive, N.O.S. (UN2735, Class 8), with attendant handling and packaging requirements that add complexity and cost to cross-border trade and just-in-time supply models.
-
Regulatory clarity but compliance burden: While industry-aligned safety data indicates that coco amine ethoxylates do not meet PBT or vPvB criteria under REACH, evolving environmental disclosure and downstream reporting obligations continue to raise compliance costs and documentation burdens for exporters and formulators targeting regulated markets.
Supply-Side Structure and Competitive Implications
The market shows mid-tier concentration—enough scale among leading players to influence supply dynamics, but with significant global fragmentation that favors agile regional suppliers. For strategic planning, leaders must balance partnership with established multinationals against opportunities with specialized regional producers and distributors.
-
Nouryon (Netherlands) — Global technology and brand strength in ethoxylated amines; established product families for crop protection and emulsification. Suited for partners seeking proven, specification-driven supply and global technical support ( https://www.nouryon.com).
-
Stepan Company (United States) — Deep agricultural adjuvant know-how with established ethoxylate SKUs used in formulations; attractive for formulators prioritizing agricultural channel access ( https://www.stepan.com).
-
Harcros Chemicals & Colonial Chemical (United States) — Broad portfolio support for industrial and metalworking applications; strength in customization and technical service for B2B formulators ( https://www.harcros.com; https://colonialchem.com).
-
Regional manufacturers and exporters (India, China, etc.) — Companies such as Matangi Industries, Tristar Intermediates, Shree Vallabh Chemical, and multiple Indian exporters offer scale and cost-competitive supply for commodity grades; suitable for high-volume formulators and distributors seeking price flexibility (see respective corporate sites).
-
Specialist distributors in North America — Silver Fern Chemical and Rock Chemicals offer distribution and logistical solutions that reduce lead time and regulatory handling risk for local manufacturers.
For buyers and strategists, this supplier mix implies three actionable stances: (1) lock strategic supply with tier-1 players for critical grades, (2) maintain agile sourcing from regional producers for commodity grades to preserve margin, and (3) deepen distributor relationships to shorten cash-to-product cycles in major end-use geographies.
Report Contents — What Executives Will Find (practical, but non-disclosing)
-
Integrated market model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario variants aligned to feedstock price trajectories and regulatory shocks.
-
Supplier benchmarking toolkit: capability maps, quality and regulatory readiness scoring, and playbooks for supplier segmentation across strategic, preferred, and tactical tiers.
-
Commercial playbook for 2026 procurement and pricing: hedging frameworks, contract clause templates, and inventory optimization levers that protect margin under price volatility.
-
Technical & product guidance: recommended R&D focus areas, grade-selection matrices for formulators, and performance vs. cost trade-off analysis for EO-degree strategies.
-
Regulatory and transport dossier: compliance checklists for global trade, labeling and SDS best practices, and an assessment of likely near-term regulatory changes.
-
M&A and partnership screening: target profiles, valuation sensitivities, and integration playbooks tailored to players seeking scale or capability expansion.
-
Risk heatmaps and a prioritized 18-month action plan for procurement, supply continuity, and go-to-market moves.
Note: the full report contains detailed regional and application breakdowns, quantitative supplier shares, and proprietary price-deck scenarios. This executive summary intentionally omits those granular segment values to preserve the strategic advantage available via the complete intelligence package.
Practical Strategic Recommendations for 2026
-
Embed feedstock scenario planning into budgets: create at least three procurement scenarios tied to coconut oil price bands and test margins, capex, and working capital across those.
-
Negotiate hybrid contracts: mix fixed-volume agreements for critical grades with indexed, flexible arrangements for commodity grades to balance cost and continuity.
-
Accelerate formulation differentiation: invest in mid-EO innovation and eco-design where premiumization is feasible—this reduces commoditization risk and creates margin protection.
-
Strengthen transport & SDS capability: standardize packaging and emergency response processes to reduce trans-shipment friction and insurance costs for Class 8 shipments.
-
Pursue selective consolidation: target bolt-ons that add technical capability, local regulatory access, or logistics capacity rather than broad volume buys.
-
Operationalize supplier scorecards: include ESG, regulatory-readiness, and feedstock sourcing transparency as mandatory KPIs for all strategic suppliers.
How PW Consulting’s Study Supports Board-Level Decisions
Boards and executive teams will find the report useful as a decision-grade input: it translates macro demand growth (5.5% CAGR in the forecast window) into concrete P&L, capex, and procurement scenarios; it prioritizes investments that preserve near-term margin while positioning for mid-cycle value capture; and it codifies a repeatable approach to supplier and product portfolio optimization. The report’s combination of market modeling, supplier diagnostics, and transaction playbooks is designed to fast-track 90-day action plans and support 12–24 month roadmaps for companies active across the coco amine ethoxylate value chain.
Next Steps
-
Download the full report for access to granular regional and application-level forecasts, supplier market shares, and the complete scenario price decks.
-
Schedule a strategic briefing with PW Consulting to translate the report’s findings into a tailored 90-day implementation roadmap for your organization.
In 2026, the interplay between feedstock volatility, compliance obligations, and product premiumization will determine winners and laggards. PW Consulting’s Coco Amine Ethoxylate Market study provides the quantitative foundation and pragmatic execution tools to convert market growth into sustainable commercial advantage—while the full report supplies the proprietary segmentation and supplier data necessary to operationalize those strategies.
For detailed analysis of this topic, please visit the official page: Coco Amine Ethoxylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com