

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sports Fabric Market Tops USD 48.78 Billion in 2025 — Poised for 6.02% CAGR Through 2032, Led by Asia Pacific

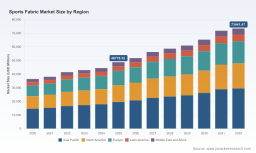
Sports Fabric Market 2026: Strategic Imperatives from PW Consulting’s Market Study
Executive snapshot
PW Consulting’s latest Sports Fabric Market report (base year 2025) synthesizes five years of historical performance and a forward-looking forecast to 2032. The global market reached approximately USD 48,778 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 6.02% over the 2026–2032 forecast period, reaching an expected market scale in the low-to-mid tens of billions by 2032. That steady, mid-single-digit growth masks material shifts in technology, sourcing economics, regulation and buyer behavior that will determine winners and laggards through 2026 and beyond.
Sports Fabric Market
Why this matters for 2026 decision-makers
- Investment cycles: Capital allocation to fibre innovation, recycling infrastructure and performance R&D needs to be timed to capture the next wave of product differentiation without oversupplying legacy commodity lines.
- Regulatory compliance: New product design, certification and traceability obligations will affect cost-to-market and retail go-to-market plans beginning in 2026.
- Procurement and pricing: Feedstock dynamics and trade measures are creating a new volatility regime; procurement strategies that were sufficient in 2022–24 will not protect margin in 2026.
- Commercial positioning: Brands and suppliers that can credibly combine performance with verifiable sustainability at scale will command premium share of growth in activewear, footwear and adjunct sports applications.
What the report delivers (practical takeaways)
Built for C-suite and functional leaders, the report translates market intelligence into executable actions. It includes:
Sports Fabric Market
- Top-down market sizing and scenario modeling through 2032, with sensitivity tests for feedstock shocks, tariff escalations and accelerated circularity adoption.
- Demand-driver analysis by product type and end-application, with use-case oriented commercial playbooks for performance apparel, footwear and accessories.
- Supply-chain maps and supplier scorecards that rank technical capability, sustainability readiness, capacity risk and margin profile.
- Regulatory impact assessment and an implementation checklist for compliance with emerging EU rules, digital product passports and inventory-disposal bans.
- Innovation radar highlighting near-commercial technologies (bio-based polymers, advanced spandex variants, antimicrobial/thermoregulating finishes) and licensing/partnering options.
- Actionable M&A and CAPEX frameworks identifying where consolidation, joint ventures or captive capacity will create defensible advantage.
Note: this release follows a “trailer” approach — the report teases strategic direction and methodology but intentionally withholds granular segment-level figures (regional splits, application and fiber-type-by-value tables). Full segment detail and interactive models are available via the report landing page.
Sports Fabric Market
Competitive landscape — who to watch and why
The sports fabric space remains fragmented: the top three suppliers account for under one-fifth of market revenue and the top five for roughly one-quarter, underscoring persistent opportunities for scale-driven consolidation and niche differentiation.
- INVISTA (Koch Industries) — Dominant in engineered spandex and branded performance fibers (LYCRA® family). Strengths: deep brand licensing, vertical relationships with performance apparel OEMs and proven durability and stretch technologies. Strategic focus should be defending premium performance segments while scaling circular offerings.
- Toray Industries — Technical polyester/nylon leader with strong R&D in lightweight and quick-dry polyester constructions. Toray’s edge is in materials-to-product integration and working closely with brand R&D teams to optimize fabric-engineered solutions.
- Teijin Limited — Established supplier of high-tenacity polyester and next-generation stretch fabrics. Teijin’s recent product pushes indicate a focus on multi-dimensional performance (3D-structured stretch, rapid drying) and B2B collaborations.
- Hyosung TNC — Global leader in spandex (creora®) and an early mover on recycled polyester yarns. Hyosung’s capability to marry high-stretch chemistry with recycled feedstocks positions it well for demand that prizes both performance and sustainability.
- Asahi Kasei — Known for functional knits and balanced performance across comfort, elasticity and moisture management, making it a reliable partner for outdoor and athleisure segments.
- DuPont de Nemours — Leveraging bio-based polymer platforms and new Sorona® Revive launches, DuPont aims to capture growth at the intersection of performance and sustainable narratives.
- Milliken & Company — Specializes in performance finishes and coated textiles; differentiation comes through treatment technologies (antimicrobial, moisture control) that extend product life and wearer comfort.
- W.L. Gore & Associates — GORE-TEX® membranes remain a go-to in waterproof/breathable outdoor sportswear; Gore’s franchise is less volume-driven and more margin-anchored through performance licensing.
- Unifi, Inc. — With REPREVE® recycled polyester yarns, Unifi is central to the circularity story, converting post-consumer plastics to performance yarns at scale — an increasingly important procurement lever for brands.
- Glen Raven & Schoeller — Niche leaders in durable and highly functional textiles, respectively; these companies are strategic partners for brands seeking differentiated material properties or technical finishes.
Recent industry moves reinforce strategic themes: bio-based and recycled launches (e.g., Sorona® Revive), novel stretch constructions and integrated antimicrobial/thermoregulation collaborations. These developments aren’t incremental — they change specification conversations between brands and suppliers.
Market dynamics shaping 2026 strategy
- Technology convergence: Four-way stretch, engineered 3D crimps, antimicrobial/thermoregulation finishes and membrane laminates are integrating into single SKUs. R&D agendas must prioritize multi-functionality while protecting margin.
- Feedstock economics: Polyester-based supply retains a structural cost edge versus natural fibers, supporting competitiveness of synthetic-based performance textiles. However, procurement teams must plan for periodic volatility and carbon-cost overlays.
- Regulatory inflection: EU Ecodesign-style rules, digital product passport requirements and bans on destruction of unsold textiles will materially affect product design, inventory policy and reverse logistics starting in 2026.
- Trade and carbon risk: Tariff shifts and carbon border adjustment mechanisms are raising the cost-sensitivity of polyester-heavy supply chains, prompting nearshoring and low-carbon feedstock sourcing as viable hedges.
- Market fragmentation: Low concentration means acquisition and selective partnerships are high-return levers for companies seeking scale or technical exclusivity.
Strategic recommendations for executives in 2026
- Adopt a staged materials roadmap — Prioritize investments that enable both performance and recyclability. Define “acceptable” recycled or bio-based blends for each price point and application, and lock supplier development agreements accordingly.
- Operationalize traceability — Implement digital product passport pilots for priority SKUs to ensure compliance and to unlock premium retail positioning; make traceability a supplier selection criterion.
- Revise inventory and disposal practices — Design inventory governance to avoid the downstream costs of disposal bans and to capture value through refurbishment, resale and take-back programmes.
- Diversify feedstock exposure — Combine long-term contracts, regional sourcing and strategic nearshoring to mitigate tariff and carbon border risks while smoothing margin volatility.
- Close capability gaps through partnerships — Where internal R&D is insufficient, prioritize co-development agreements or licensing with material innovators rather than building high-cost internal capabilities from scratch.
- Embed sustainability into pricing and procurement — Use validated sustainability attributes as a commercial lever to recapture margin, not merely as a compliance checkbox.
- Targeted M&A and strategic minority investments — Acquire upstream capabilities (recycling, melt-to-fiber) or take minority stakes in high-potential performance fiber startups to secure preferential access to next-generation feedstocks.
Conclusion — navigating to competitive advantage
For organizations making 2026 decisions, the sports fabric market represents both continuity and disruption: steady market expansion at a roughly 6% CAGR coupled with transformative changes in regulation, feedstock economics and material science. Winning strategies will be those that marry product performance with verifiable sustainability, rewire procurement and inventory practices for a more constrained regulatory landscape, and partner selectively to accelerate time-to-market.
PW Consulting’s full Sports Fabric Market report contains the detailed segment-level forecasts, regional analysis, supplier benchmarking tables and downloadable financial models that underpin the recommendations summarized here. We have intentionally withheld granular segment figures in this release; please visit our report page to access the complete dataset, interactive models and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Sports Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com