

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High Dielectric Plastic Films Market Poised to Grow at a 6.48% CAGR Through 2032

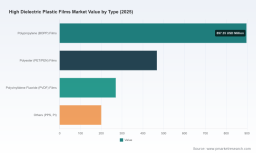
High Dielectric Plastic Films Market: A 2026 Strategic Briefing
As demand for higher-performance dielectrics accelerates across power electronics, energy storage and electrified mobility, PW Consulting’s new market study on High Dielectric Plastic Films arrives as a decision-grade briefing for boards, strategy teams and procurement leaders planning for 2026. The market is on a steady expansion path — our base-year analysis (2025) and forecast through 2032 combine historical trend analysis with stress-tested scenarios to translate technical nuance into commercial action. This release is a “trailer” of our full report: we surface the critical implications and actionable levers while directing readers to the source for full segmentation tables, vendor scorecards and proprietary unit-economics models.
High Dielectric Plastic Films Market
Market snapshot: trajectory and near-term sizing
Using 2025 as the base year and a forecast horizon of 2026–2032, the high dielectric plastic films market exhibits a mid-single-digit compounded annual growth rate (CAGR) of approximately 6.48%. The market has demonstrated durable expansion through 2020–2025 and is projected to continue that momentum into the latter half of the decade under our base-case scenario. For executives, the headline takeaway is simple: demand growth is broad-based and persistent enough to justify near-term capacity investments, but not so explosive as to remove the premium on disciplined capital allocation and supplier selection.
High Dielectric Plastic Films Market
Why 2026 is a strategic inflection point
- Regulatory and material risk converge. European chemical restrictions and international standards are shifting the compliance burden for dielectric films. Notably, regulatory action on persistent fluorinated substances has created conditional paths for essential electrical uses — a factor that complicates long-term material sourcing and approval timelines for product roadmaps.
- Cost pressure from upstream inputs. Fluoropolymer resin price inflation and freight surcharges have introduced fresh margin volatility. Our industry monitoring shows meaningful YoY increases in key resin inputs and a notable uptick in ocean freight costs for hazardous-classified polymer shipments — both of which blunt the effectiveness of traditional spot-buy strategies.
- Trade policy and market access. Tariff overlays for high-tech fluoropolymers have raised the landed cost of imports into certain markets since 2025. Corporates must now weigh nearshoring, tariff engineering and bonded-warehouse strategies when designing distribution footprints.
- Certification as a market gate. Technical certifications (for example, requirements tied to higher permittivity films) are becoming non-negotiable for scaled commercial deployment. Certification timelines should be incorporated as deterministic inputs in any 2026 product launch plan.
Contents and practical deliverables in the full report
Our full study is designed for immediate operational use. Highlights include:
High Dielectric Plastic Films Market
- Market model with historicals (2020–2025) and forecasts (2026–2032) built on a transparent, audit-ready workbook.
- Scenario suite (base, constrained-supply, accelerated-EV adoption) with sensitivity analyses for resin pricing, freight surcharges and tariff outcomes.
- Supplier-level commercial dossiers: manufacturing footprint maps, capacity timelines, technology IP positions and a proprietary vendor-risk scoring system suitable for supplier rationalization or dual-sourcing decisions.
- Buy-side playbooks covering hedging approaches for fluoropolymer resins, contract language to manage pass-throughs, and sample bilateral MOU templates for capacity reservation.
- M&A and partnership screening matrix highlighting strategic targets and integration pitfalls, supported by near-term synergy estimates and regulatory risk overlays.
- Deployment-ready product development roadmaps: material substitution scenarios, certification path dependencies and BOM (bill-of-materials) change-impact analyses.
Note: detailed split tables by region, film type and application segments — including company-level revenues by segment — are intentionally withheld in this briefing and are available only in the full report package.
Competitive landscape: who is shaping the market
The market displays moderate concentration. The top-three players account for a significant share of capacity, while the top-five further increase concentration, signaling a supplier base with meaningful scale advantages but room for niche specialists. Several incumbent and specialty firms are setting the competitive tempo:
- DuPont (USA) — Leveraging established product brands and material science capabilities, DuPont has recently invested in expanding capacity for its high-dielectric polyimide variants to meet rising electronics demand. Their scale and customer relationships make them a preferred partner for OEMs seeking supply continuity and specification compliance.
- Toray Industries (Japan) — Toray’s recent product launches for EV power modules reflect a focused push into high-voltage applications. Their R&D pipeline and integration with composites/film ecosystems position them strongly for automotive OEM engagements.
- 3M (USA) — 3M continues to defend use cases across power electronics and energy storage with validated dielectric film offerings and certification updates that streamline customer adoption.
- Saint‑Gobain (France) & AGC Inc. (Japan) — Both offer high-performance fluoropolymer films and bring deep thermal and dielectric expertise, making them relevant partners for high-reliability and high-temperature applications.
- Specialists (Tekra/Materion, Polyflon Technology) — Niche producers remain vital for custom formulations, thin-gauge flexible circuits and RF applications where tailored dielectric constants and bespoke processing services are required.
Recent corporate activity underlines two market realities: (1) incumbents are expanding capacity and product breadth to capture OEM platform deals (DuPont’s capacity expansion in early 2025); and (2) targeted product innovation for EV power electronics continues to be a differentiator (Toray’s advanced fluoropolymer launch in October 2025). Certification and compliance updates from major suppliers (e.g., 3M’s mid‑2025 announcements) are reducing adoption friction for conservative buyers but also raising the bar for emerging entrants.
Key dynamics you must model into 2026 plans
- Input-price pass-through sensitivity. A 12% YoY rise in key fluoropolymer resin costs and an ~8% ocean freight surcharge for hazardous-class shipments materially change supplier economics. Price decks, renewal cadences and cost-sharing mechanisms must be stress-tested across supplier tiers.
- Regulatory scenario planning. With regional chemical restrictions limiting certain fluorinated chemistries, product roadmaps that assume uninterrupted material availability are fragile. Organizations should model alternate chemistries, exemption procurement strategies and the timeline to secure derogations where safety-critical uses apply.
- Trade-policy hedges. Tariff regimes that came into effect in 2025 change sourcing calculations. Tariff-engineering, nearshoring and local conversion strategies will be decisive for companies serving protected markets.
- Certification and product-entry gating. Films with elevated dielectric properties increasingly require specific flammability and safety certifications before commercial deployment. Certification time and cost should be treated as capital expenditure equivalents in project plans.
Strategic imperatives for executives (2026 action checklist)
- Embed supply-risk KPIs into board reporting: lead times, single-supplier exposure and regulatory-compliance milestones.
- Re-price and re-contract: negotiate multi-year purchase agreements with indexed pass-throughs and capacity reservation clauses to secure critical volumes at predictable economics.
- Pursue material diversification: qualify alternate chemistries and specialist suppliers to reduce dependence on constrained fluoropolymer streams.
- Accelerate certification roadmaps: treat UL/IEC approvals as deterministic project milestones and fund parallel test programs to mitigate timeline risk.
- Scan for inorganic opportunities: use the moderate market concentration to pursue bolt-on acquisitions that add niche capabilities or capacity without competing on scale alone.
- Engage public policy: join industry consortia to shape derogation criteria for essential electrical uses where feasible.
90-day tactical playbook for 2026
- Complete a supplier-stress simulation using our scenario workbook: identify two “must-save” suppliers and three “secondary” sources for each critical film type.
- Initiate a resin cost-hedging pilot: secure a portion of next-12-month resin exposure via forwards or index-linked contracts tied to transparent benchmarks.
- Fast-track certification for at least one high-permittivity product platform with contingency funding for retest events.
- Open three M&A/partnership conversations with targeted specialty producers as defensive options against supply shocks or to accelerate roadmap timelines.
- Update commercial contracts to include freight-surcharge pass-through language and clear IMDG classification responsibilities.
Conclusion — why PW Consulting’s analysis matters for 2026
For executives plotting 2026 strategies, the high dielectric plastic films market is neither a low-stakes commodity arena nor a runaway boom market. It is a technically complex, moderately consolidated market where supply-side actions, regulatory shifts and certification timelines materially influence commercial outcomes. Our study synthesizes these elements into a set of executable recommendations — from negotiating contract terms to qualifying alternate materials and identifying precise M&A targets — enabling decision-makers to convert technical differentiation into durable commercial advantage.
Access to the full study provides the proprietary models, segmentation tables, supplier scorecards and contract templates referenced above. Visit our publication page to obtain the complete report and the accompanying scenario workbook that will let your team trade off capacity, compliance and cost risk with precision.
For detailed analysis of this topic, please visit the official page: High Dielectric Plastic Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com