

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Inertial Navigation System Market to Hit USD 3,835 Million by 2032 at a 6.85% CAGR — Base Year 2025 Report Reveals

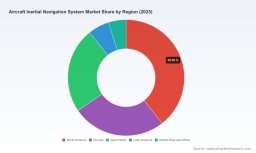
Aircraft Inertial Navigation System Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new Aircraft Inertial Navigation System (INS) Market report provides an incisive, action-oriented view of an industry at the intersection of aerospace modernization, defense preparedness, and sensor miniaturization. This preview summarizes the macro trajectory, competitive dynamics, strategic inflection points and the practical value the full report delivers to executives making procurement, R&D, partnership and M&A decisions in 2026. For competitive reasons, we surface the analytical framework and directional findings while withholding detailed segment tables and granular region/application splits; the full dataset, scenario models and primary-source exhibits are available through our report portal.
Aircraft Inertial Navigation System Market
Market at a glance — growth, scale and concentration
After a period of steady recovery and modernization from 2020 through 2025, the global Aircraft INS market stands at approximately USD 2,415 Million in 2025. PW Consulting’s base-case forecast projects a compound annual growth rate (CAGR) of 6.85% for 2026–2032, driving the market toward roughly USD 3,835 Million by 2032. These figures reflect a mix of fleet refresh cycles in commercial aviation, defense capex allocated to GPS-denied navigation solutions, and accelerating uptake of high-performance INS in autonomous aerial platforms.
Aircraft Inertial Navigation System Market
Market concentration is meaningful: the top three players account for a majority share and the top five control well over two-thirds of the market by revenue. This structure creates differentiated opportunity zones — scale-dependent OEMs and integrators dominate high-reliability, high-cost segments, while specialist players and newer entrants compete on price, miniaturization and rapid iteration.
Aircraft Inertial Navigation System Market
Why this matters for 2026 strategic planning
- Procurement timing and budgeting: With a mid-single-digit-plus CAGR, procurement cycles for platform integrators and Tier-1 suppliers should anticipate steady but manageable price and supply pressure through 2032. Budget scenarios in the report align procurement windows with fleet retrofit schedules to minimize CAPEX spikes.
- Technology roadmap prioritization: Diverging technology trajectories (high-precision fiber-optic and ring-laser platforms versus cost-competitive MEMS and hybrid approaches) require clear product roadmaps. The report maps performance, cost curves and technology risk to help prioritize R&D investment for 2026.
- Supply-chain and raw material risk: Volatility in high-precision sensor components has translated into observable pricing sensitivity; industry inputs suggest raw-material-driven price shifts in the mid-single-digit percent range. The report provides mitigation strategies — from supplier diversification to forward-buying and long-term contracts.
- Defense and GNSS-denial readiness: Rising defense budgets and operational emphasis on GPS-denied navigation materially increase demand for hardened, high-integrity INS. We provide pragmatic go-to-market approaches for vendors seeking to accelerate military certifications and cross-qualify civil variants.
What the full report contains — practical, transaction-ready deliverables
- Top-line market sizing and seven-year forecasting models (2026–2032) with scenario sensitivity (base, upside, downside) and breakpoints for key inflection drivers.
- Technology roadmaps linking gyro and IMU families (ring laser, fiber-optic, HRG, MEMS, mechanical) to expected cost declines, SWaP (size, weight, and power) improvements and lifecycle replacement rates.
- Supply-chain heat maps and tiered risk assessments for component scarcity and lead-time concentration; recommended procurement levers and contractual language to hedge 2026 exposures.
- Competitive benchmarking with profiles, capability matrices and go-to-market positioning for principal vendors; acquisition targets and partner-screening filters for corporate development teams.
- Regulatory and operations impact analysis, including redundancy requirements, dispatch constraints and certification pathways that influence design-for-certification timelines.
- Commercial and defense demand archetypes with deployment roadmaps for manned transports, fighters, helicopters, and unmanned aerial systems — including integration cost and time-to-certification estimates.
- Strategic playbooks: M&A diligence checklists, JV negotiation templates, licensing strategies for novel sensors and IP monetization options.
Competitive landscape — where incumbents and challengers are placing their bets
The competitive map shows a bifurcation between large diversified aerospace suppliers and focused specialist innovators. Below we summarize core companies that define vendor dynamics; the full report expands these profiles with product portfolios, margin analysis and go-to-market KPIs.
- Honeywell International Inc. (Charlotte, NC, USA) — A broad avionics and systems integrator offering ADIRS and compact INS solutions. Honeywell’s strengths lie in avionics integration for major OEM platforms and proven GPS-denied navigation capabilities, positioning it well for large-platform upgrades and avionics suite refresh programs.
- Northrop Grumman Corporation (Falls Church, VA, USA) — Defense-oriented supplier of advanced EGI (Embedded GPS/INS) systems, leveraging fiber-optic gyro platforms for high-precision military applications. Northrop Grumman captures premium defense demand where survivability and anti-jam performance are critical.
- Safran Electronics & Defense (Paris, France) — Focused on hybrid inertial/GNSS systems and crystal HRG technologies. Safran’s compact designs suit rotorcraft, tactical transports and unmanned systems that require integrity in contested GNSS environments.
- Thales Group (Paris, France) — Developer of high-performance inertial reference systems rooted in ring-laser gyro heritage, now expanding into lighter MEMS-based IMUs for civil and military markets. Recent product launches show a dual-track strategy: maintain high-end legacy platforms while pursuing cost-effective new builds.
- Collins Aerospace (RTX, Charlotte, NC, USA) — Focused on MEMS IMUs and Micro INS solutions, Collins targets ruggedized, compact applications — particularly where SWaP and cost efficiency are decisive, such as experimental and certain military platforms.
- Advanced Navigation (Sydney, Australia) — Specialist innovator combining MEMS and FOG approaches, with AI-enhanced navigation features. As a fast-scaling challenger, recent funding rounds are accelerating product development and global market expansion.
Recent catalyst events and their strategic implications
- Private capital fueling innovation: Significant funding rounds for navigation-focused startups have expanded R&D bandwidth and shortened time-to-market for advanced MEMS/AI hybrids. This creates acquisition and partnership opportunities for incumbents seeking to accelerate innovation without building in-house.
- Product launches and miniaturization: Established suppliers are shipping lighter, lower-SWaP IMUs, enabling retrofit opportunities on a wider set of airframes and opening new markets (eVTOL, ISR UAVs). Vendors and integrators must evaluate trade-offs between precision and cost when selecting platforms for 2026 projects.
- Emerging GPS alternatives: Demonstrations of quantum-assisted navigation and alternate inertial augmentation underscore a long-term disruption vector. For 2026, these remain experimental but warrant inclusion in medium-term R&D roadmaps, defensive IP strategies and select pilot programs.
- Regulatory and operational guardrails: Dispatch and redundancy requirements in modern commercial aircraft necessitate robust INS architectures — a non-negotiable constraint for OEMs and airlines that directly affects retrofit prioritization and spares provisioning.
How executives should use this report in 2026
- Procurement teams: Use the report’s scenario models to align long-lead component purchases and to time multi-year blanket contracts that protect margins against raw-material-driven cost swings.
- R&D and product teams: Apply the technology roadmaps and performance-cost trajectories to prioritize sensor families for iterative upgrades versus disruptive bets (e.g., HRG/FOG for high-end, MEMS/AI for volume).
- Corporate development: Leverage the target-screening filters and valuation comparables in diligence on potential buys or strategic partnerships — particularly for companies that strengthen positioning in GPS-denied or miniaturized INS solutions.
- Program managers and integrators: Map certification and integration timelines against the report’s fleet-refresh scenarios to reduce time-to-deployment for retrofit and new-build programs.
Risk considerations and watchlist for 2026
- Raw material and component cost volatility that can compress supplier margins — mitigations include dual-sourcing and indexed contracts.
- Technology substitution risk as quantum navigation and alternative inertial paradigms progress from demonstration to field trials.
- Consolidation pressure from large primes seeking vertical control over avionics stacks, which may limit market access for smaller suppliers without strategic partnerships.
- Regulatory changes in dispatch and redundancy requirements that could increase retrofit demand but also complicate certification pathways.
Conclusion — the decision value of PW Consulting’s Aircraft INS intelligence
For 2026, decision-makers need a report that is both strategic and immediately actionable: one that links macro forecasts to tactical playbooks and transaction-ready diligence. PW Consulting’s Aircraft Inertial Navigation System Market study supplies that linkage — quantifying market scale and growth, mapping technology and supplier landscapes, and delivering procurement and corporate-development tools tailored to real-world timelines.
To review the full forecasts, segmented analyses, company scorecards and downloadable model files that underpin the conclusions summarized here, please visit our report page. The detailed segment-level tables and interactive scenario models are available to licensed subscribers and are structured specifically to support capital allocation, RFP preparation and M&A diligence in 2026.
For detailed analysis of this topic, please visit the official page: Aircraft Inertial Navigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com