

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
TEC Modules Market to Expand at 8.7% CAGR Through 2032 — PW Consulting

Thermoelectric Cooler (TEC) Modules Market: Strategic Outlook for 2026 Decision-Makers
As enterprises plan product roadmaps, supply-chain investments, and go-to-market strategies for 2026, understanding the Thermoelectric Cooler (TEC) modules market is no longer optional — it is strategic. This briefing synthesizes the directional intelligence and decision-ready frameworks from PW Consulting’s latest TEC Modules Market study. It highlights the macro trajectory, competitive dynamics, and the tactical choices that will matter most to OEMs, component suppliers, and systems integrators during the next strategic planning cycle, while intentionally reserving the full subsegment tables and granular numerical breakouts for the full report.
Thermoelectric Cooler (TEC) Modules Market
Executive snapshot: why this matters in 2026
-
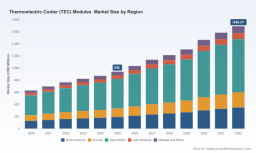
Market momentum: The global TEC modules market has expanded materially over the past half-decade and is positioned to continue robust growth through the end of the decade. From a base of under USD 1 billion in 2025, our forecast shows a clear, sustained upswing driven by higher-density photonics, telecom reliability needs, medical-device miniaturization, and increased electrification across transportation and industrial systems.
Thermoelectric Cooler (TEC) Modules Market -
Compound growth: The market is forecast on an 8.7% CAGR over the 2026–2032 planning window — a rate that supports capital expansion, targeted product innovation, and differentiated service layers for companies that move early.
Thermoelectric Cooler (TEC) Modules Market -
Competitive shape: Market concentration is meaningful but not prohibitive — the leading three firms collectively control just under half of the market, with the top five approaching around three-fifths. This creates clear opportunity for focused challengers and niche specialists.
Market trajectory in plain terms
From 2020–2025 the sector grew from a mid‑hundreds million-dollar base to approximately USD 940 million by 2025, reflecting steady adoption in core electronics cooling and emerging high-reliability segments. Looking forward, the study projects the market crossing the USD 1 billion threshold in the early stage of the forecast and continuing to expand into the late 2020s and early 2030s, with demand patterns skewing toward higher-value, engineered TEC solutions (micro TECs, multi-stage assemblies, and integrated active cooling modules) as application requirements intensify.
For decision-makers in 2026, that means the window for early advantage is open but narrowing: companies that pair product roadmaps with supply continuity, certification roadmaps, and targeted account plays will capture outsized value as the market expands.
Dynamics shaping the 2026 opportunity
-
Materials and capacity: Bismuth telluride remains the dominant semiconductor material in active TEC production. Recent capacity expansions among leading producers are intended to meet rising demand — a positive signal for industrial scale-up, but a reminder that upstream raw-material constraints and price volatility can materially affect cost curves and lead-times for manufacturers and integrators.
-
Standards and qualification: Certification pathways (for example, telecom and optoelectronic reliability standards) are accelerating deployment in demanding segments. Components that meet recognized qualification regimes reduce long sales cycles and lower technical risk for system integrators — a practical axis for commercial differentiation.
-
Energy and sustainability tailwinds: With policy and buyer emphasis on energy efficiency and refrigerant-free thermal solutions, TEC modules offer an attractive solid-state cooling alternative. This macro trend expands addressable use cases beyond legacy niches into mainstream electronics and environmental-control applications.
-
Cost and talent pressures: Precision manufacturing and custom-engineering for high-reliability TECs keep labor and engineering costs elevated. Companies must choose between vertical investment in manufacturing capability, outsourcing to specialized suppliers, or platformizing product lines to control cost-to-serve.
-
Infrastructure evolution: Planned capacity additions and factory modernization efforts focused on bismuth telluride processing and assembly indicate a near-term improvement in availability for qualified products — yet timing and regional logistics will be critical to secure supply during product ramp phases.
Segmentation overview (high-level)
The study organizes the sector across three practical dimensions — by product type, by application, and by geography — to support go-to-market and product planning. Key takeaways:
-
Product types: The market supports both single-stage and multi-stage TEC architectures. Single-stage modules remain the workhorse across many applications, while multi-stage designs command attention in extreme ΔT or high-precision thermal-control use cases. Product strategy should align with target thermal specifications and system-level integration complexity.
-
Applications: End markets include consumer electronics, communications (including photonics and telecom optics), medical devices, automotive electronics, industrial thermal management, and aerospace/defense. Each application pathway carries distinct reliability, certification, and margin profiles; the full report provides granular demand drivers and risk matrices for each segment to support prioritization.
-
Geography: Demand is globally distributed, with concentrated pockets of manufacturing, R&D, and end-system OEMs. The strategic imperative for 2026 is to align supply-access with target accounts and to model regional logistics and tariff scenarios in financial planning.
Note: detailed segment tables, unit volumes, and per-region/per-application revenue splits are intentionally reserved for the full report.
Competitive landscape: who to watch and what they signal
The competitive map is populated by a mix of specialized TEC manufacturers, diversified thermal-systems players, and regional high-volume producers. The full study profiles company strategy, product portfolios, go-to-market models, and recent R&D or partnership moves. Highlights:
-
Sheetak (Austin, Texas) — A technology-focused manufacturer with both standard CENTUM® product lines and µCENTUM™ micro TECs for precision photonics and optoelectronics. Recent activities include several product launches aimed at miniaturized applications and modular prototyping kits that reduce developer time-to-test, alongside exhibition plans to demonstrate live systems. These signals point to an aggressive go-to-market push into high-growth optics and telecom niches.
-
TEC Microsystems GmbH (Berlin) — A European specialist with aluminum-plate and ceramic-alternative TEC series tailored to telecom and detector markets. Their focus on Telcordia-style qualification and heavy-load modules speaks to the reliability-driven segments of the market.
-
Ferrotec Corporation (Tokyo) and Laird Thermal Systems (Delaware) — Established suppliers with broad portfolios for industrial and telecommunications systems, often competing on high-power offerings and integrated subassemblies.
-
TE Technology (Pennsylvania), Crystal Ltd. (Hong Kong), KELK (Tokyo), RMT (Russia), Thermonamic (Jiangxi), and KRYOTHERM (Germany) — A cohort of regional and specialized players providing both standard and custom TECs. Their presence underlines a market structure that balances scale with niche engineering depth.
Recent company developments — especially rapid SKU introductions and partnerships designed to shorten prototyping cycles — underscore an industry pivot toward faster validation and tighter collaboration with system OEMs. The full competitive chapter includes capability matrices, procurement risk scores, and scenario-based supplier selection tools.
Strategic playbook for 2026
-
Match solution depth to system risk: If your application requires telecom-grade reliability or medical certification, prioritize suppliers and designs with documented qualification pathways rather than attempting to accelerate a low‑maturity in-house build.
-
Lock critical materials early: Given the bismuth telluride demand signal, secure upstream commitments or dual-source plans to mitigate lead-time and price exposure during product ramps.
-
Design modular options: Modular TEC assemblies and development kits greatly reduce prototyping time and supplier friction. Plan product architecture to accept plug-in TEC modules where feasible to accelerate time-to-market.
-
Invest in thermal system-level IP: Margins accrue to firms that combine TEC modules with control electronics, heat-spreading, and system diagnostics. Consider partnerships or acquisitions that fill these adjacent capability gaps.
-
Scenario-test supply concentration: With a moderate market concentration among leaders, build procurement scenarios that model supplier failure, capacity constraints, and certification timelines. The report provides ready-to-use models for stress-testing sourcing strategies.
What the full report delivers (operational highlights)
-
Comprehensive market model (2020–2032) with annualized revenues and scenario-based forecasts calibrated to demand drivers and materials constraints.
-
Segmentation tables and demand-driver narratives for product types, end-use applications, and regional markets (note: these detailed tables are available only in the full report).
-
Supplier and competitor profiles with product maps, capability ratings, and partnership intelligence — including detailed case notes on recent launches and trade-show activities.
-
Procurement & risk toolkit: supplier selection matrices, lead-time sensitivity analyses, and unit-cost build-ups that translate market signals into sourcing decisions.
-
Strategic scenarios and playbooks for new entrants, incumbent manufacturers, and systems integrators — including M&A stress-test frameworks and commercialization timelines.
How to use this intelligence in 2026 planning
For R&D leaders: prioritize modular micro-TEC architectures and invest in control electronics integration to capture premium segments. For supply-chain and procurement functions: model multi-tier sourcing, secure critical raw-material commitments, and evaluate nearshoring for high-reliability lines. For corporate development teams: map acquisition targets that provide either manufacturing scale in bismuth telluride processing or system-level thermal integration IP.
Each of these recommendations is actionable in the coming 12–18 months and is supported by the full report’s datasets, supplier scorecards, and scenario models — resources designed to convert market direction into board-level decisions.
Conclusion: a tactical window for decisive plays
The TEC modules market is entering a phase where growth and technical differentiation intersect. The macro trajectory (an 8.7% CAGR across 2026–2032 from a 2025 base of roughly USD 940 million) creates opportunities for firms that can align product capability, supply assurance, and certification readiness. The strategic choices you make in 2026 — about sourcing, modularization, and targeted product investment — will determine whether you are a market follower or a category shaper as demand matures.
To move from strategic intent to executable plans, access the full PW Consulting TEC Modules Market report for the detailed datasets, segment-level analytics, and supplier assessments that underpin the recommendations above.
For detailed analysis of this topic, please visit the official page: Thermoelectric Cooler (TEC) Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com