

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fiber Optics Market to Reach USD 15,227.65 Million by 2032 at 6.86% CAGR

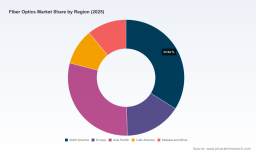
Fiber Optics Market 2026: Strategic Intelligence Briefing — What Senior Leaders Must Know Now
Executive snapshot
As the principal industry advisor at PW Consulting, I present a concise, decision-focused synthesis of our new Fiber Optics Market study — designed to inform board-level strategy, capital allocation, and operational planning through 2026 and beyond. The global fiber optics market, measured at the 2025 base year, stands at roughly USD 9.6 billion and is projected to exceed USD 10.4 billion in 2026. Our forecast through 2032 reflects a compound annual growth rate (CAGR) of approximately 6.86%, with the market approaching the mid‑teens in billions of USD by the end of the forecast window. These macro dynamics set the stage for a high‑stakes period of investment, supply‑chain reconfiguration, and technology differentiation.
Fiber Optics Market
Why 2026 is an inflection year
-
Converging demand drivers. AI-driven hyperscale data center buildouts, accelerated FTTH and broadband initiatives, and 5G backhaul rollouts are converging to raise both unit volumes and requirements for higher-density, lower-loss optical solutions. This is creating more predictable long‑term demand while intensifying near‑term supply pressure.
Fiber Optics Market -
Supply-side volatility. Critical dopants and raw materials have become focal points of strategic vulnerability. One resource critical to optical fiber preforms is heavily concentrated geographically — a single country controls an outsized share of global germanium supply — and export controls remain an active policy lever. At the same time, prices for conventional single-mode fiber spiked sharply in early 2026, reflecting tightening supply/demand balances.
Fiber Optics Market -
Policy and procurement momentum. Large public funding programs and national infrastructure initiatives (notably multi‑billion-dollar broadband allocations) are directly accelerating greenfield and upgrade projects, shifting public and private procurement toward domestic capability and resilient supply chains.
-
Industry structure in transition. While leading vendors maintain scale advantages, concentration metrics point to a market that remains meaningfully fragmented — creating space for technology‑led entrants and regional champions to capture specialized niches.
What the PW Consulting report delivers (practical, operational content)
-
Actionable market sizing and near‑term demand scenarios calibrated to AI, telecom, broadband, and industrial segments — with upside/ downside scenarios tied to capacity additions, raw‑material price shocks, and regulatory shifts.
-
Supply‑chain stress maps that identify single‑point dependencies (materials, equipment, geographies) and provide mitigation playbooks — from strategic stockpiling and dual‑sourcing to vertical integration and contract architecture.
-
Commercial playbooks for suppliers and buyers: pricing strategies under tight supply, contract clauses for long‑lead items, lane‑level logistics optimization, and criteria for selecting co‑packaged optics and multicore fiber solutions.
-
Technology adoption frameworks: vendor shortlists, TCO comparisons for multicore vs. traditional fiber architectures in dense AI campus environments, and readiness assessments for co‑packaged optics for hyperscalers and OEMs.
-
M&A and investment diagnostics: valuations guidance, roll‑up play options, and integration checklists for acquiring capacity or capabilities (manufacturing, preform supply, specialty fibers).
-
Regulatory and geopolitical scenario planning: licensing risk matrices, export‑control contingency plans, and suggested engagement strategies with policymakers to de‑risk critical material flows.
Strategic implications by value chain node
-
Raw materials and preforms — prioritize visibility. Firms must obtain granular visibility into fused‑silica preform supply and dopant sourcing. The raw material market itself is expanding in absolute terms; however, concentrated supply and periodic export restrictions can rapidly alter cost curves and lead times. Near‑term spikes in key fiber prices underline the need for fortified sourcing agreements and scenario planning.
-
Manufacturing and capacity — rethink geographic footprints. New manufacturing expansions in North America and other markets are reshaping the tradeoffs between proximity to hyperscalers and cost optimization. For strategic buyers, nearshoring and qualifying alternative suppliers reduce risk; for suppliers, targeted capacity investment aligned to AI data center clusters creates premium margins on advanced fiber products.
-
Products and architecture — specialization pays. Multicore fibers, microcables, and co‑packaged optics are shifting the performance and procurement calculus for dense deployments. Players that can demonstrate lower-loss, higher‑density solutions with validated interoperability will earn the most valuable contracts in AI campus and hyperscale corridors.
-
Commercial and pricing strategy — anticipate volatility. Buyers and sellers should build flexibility into pricing and contract terms to hedge raw‑material swings and supply disruptions. Shorter review cycles, indexed pricing bands, and capacity reservation models are becoming best practice.
Competitive landscape — who matters and why (high‑level analysis)
The market is anchored by established global manufacturers and integrators with distinct strategic positions:
-
Corning Incorporated — Scale plus innovation. Corning combines high-volume manufacturing with recent strategic wins and product launches tailored to AI data centers. A multiyear supply agreement with a major hyperscaler underscores both their scale and their ability to secure anchor demand. Recent OFC 2026 introductions — including multicore fiber and co‑packaged optics systems — position them to capture next‑generation density projects.
-
Sumitomo Electric Industries and Fujikura — low‑loss optics and MCF leadership. These incumbents compete on ultra‑low‑loss fiber technologies and end‑to‑end connectivity solutions. Collaborative industry efforts to define multicore fiber standards demonstrate their strategic push to shape the technical baseline for AI campus interconnects.
-
Prysmian Group , CommScope , and Nexans — infrastructure integrators. These players blend cable systems with installation services, targeting telecom and utility upgrades as well as enterprise and industrial applications.
-
Regional and specialty players — capacity and niche differentiation. Companies such as Fitel/OFS, Sterlite, YOFC, FiberHome, and Amphenol play critical roles in regional supply, specialty fiber segments, and component ecosystems (connectors, transceivers). Their strategic value lies in regional scale, local customer relationships, and component ecosystems that large-scale manufacturers cannot replicate quickly.
Recent industry developments that matter in 2026
-
Large-scale strategic procurement: The announcement of a multiyear supply agreement between a leading glass fiber manufacturer and a major AI operator highlights how anchor contracts are reshaping capacity planning and capital allocation.
-
Product roadmaps aligned to AI density: Several incumbents unveiled multicore fiber and microcable solutions tailored to AI data centers, together with next‑gen connectors and co‑packaged optics demonstrations — all clear signals that product differentiation will drive contract awards.
-
Standards and collaborations: Industry collaborations to define multicore fiber MSA profiles show the market moving from proprietary experiments toward interoperable ecosystems — a crucial development for scaling deployments and reducing integration risk.
-
Raw‑material geopolitics: Export controls and concentrated sourcing for key dopants create ongoing operational risk for manufacturers and buyers. Firms without robust contingency plans face margin compression or delivery delays.
Risk matrix: what keeps CFOs and CTOs awake
-
Material access and price shocks — mitigate with layered sourcing, strategic inventory, and fixed/ index‑linked contracts.
-
Technology obsolescence — protect with modular architecture choices, interoperability standards compliance, and staged migration investments.
-
Regulatory shifts — maintain active policy engagement and export‑control legal review processes, especially for cross‑border customers and defense‑sensitive end‑uses.
-
Execution risk on capacity projects — deploy stage‑gated capital programs and prequalification of EPC and equipment suppliers to avoid schedule slippage and cost overruns.
How senior leaders should act in 2026
-
Buyers: Lock in critical capacity via multi‑year agreements with flexible remittance and capacity reservation clauses; prioritize partners who demonstrate both technical roadmap alignment and diversified supply chains.
-
Suppliers: Focus capex on high‑margin, differentiated products (multicore, ultra‑low‑loss fibers, and integrated connectivity for AI campuses); pursue strategic partnerships to secure feedstock and preform access.
-
Investors and private equity: Look for asset plays that consolidate regional capacity or acquire specialty technology providers with defensible IP and strong customer contracts.
Why PW Consulting’s study is strategically valuable for 2026 decisions
Our report is expressly engineered to translate market trajectories into executable decisions. It combines robust macro forecasts with supplier and raw‑material stress tests, a detailed competitive playbook, and practical templates for contracting, procurement, and capex prioritization. Importantly, the study provides scenario‑based financial models and decision trees that help quantify the tradeoffs between near‑term resiliency investments and long‑term margin objectives.
We deliberately present high‑confidence directional findings here while withholding granular regional and application split tables in this preview — those granular segment matrices, vendor scorecards, and contract clause libraries are included in the full report and interactive dashboards available via our portal.
Next steps
-
Download the full report to access the segmented demand models, supplier scorecards, and our proprietary scenario simulator.
-
Engage PW Consulting for a bespoke workshop: we map the study’s scenarios to your supply base, capital plans, and procurement contracts to generate an actionable 90‑day roadmap.
For C‑suite teams preparing for 2026, the central imperative is clear: convert macro growth and technological opportunity into defensible, risk‑adjusted positions across sourcing, manufacturing footprint, and product differentiation. PW Consulting’s Fiber Optics Market study gives you the frameworks, scenarios, and commercial tools to do exactly that — with the full, granular intelligence accessible in the complete report.
For detailed analysis of this topic, please visit the official page: Fiber Optics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com