

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Helium Gas Market to Hit USD 344.8M by 2032 at 6.98% CAGR

Helium Gas Market — Strategic Imperatives for 2026
Executive snapshot
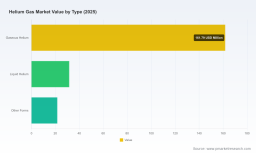
As companies plan capital allocation and supply strategies for 2026, the helium market presents a distinctive combination of steady long-term growth and acute near-term volatility. Our PW Consulting Helium Gas Market study — anchored to a 2025 base year — projects the global market growing from USD 215.0 Million in 2025 to approximately USD 344.8 Million by 2032, representing a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. Historical context matters: the market moved from roughly USD 163 Million in 2020 to USD 215 Million in 2025, a pattern that reflects both demand rebound and supply-side structural shifts.
Helium Gas Market
Why this matters for 2026 decision-making
- Capital allocation: With a near-term uptick in headline prices following supply disruptions, investment committees must balance the temptation to accelerate upstream projects with the risk of stranded capacity should new supplies normalize.
- Procurement and contracting: Spot volatility and the return of geopolitical supply risk make traditional short-term spot purchases increasingly costly; conversely, competitive long-term bilateral contracts and integrated supply agreements are gaining strategic value.
- Operational resilience: End-users in semiconductors, cryogenics and medical imaging face asymmetric supply risk — a small shortage can halt critical processes. Inventory strategy, access to strategic storage, and recovery/recycling investments are now core operational priorities.
- M&A and JV timing: Moderate market concentration coupled with rising project activity creates selective windows for acquisitions and partnering that can lock in feedstock or liquefaction capacity without paying for overcapacity premiums.
Market dynamics — what’s driving growth and disruption
Two sets of forces are operating simultaneously. First, secular demand drivers — primarily cryogenics and advanced manufacturing use-cases — continue to support a multi-year growth path captured by the 6.98% forecast CAGR. Second, supply-side events and policy shifts introduce episodic shocks that materially change near-term economics and contract structures.
Helium Gas Market
- Geopolitical shock: The March 2026 force majeure declaration at a major Middle East production hub removed a material portion of global supply (industry reports estimate a removal on the order of tens of percent of global output). The immediate effect was a measurable tightening of available product and a jump in short-term spot pricing.
- New production and storage: Regulatory and permitting developments, plus new U.S. production operations and storage capacity coming online, are reshaping regional resilience. USGS reporting in early 2026 notes several newly commissioned U.S. operations and an additional cavern placed into strategic storage. These infrastructure moves alter seasonal and regional arbitrage possibilities for buyers.
- Product and process innovation: Recent supplier product launches — high-purity grades and improved liquid delivery systems — signal supplier focus on differentiated offerings (purity, safety, and efficiency) that command premium positioning with semiconductor and cryogenics customers.
- Decarbonization and integration: Emerging project-level combinations of CO2 management and helium liquefaction are appearing in development agreements. These integrated designs both reduce the environmental footprint of helium extraction and open pathways for project financing under ESG criteria.
Competitive landscape — what the leading players are doing
The helium supply ecosystem mixes integrated industrial gas majors, national oil & gas producers, regional specialists, and resource explorers. Market concentration metrics indicate a relatively fragmented supply base; top supplier groupings collectively do not dominate the market to the same extent seen in many other industrial gases. Against this backdrop, players are pursuing distinct strategies:
Helium Gas Market
- Integrated industrial gas companies (e.g., long-established global suppliers) emphasize downstream liquefaction, very-high-purity product lines, and contractual reach into semiconductor and medical markets. Recent product launches highlight investments in purity and delivery systems tailored to mission-critical customers.
- Large upstream producers leverage existing natural gas processing footprints to monetize helium as a differentiated by-product. Their strategic advantage lies in low incremental cost of supply and export scale, but they are exposed to commodity-linked cyclicality.
- Regional and niche players focus on localized logistics, recovery/recycling equipment, and bespoke supply solutions for industrial and scientific customers — a play that becomes more attractive when global transport constraints or geopolitical events raise the value of local secure supply.
- Explorers and junior developers are maturing projects; strategic partnerships or offtake agreements with established suppliers are now commonplace as a route to de-risk first production and guarantee market access.
Notable recent developments underline these trends: a major regional force majeure event in early 2026 that materially disrupted global flows; upstream offtake agreements from emerging producers to lock in revenue; and supplier product launches focused on higher purity and improved liquid delivery — each reinforcing the mixed character of supply risk and supplier differentiation.
How leading companies should respond in 2026 — a pragmatic playbook
Based on our integrated demand-supply modelling and scenario analysis, PW Consulting recommends a prioritized, actionable approach for corporate decision-makers:
- Secure layered supply: Combine a core of long-term contracted volumes with a secondary pool of rotational spot or short-term flexible supply. Prioritize contracts with conditional delivery terms and built-in flexibility for force majeure scenarios.
- Invest selectively in storage and recycling: Where economics permit, invest in strategic storage capacity (or long-term access agreements) and end-use recovery technologies to blunt short-term outages and reduce procurement spend volatility.
- Pursue vertical partnerships: Downstream industrial users should evaluate equity or strategic offtake stakes in near-term development projects to obtain preferential access and improve margin predictability.
- Differentiate by service not just price: Suppliers should develop product bundles — purity-grade guarantees, delivery SLAs, and field-service capabilities — to capture higher-margin segments, particularly in semiconductors and scientific markets.
- Hedge policy and geopolitical risk: Model scenario permutations that incorporate supply shocks, rapid recovery, and prolonged outages. Use these scenarios to stress capital plans and contract negotiation playbooks for 2026.
What’s included in the PW Consulting Helium Gas Market study
The research package is designed as a decision-ready tool for 2026 strategy cycles. It combines quantitative rigor with transactional practicality while maintaining the confidentiality of proprietary split tables and supplier-by-region revenue detail (these granular items are reserved for full-report subscribers). Key deliverables include:
- Transparent market-sizing and methodology appendix tied to a 2025 base year and a 2026–2032 forecast suite (numerical headline trajectory and CAGR disclosed; detailed sub-segment tables are available in the full report).
- Supply-demand balance and elasticity analysis, including scenario runs that quantify the operational impact of specific disruption events and capacity additions.
- Price-formation model calibrated to spot, short-term and contract pricing behaviors — with scenarios reflecting recent 2026 disruptions.
- Supplier scorecards and risk heatmaps that evaluate production reliability, liquefaction footprint, logistics exposure, and contractual flexibility for major and regional players.
- Deal playbook and contract templates for offtake, tolling, and liquefaction arrangements — crafted for use by procurement, legal, and commercial teams.
- M&A short-listing and valuation benchmarks for upstream and midstream assets, with integration risk checklists and suggested earn-out structures suited to volatile commodity windows.
- Operational benchmarking (liquefaction CAPEX/OPEX ranges, purity-delivery cost curves, recovery/recycling economics) and a prioritized investment roadmap to strengthen supply resilience.
Competitive implications — spotlight on select companies
Major integrated gas companies remain best positioned to serve high-value end-markets because of their scale in liquefaction, distribution, and specialty gas portfolios. Large upstream energy firms, by contrast, can undercut marginal costs for helium when integrated with natural gas processing but are less focused on product differentiation. Regional specialists and emerging developers are becoming acquisition targets or JV partners as buyers seek supply diversity.
PW Consulting’s company profiles — covering global industrial gas leaders, national producers, regional suppliers and project developers — provide strategic intelligence on corporate positioning, fleet footprints, recent product launches, and announced agreements. Notably, 2026 saw new product introductions and offtake agreements that materially alter the competitive playing field; these developments are analyzed in the report with implications for procurement and partnership strategies.
Readiness checklist for 2026
- Have you stress-tested procurement and production plans against a multi-month export shutdown scenario?
- Do your contracts include access to contingency volumes and defined escalation clauses tied to spot benchmarks?
- Is your capex plan flexible enough to accelerate liquefaction or storage investments if project economics improve post-shock?
- Have you assessed partnering options with regional suppliers to reduce single-point-of-failure exposure?
- Can your operations recapture helium or otherwise reduce dependencies through substitution or efficiency gains?
Final perspective — strategic posture for the coming 18 months
2026 will be a decisive year for companies active in the helium ecosystem. The market’s headline growth trajectory is intact — the forecast CAGR reflects ongoing structural demand — but the path is jagged because of outsized supply shocks and fast-moving project development activity. Organizations that combine financial discipline with operational preparedness (storage, recycling, flexible contracting) and strategic collaborations will convert volatility into advantage.
PW Consulting’s full Helium Gas Market report provides the granular datasets, segmented forecasts, supplier scorecards, and executable contract templates needed to move from insight to action. For teams preparing 2026 budgets or negotiating multi-year offtake arrangements, the report is intentionally structured to deliver both the quantitative inputs and the pragmatic playbooks required to secure supply, manage cost, and capture growth.
Next steps
Contact our research desk to schedule a briefing or to obtain the full report that contains the comprehensive segment tables, regional breakdowns, and the supplier-specific financial and operational metrics omitted from this overview. The full dataset is necessary for transaction-level diligence and precise procurement modeling in 2026.
For detailed analysis of this topic, please visit the official page: Helium Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com