

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Carbon-Carbon Composite Market to Rise to USD 334.67M by 2032 at 6.55% CAGR

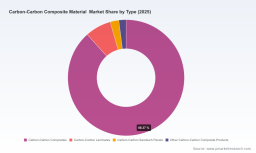
Carbon-Carbon Composite Material Market: Strategic Intelligence for 2026 Decision-Making
Executive teaser
As companies plan capital allocation, supplier strategies, and product roadmaps for 2026, the carbon-carbon (C/C) composite market presents a mix of predictable growth and concentrated supply-side risks. Our base-year analysis (2025) shows a market that has expanded steadily since 2020 and — under conservative demand scenarios — is expected to continue growing through 2032 at a compound annual growth rate of 6.55% (forecast period 2026–2032). PW Consulting’s new study synthesizes market sizing, technology inflection points, supply-chain concentration, regulatory dynamics, and competitive positioning into an operational playbook designed to reduce execution risk and accelerate value capture.
Carbon-Carbon Composite Material Market
Why this study is strategically material for 2026
- Timing of capital deployment: The market size at the 2025 base year (~USD 215.0 Million) and the pathway to 2032 (~USD 334.7 Million under base forecasts) create clear inflection windows where incremental capacity or capability investments can unlock disproportionate revenue and margin upside. Our modelling highlights when to commit to brownfield expansions versus modular, short-cycle investments.
- Supply concentration and procurement risk: The upstream feedstock and precursor market is tightly consolidated. This creates both price volatility and single-source failure risk — factors that materially affect C/C producers’ cost curves, delivery reliability, and make-versus-buy decisions for OEMs in aerospace, defense, and high-end industrial markets.
- Regulatory and policy contingency planning: Recent tariff and trade shifts in the United States, coupled with environmental constraints on precursor production, require immediate reassessment of supplier footprints and contractual protections (e.g., take-or-pay, destination clauses, and price pass-through mechanisms).
- Commercial differentiation: Improvements in densification, weave architecture, and hybrid laminates are transitioning C/C composites from highly specialized niches toward broader aerospace and industrial adoption. That transition creates near-term opportunities for premium pricing and longer-term pressures from commoditization — both of which are covered in actionable scenarios in the report.
Market trajectory at a glance
From 2020 through 2025 the market moved through a steady growth phase. The 2025 base year is a practical inflection point where pandemic-driven distortions have evaporated and secular demand drivers (aerospace recovery, e-mobility high-performance applications, industrial process upgrades) reassert themselves. Our forecast through 2032 assumes a stable macroeconomic backdrop and an industry CAGR of 6.55% across 2026–2032, yielding material expansion in total available market value by decade end. In parallel, global production tonnage and average selling price trends (industry-level production in 2024 was ~25,710 tons with an average selling price near USD 9,200/ton) indicate a market where volume growth and ASP dynamics both contribute to revenue expansion.
Carbon-Carbon Composite Material Market
What the report delivers — operationally useful content
- Executive dashboard: verified historicals (2020–2025), base-year reconciliations, and scenario-driven forecasts (2026–2032) with Monte Carlo sensitivity on demand, CAPEX outcomes, and key commodity inputs.
- Demand-by-use-case narratives: demand drivers, adoption levers, and obsolescence risks across high-value end uses, with TAM/SAM/TOM frameworks that connect OEM procurement cycles to supplier capacity planning.
- Supply-chain heatmap: supplier concentration analysis, precursor supplier risk matrices, nodal logistics cost models, and tariffs/NTB scenario impact assessments for 2026 planning horizons.
- Competitive intelligence and supplier scorecards: capability, scale, technology roadmap, margin proxies, and M&A watchlist for the leading global and regional players — enabling fast shortlist decisions for partnerships, JV targets, or acquisitions.
- Technology and process deep dives: densification routes, resin infiltration trade-offs, densified vs. pre-preg architectures, and capex/throughput benchmarks for greenfield vs. retrofit investments.
- Commercial playbook: pricing strategies, aftermarket services, OEM co-development frameworks, and warranty/total-cost-of-ownership levers that improve contract convertibility.
- Regulatory & sustainability impact briefings: emissions constraints on precursor production, compliance cost scenarios, and blueprints for low-carbon positioning that can be capitalized for premium procurement programs.
Competitive landscape snapshot (what you need to know for 2026)
The C/C composite market is structurally concentrated — the top three players capture a substantial share of global revenue, and the top five even more so. This concentration amplifies strategic implications:
Carbon-Carbon Composite Material Market
- SGL Carbon SE (Germany): A market leader in high-performance C/C with deep aerospace braking and thermal protection competencies. Their product depth and installed credibility with tier-1 OEMs make them a natural partner for OEMs seeking low technical risk solutions.
- Toray Industries (Japan): A dominant precursor and carbon-fiber supplier with vertically integrated capabilities. Toray’s control of upstream feedstock and R&D investments in advanced prepregs gives them leverage over pricing and supply continuity — a critical factor for firms that rely on uninterrupted supply for just-in-time production.
- Hexcel Corporation (U.S.): Strong in aerospace-grade composites and evolving C/C offerings. Hexcel’s customer relationships with large airframers and historical composites know-how make them an important participant in platform-level supply decisions.
- Tokai Carbon, Nippon Carbon, Schunk Carbon Technology, Teijin, Mitsubishi Chemical, Solvay, and specialized U.S./China players: Each brings differentiated strengths — from high-temperature structural materials to scale production for industrial markets. Their strategic moves (capacity expansions, new product lines, and regional investments) will determine competitive dynamics in the next 24 months.
Recent industry actions signal where the market is heading: capacity expansions by major precursor and composite producers, strategic facility investments by aerospace suppliers, and product branding focused on sustainability. Taken together, these moves indicate rising commercial throughput and renewed supplier investment — but also a period of tightened precursor availability and potential margin compression for commodityized streams.
Recent developments that alter 2026 playbooks
- Upstream capacity announcements and expansions (e.g., expanded precursor and carbon-fiber production) change the timing of when feedstock constraints ease and therefore when downstream producers can scale reliably.
- Large OEM facility expansions and targeted acquisitions in thermal protection and brake systems increase demand certainty for selected suppliers, but also raise barriers for newcomers seeking to gain OEM approvals quickly.
- Regulatory shifts — notably U.S. tariff and trade policy adjustments and environmental limits on precursor production — force reconfigurations of logistics, inventory strategy, and contractual protections. Firms that model these shifts and negotiate flexible supply agreements will have a durable advantage.
Top strategic plays for 2026 (practical, prioritized)
- Short-term (0–3 months): Execute accelerated supplier due diligence and secure flexible, multi-year supply agreements with upstream precursors; implement trigger-based option contracts to hedge tariff or feedstock price spikes.
- Medium-term (3–12 months): Evaluate co-investment or JV opportunities with incumbent C/C producers to de-risk approval timelines for aerospace and defense platforms; prioritize modular capacity investments to match forecasted ramp profiles while avoiding stranded asset risk.
- Portfolio-level (12–36 months): Consider vertical integration into critical precursor processes if margin and strategic access analyses support it; alternatively, secure strategic minority stakes in specialized densification technology providers to lock preferential access to novel processes that enable cost or performance differentiation.
- Commercial (ongoing): Build aftermarket and services revenue via long-tail maintenance contracts for C/C-based components (thermal protection, brakes) — these contracts improve revenue visibility and reduce reliance on cyclical OEM programs.
How to use this intelligence in your 2026 planning cycle
PW Consulting’s study is built to be a decision-support tool rather than a descriptive document. Use it to:
- Run sensitivity analyses on capex timing and contract structures using our integrated financial model.
- Create a staged supplier-qualification plan tied to procurement milestones and contract release points.
- Align R&D roadmaps with near-term densification and hybridization trends that will determine product competitiveness in 2026–2028.
- Design scenario-triggered playbooks for tariff or feedstock shocks, with predefined governance for invoking contingency actions (dual-sourcing, temporary production relocation, inventory drawdown).
Note on withheld data and next steps
Consistent with the “trailer” principle of this briefing, we have intentionally demonstrated the analytical depth of our work while withholding the granular sub-segment tables and region/application breakdowns that underpin commercial commitments and competitive bids. The full report includes the detailed segmentation, supplier scorecards, and model inputs that organizations use to finalize procurement contracts, investment memoranda, and M&A term sheets. Accessing that content will equip your leadership team to move from strategy to signed agreements with confidence.
Call to action
If your 2026 strategy requires prioritized supplier commitments, optimized capex timing, or an M&A shortlist in the carbon-carbon composite space, PW Consulting’s full Carbon-Carbon Composite Material Market report provides the calibrated data models and scenario playbooks needed to act. For tailored briefings, model extracts, or a one-day executive workshop to convert the study’s findings into a 90-day execution plan, contact our industry team.
For detailed analysis of this topic, please visit the official page: Carbon-Carbon Composite Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com