

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Railway Maintenance Machinery to reach USD 633M by 2032 at 5.8% CAGR

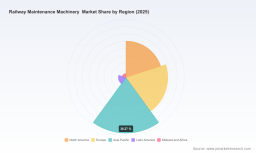
Railway Maintenance Machinery Market: Strategic Briefing for 2026 Decisions
As rail operators and equipment manufacturers enter an inflection point, PW Consulting’s new Railway Maintenance Machinery Market study offers a timely strategic compass for 2026 planning. Built on a 2025 base year and a historical window covering 2020–2025, the study projects the market forward through 2032. The market is on a steady growth trajectory—registering a compound annual growth rate (CAGR) of 5.8%—with total industry revenue rising from the mid-hundreds of million USD in 2025 to well over half a billion by the early 2030s. For executives making capex, R&D, partnership, or M&A decisions this year, the study translates these macro signals into actionable options, risk trade-offs and near-term execution paths.
Railway Maintenance Machinery Market
Why 2026 is a Strategic Inflection Year
-
Acceleration of automation. Recent field trials and product launches have shown that autonomous and semi-autonomous maintenance platforms are moving from pilot to operational status. The incremental productivity and night-time utilization unlocked by these systems change the investment calculus for operators and OEMs alike.
Railway Maintenance Machinery Market -
Digital-native maintenance models. AI-driven condition monitoring and machine-vision-enabled grinding or tamping systems are already delivering step-change improvements in unit efficiency. Buyers must decide in 2026 whether to adopt bolt-on digital upgrades, pursue OEM-supplied integrated solutions, or develop in-house capabilities.
Railway Maintenance Machinery Market -
Margin pressure and supply volatility. Volatile steel prices and rising labor costs are compressing OEM margins and altering supplier negotiations. Firms that lock in material hedges, revise cost-to-serve models, or redesign products for material efficiency will secure a long-term edge.
Market Trajectory and Strategic Implications
From a macro perspective, the sector has expanded from a post-2020 base to a larger, more diversified marketplace by 2025, and is projected to grow consistently through 2032 underpinned by network renewal programs, capacity expansion in key corridors, and an uptick in replacements and upgrades. This growth is neither uniform nor uncontested: market concentration metrics indicate that a handful of established global players command a meaningful share of revenues, while specialist and regional suppliers continue to capture niche demand.
For 2026 strategies, the implications are clear:
-
Prioritize modularity and retrofitability. With fleet renewal budgets constrained in many regions, products that can be retrofitted with automation or energy-efficient powertrains will displace single-purpose capital goods.
-
Design for cross-border operability. Fragmented rail standards and homologation hurdles are limiting equipment interoperability in multiple markets. Firms that invest in multi-jurisdiction certification roadmaps will unlock serviceable market pools faster.
-
Move beyond the product to serviced outcomes. The competitive advantage is shifting toward integrated service contracts—predictive maintenance, uptime guarantees, and performance-based pricing—that smooth demand and increase lifetime value.
Technology and Product Trends Shaping 2026 Decisions
-
Autonomy and night operations. Recent trials of autonomous tamping systems demonstrate the feasibility of unsupervised night-time maintenance windows, significantly increasing asset utilization and reducing traffic interruption costs. Operators should evaluate pilot deployments that target high-impact, low-risk corridors first.
-
AI-enabled condition-based maintenance. AI and LIDAR-enabled grinding and milling systems have shown notable efficiency gains in real-world deployments. Integrating condition-sensing into procurement criteria will reduce lifecycle costs and justify premium pricing for smarter machines.
-
Energy transition and drivetrains. Energy efficiency mandates and fuel-switching policies are accelerating electrified and hybrid powertrain development for maintenance machinery. Procurers must assess total-cost-of-ownership under differing regulatory scenarios when evaluating next-gen machines.
-
Digital twinning and simulation. Virtual commissioning and digital twin models shorten time-to-deploy and inform predictive replacement cycles. Early adopters will see faster commissioning and fewer warranty incidents.
Competitive Landscape — Who Matters and Why
The market remains anchored by established global manufacturers and specialist technology providers. Several firms warrant specific attention due to their product breadth, innovation cadence, and relationships with major rail operators:
-
Plasser & Theurer (Vienna, Austria) — a longstanding leader in tamping, ballast cleaning and autonomous track maintenance systems. Recent field trials validating autonomous tamping underscore their role in operationalizing night-time automation.
-
Loram Maintenance of Way (Hamel, Minnesota, USA) — known for rail grinding and reprofiling systems; their introduction of AI-powered grinding demonstrates how sensor fusion and pattern optimization can deliver measurable efficiency uplifts.
-
Enviri Corporation (Harsco Rail) (Philadelphia, USA) — a significant provider of tampers and spot-maintenance vehicles, with a business model leaning into utility machines and serviceability.
-
MATISA (Crissier, Switzerland) and ROBEL (Freilassing, Germany) — both with deep expertise in tampers and ballast regulators, and strong footholds in Europe’s maintenance ecosystems.
-
Speno (Geneva, Switzerland) and GEATECH (Altedo, Italy) — specialists in grinding and reprofiling technologies that complement broader maintenance machine portfolios.
-
Strukton Rail , Sinara Transport Machines , CRRC , and Wabtec/Nordco — each plays a strategic role across track renewal, heavy track machinery and inspection equipment, with CRRC particularly influential in high-volume markets.
Collectively, market concentration indicates a competitive environment where top firms capture a majority of revenue, yet pockets of opportunity exist for nimble challengers and regional specialists—especially where customization, service delivery and local compliance matter.
Regulatory, Cost and Workforce Dynamics to Monitor
-
Raw material volatility: Steel price swings are pressuring OEM margins and forcing procurement reconsiderations. Tactical hedging and alternative material engineering will be decisive.
-
Labor and skills: Shortages of skilled maintenance labor are increasing demand for automation and remote-operation features. Workforce upskilling programs tied to machine sales can accelerate adoption.
-
Standards fragmentation: Divergent homologation rules across regions remain a barrier to scalable exports. A deliberate compliance strategy—targeting harmonization pathways and type-approval roadmaps—can materially shorten market entry timelines.
-
Energy policy impact: Energy efficiency and fuel-switching policies are shaping product roadmaps and procurement criteria. Anticipatory product development around hybrid and electric powertrains is becoming a baseline requirement for competitive bids.
Practical, High-Impact Recommendations for 2026
-
Adopt a two-track investment posture: accelerate pilots for autonomy and AI while maintaining a parallel program for low-risk, high-ROI platform upgrades that improve retrofitability and serviceability.
-
Lock in strategic supply agreements and material hedges to stabilize margins; simultaneously invest in design-for-material-efficiency to reduce sensitivity to raw-material cycles.
-
Pursue outcome-based commercial models with key operators—performance-linked warranties, uptime SLAs and shared-savings mechanisms—which increase stickiness and predictable revenue.
-
Accelerate cross-industry partnerships with AI and sensor firms to compress time-to-market for condition-based systems and digital services.
-
Evaluate M&A or JV plays selectively: targets that provide digital capabilities, regional market access, or niche mechanical technologies can be accretive more quickly than broad-spectrum consolidation.
What PW Consulting’s Report Delivers
This study is designed as an operator- and OEM-ready playbook. It includes:
-
Market sizing and five-year-plus forecasts (historical 2020–2025 base and 2026–2032 projections), including scenario-variant outputs aligned to policy and material-cost sensitivities.
-
Competitive benchmarking across product classes, with capability matrices, go-to-market mapping, and partner-ecosystem profiles.
-
Technology roadmaps and adoption curves for autonomy, AI-enabled maintenance, and powertrain electrification—paired with practical procurement decision frameworks.
-
Regional opportunity diagnostics and a homologation-risk matrix to inform export strategies (note: detailed sub-segment allocations and per-region financial breakouts are available in the full report).
-
Actionable playbooks: pilot design templates, OPEX vs CAPEX optimization tools, and M&A screening criteria tailored for rapid decision-making in 2026.
Concluding Perspective: From Data to Decisions
In 2026, railway maintenance machinery stakeholders confront a landscape where technology, regulation and cost dynamics converge to reward rapid but disciplined action. The market’s steady growth (a multi-year CAGR near 5.8%) and the demonstrated efficacy of new automation and AI-equipped systems create a window for firms that can execute pilots, lock in service revenue, and de-risk supply chains.
PW Consulting’s study does more than quantify the market: it translates momentum into concrete choices—what to pilot, where to partner, which capabilities to acquire, and how to structure deals to capture the upside while insulating downside. For leaders who must present investment cases, that translation is the difference between reactive procurement and proactive value creation.
Next Steps
If your 2026 plan includes fleet renewal, digitalization, or strategic M&A, our full Railway Maintenance Machinery Market report provides the proprietary segment analytics, supplier scorecards and scenario tools you need to move from intent to implementation. Access the full intelligence pack to unlock the detailed sub-segment economics and region-specific deployment playbooks that are intentionally withheld from this briefing to protect the competitive advantage contained in the complete study.
For detailed analysis of this topic, please visit the official page: Railway Maintenance Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com