

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Catheters Market to reach USD 51.8 Billion by 2032 at 6.8% CAGR

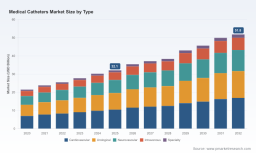
Medical Catheters Market — Strategic Imperatives for 2026 Decision‑Makers
The medical catheters market is moving from steady expansion into a period of strategic consolidation and technology-driven differentiation. Our latest market model — anchored on a 2025 base year and projecting through 2032 — shows the global market expanding at a compound annual growth rate of 6.8% across the forecast window. After growing from roughly USD 21.5 Billion in 2020 to USD 32.1 Billion in 2025, the market is modeled to surpass USD 35 Billion in 2026 and continue to expand toward the mid‑50s by 2032. For executives making resource allocation, portfolio prioritization, or M&A decisions in 2026, these topline dynamics signal both predictable scale opportunities and concentrated pockets of disruption that require finely tuned responses.
Medical Catheters Market
Why this study matters now
-
Converging regulatory and reimbursement inflection points. Standards and payer policies updated in 2025–2026 (including revised ASTM standards for urethral catheters and emergent Medicare coding for novel catheter‑based therapies) are reshaping product design requirements and economics of care.
Medical Catheters Market -
Accelerating neurovascular and ischemic stroke innovation. New clearances and product launches in 2025–2026 have expanded device options for neurovascular access and aspiration, changing procedural workflows and physician preferences.
Medical Catheters Market -
Supply‑side visibility and risk. Recent device discontinuations and FDA shortage listings have highlighted fragility in certain catheter supply chains, especially for specialized disposables — an operational risk that can materially affect hospital purchasing strategies and vendor contracting.
-
Market concentration creates leverage — and vulnerability. The sector exhibits a degree of concentration among a handful of global OEMs, which amplifies the strategic importance of partnerships, differentiated IP, and route‑to‑market execution for mid‑caps and challengers.
What PW Consulting’s Medical Catheters Market Report delivers
This study is designed as a practical, executable toolkit for 2026 strategy formation. It combines a robust market model with playbooks, decision frameworks, and commercial assets you can operationalize immediately. Key deliverables include:
-
Topline market sizing and a granular forecasting engine (2026–2032) delivered in Excel for custom scenario-testing and M&A diligence. The forecast is informed by procedure‑level drivers, demographic trends, device replacement cycles and technology adoption curves.
-
Segment and use‑case analyses that translate clinical trends into revenue and margin impact across Type, Application and Region — available in full in the licensed report. (Note: this introduction intentionally omits detailed split figures to preserve the full report’s strategic value.)
-
Competitor ecosystem maps, strength/weakness matrices and CRx concentration context to help you position products, anticipate competitive moves, and prioritize account strategies.
-
Regulatory and reimbursement playbook that decodes recent standards and coding changes and maps evidence generation pathways to commercial outcomes.
-
Manufacturing and supply‑chain risk assessment, with dual‑sourcing recommendations, critical‑component heatmaps and cost‑to‑recover scenarios for shortage events.
-
Commercial go‑to‑market playbooks for hospitals and ASC channels, pricing sensitivity models, and contracting templates for value‑based arrangements and tender processes.
-
M&A and investment scoring tools — target screens, synergies, and downside protection checklists tailored for serial acquirers and private equity sponsors.
Competitive landscape — patterns that determine winners
The market is led by a mix of global medtech majors and specialist manufacturers. The competitive field is best understood as multi‑tiered: large diversified OEMs maintain scale, distribution breadth and clinical relationships; focused innovators compete on specialist access, coating and delivery technologies; and regional manufacturers seek cost‑efficient commodity supply plays. The market’s CR3 and CR5 concentration metrics indicate that the top three and top five players command a meaningful share of revenue — a structural feature that shapes procurement dynamics and partner selection.
-
Medtronic sits as a broad leader with deep capabilities in neurovascular, cardiac and peripheral vascular catheters, leveraging integrated platforms and physician relationships to defend share in complex procedures.
-
Boston Scientific capitalizes on electrophysiology and structural heart portfolios; its mapping and access devices make it a preferred partner for complex cardiac interventions where integrated workflow matters.
-
BD and other large supply‑focused firms combine clinician‑preferred disposable lines with scale manufacturing, positioning them strongly for hospital formulary penetration and cost‑sensitive categories.
-
Specialists such as Terumo, Cook Medical, Merit Medical and Coloplast differentiate on materials, hydrophilic coating expertise and procedure‑specific designs that meet clinician ergonomics and patient‑safety needs.
-
New entrants and emerging vendors (including firms that recently secured regulatory clearances and product family expansions in 2025–2026) are exerting increasing pressure in neurovascular and stroke applications, where single‑use performance and delivery compatibility are highly prized.
Recent developments with strategic implications
-
Regulatory clearances and product launches in 2025–2026 have accelerated adoption pathways for neurovascular access and aspiration technologies. These launches expand clinician choice and put a premium on compatibility and clinical data for market access.
-
Updates to manufacturing and material standards for urethral catheters (ASTM standard updates) raise compliance costs in the near term but reduce clinical variability and risk over time — favoring firms with mature quality systems and scale manufacturing.
-
FDA shortage listings and device discontinuations have sharpened hospital procurement strategies; providers now prefer vendors that can demonstrate reliable supply, inventory buffers and transparent contingency plans.
-
Medicare and payer coding decisions (including targeted add‑on payments for new catheter‑based therapies) materially affect economic equations for high‑value interventional devices and should be central to launch economics and value dossiers.
Technology, materials and clinical trends to monitor
Two intersecting technology themes are shaping winners and losers:
-
Materials and coatings: hydrophilic coatings and medical‑grade silicones remain foundational for reducing friction, improving patient comfort and lowering infection risk — and they influence reimbursement pathways for intermittent and long‑term catheters.
-
Procedure‑specific delivery systems: miniaturized access catheters, aspiration systems for stroke care, and single‑use flexible scopes are shifting clinical workflows and creating opportunities for bundled procedural solutions rather than commodity disposables.
Strategic recommendations for 2026 (executive checklist)
-
Prioritize portfolio triage: concentrate R&D and go‑to‑market investment on procedural niches with favorable reimbursement tailwinds and high clinical switching costs (e.g., neurovascular and interventional stroke adjuncts).
-
Invest in compliance and standards readiness: update design controls and supplier qualifications to align with new ASTM and regional standards; document changes to ensure timely market access.
-
Strengthen supply resilience: implement dual sourcing for critical components, maintain strategic inventory at regional hubs, and model shortage scenarios as part of contract negotiations with health systems.
-
Build evidence and reimbursement pathways in parallel: plan clinical and health‑economics studies to support coding, payment and hospital value propositions rather than only regulatory clearance.
-
Be selective with M&A: target bolt‑on technology that fills a procedural gap or materially improves margin through differentiated IP or manufacturing efficiency rather than volume alone.
-
Commercially, focus on clinician workflow integration and total cost of care metrics — suppliers that can demonstrate OR time savings, reduced complications, or faster discharges will capture preferred tier status.
How PW Consulting supports your 2026 agenda
For 2026 decision cycles, our report and advisory services provide the empirical foundation and tactical playbooks required to execute under uncertainty. Clients receive:
-
A downloadable forecasting model with scenario toggles for pricing, adoption speed, supply disruptions and reimbursement changes.
-
Vendor scorecards and a competitive reaction matrix to guide negotiation strategy and M&A screening.
-
Regulatory and clinical evidence roadmaps tailored to product classes and target geographies, including payer engagement approaches and coding timelines.
-
Workshops to translate market data into 90‑day action plans for commercial, R&D and operations teams.
In this “trailer” we have highlighted the structural trends, regulatory inflection points and competitive contours that will matter most in 2026. To access the full dataset, detailed segmentation, competitor benchmarking tables, and the interactive Excel forecast model — including the granular splits by Type, Application and Region — download the complete Medical Catheters Market report from PW Consulting’s insights portal or contact our team for a tailored briefing. The full report contains the precise segment-level intelligence, evidence frameworks and executable templates that your strategic and commercial teams will need to convert market growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Medical Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com