

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lumpectomy Market to Reach USD 260M by 2032 at 5.0% CAGR

Lumpectomy Market 2026: Strategic Imperatives from PW Consulting’s Deep-Dive Preview
Executive summary
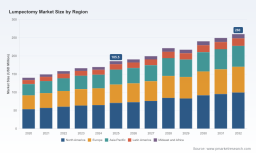
The lumpectomy ecosystem is entering a phase of steady, measurable expansion driven by converging advances in intraoperative imaging, targeted localization, and data-driven margin assessment. Our PW Consulting analysis — anchored on a 2025 base year and a 2026–2032 forecast horizon — finds the global lumpectomy market growing at a mid-single-digit CAGR (5.0% through the forecast window), with total market value increasing materially from the early 2020s to the end of the decade. Concentration metrics indicate a market where a handful of innovators shape technology adoption and clinical pathways (CR3 ~65%, CR5 >80%), creating both barriers and focused opportunity zones for entrants and incumbents alike.
Lumpectomy Market
Why this study matters for 2026 corporate decision-making
2026 will be the inflection year for several strategic choices: whether to invest in clinical evidence for intraoperative imaging, pursue partnerships to integrate localization and margin assessment, or prioritize commercial rollout in payor-constrained geographies. Our market model quantifies the market’s trajectory and cadence, but — more importantly — the research decodes the commercial levers that will convert clinical novelty into sustainable revenue. For executives preparing budgets, M&A committees evaluating strategic targets, and commercial teams plotting launch sequences, the report delivers a synthesis of evidence, regulatory timing, reimbursement levers, and competitive positioning tailored for actionable 12–24 month plans.
Lumpectomy Market
Market trajectory: fundamentals and what the numbers tell you
Over the historical window we trace continued expansion from the early 2020s into 2025. The base year (2025) anchors a market that has matured past early-adopter dynamics: product pathways have moved from feasibility to initial commercialization, enabling a predictable ramp. From 2026 through 2032, the market is projected to compound at roughly 5.0% annually, reaching a materially larger installed base by the end of the forecast horizon. These headline dynamics are driven by three structural forces:
Lumpectomy Market
-
Technology substitution: intraoperative imaging and localization tools are shifting the standard of care from blind excision toward image- and marker-guided conservation.
-
Regulatory and reimbursement momentum: recent device approvals and coding decisions have reduced adoption friction, though payor heterogeneity remains a significant gating factor.
-
Consolidation of clinical workflows: hospitals and surgical centers are gravitating to bundled intraoperative solutions that reduce re-excision rates and downstream costs.
Competitive landscape — mapped for strategic action
The lumpectomy competitive set is compact but technologically diverse. Leaders are differentiated by modality (optical coherence tomography, fluorescence imaging, magnetic localization, radiofrequency spectroscopy, and patient-specific 3D guidance) and by how they integrate hardware, software, and consumables into the OR workflow. A short taxonomy of core players and strategic postures:
-
Perimeter Medical Imaging AI, Inc. — notable for an intraoperative OCT platform enhanced with AI. Its recent FDA premarket approval (March 2026) for an AI-enabled imaging device marks a pivotal regulatory milestone that will reshape adoption calculus for real-time margin assessment.
-
Lumicell, Inc. — commercialized a fluorescence-guided adjunct with regulatory clearance and HCPCS coding following its 2024 approval; its approach emphasizes adjunct visualization to reveal residual disease in the cavity.
-
Endomag (Hologic) — occupies the localization niche with a mature magnetic-seed-based platform that reduces logistical complexity of preoperative localization and appeals to centers focused on workflow efficiency.
-
Dilon Technologies — has a legacy in radiofrequency spectroscopy for margin assessment, positioning it as an incumbent with installed clinical recall and a path to incremental feature updates.
-
Cairn Surgical — advancing a patient-specific 3D-printed locator to tighten excision accuracy; a De Novo submission in March 2026 highlights the near-term regulatory potential for bespoke surgical guidance.
For strategy teams, this landscape implies three immediate implications: prioritize interoperability with the modalities hospitals already use; accelerate evidence generation that ties device use to measurable reductions in re-excision and OR time; and evaluate alliance models with distributors or existing OR systems vendors to overcome procurement inertia.
Regulatory, reimbursement and standards dynamics
Regulatory events in early 2026 materially change the playing field. The first AI-enabled intraoperative imaging device received FDA PMA approval in March 2026 — a watershed that validates AI-augmented, real-time margin assessment and will reduce regulatory uncertainty for similar solutions. Concurrently, devices that achieved earlier clearances have started to secure coding or temporary reimbursement pathways. One commercially available fluorescence-guided system obtained a permanent HCPCS code following its market launch, smoothing the way for hospital adoption in supported geographies.
Reimbursement remains fragmented. Common procedure coding (e.g., CPT 19301 for partial mastectomy/lumpectomy) provides a billing anchor, but provider reimbursement rates vary by payer and have shown long-term real-term erosion in some public schedules. That creates a dual challenge: providers seek devices that demonstrably reduce total episode cost, while vendors must design pricing and evidence packages that align with institutional budget constraints.
Clinical and commercial dynamics that determine winners
-
Evidence linkage: the fastest-adopted technologies will be those with robust prospective data showing reduction in positive margins, lower re-excision rates, or shorter OR times. Payors and health systems prioritize hard outcomes over surrogate endpoints.
-
Workflow fit: devices that integrate into existing imaging stacks, sterilization routines, and OR timelines face far less adoption resistance than disruptive systems requiring new SOPs.
-
Consumables and recurring revenue: models that rely on single-use agents or disposables must balance clinical value with predictable unit economics — a key negotiation point with procurement teams.
-
Service and training: seller success increasingly tracks with the availability of implementation services, surgeon training, and post-sale analytics to demonstrate ROI.
Practical, tactical recommendations for 2026
For executives preparing roadmaps this year, PW Consulting highlights a prioritized set of actions:
-
Invest in targeted clinical trials that answer payor-centric questions (cost per avoided re-excision, downstream radiotherapy usage, length-of-stay impact).
-
Secure coding strategies early: engage with payors and specialty societies to translate clinical benefit into durable reimbursement pathways.
-
Pursue integration partnerships: imaging vendors, OR platform providers, and surgical instrument OEMs can accelerate market access through bundled offerings.
-
Evaluate M&A or minority investments to acquire complementary modalities that broaden addressable use cases (e.g., combining localization with margin assessment).
-
Design differentiated commercial models for high-volume academic centers vs community hospitals — one size will not fit all.
What PW Consulting’s full report delivers (practical contents)
The full Lumpectomy Market report is structured to convert insight into action. Key deliverables include:
-
Market model and forecast (2026–2032) with scenario analysis and sensitivity to reimbursement shifts and adoption inflection points.
-
Technology maps that compare modalities across clinical impact, workflow disruption, cost profile, and maturity.
-
Company profiles and competitive positioning matrices for the leading innovators and select incumbents, including assessed strengths, strategic gaps, and go-to-market posture.
-
Regulatory and reimbursement playbooks that outline likely coding pathways, evidence thresholds, and stakeholder engagement strategies.
-
Commercialization recommendations: segmentation of go-to-market approaches, sample pricing frameworks, and distributor/partner prioritization lists.
-
Executive decision frameworks for M&A diligence, investment thesis construction, and 12–24 month roadmaps.
To respect competitive sensitivity and to preserve the strategic value for subscribers, granular regional and application-level splits are intentionally withheld in this preview; the full intelligence package contains those detailed matrices and downloadable model files.
How to use this intelligence in board and budget cycles
Position the report as the central input for three near-term governance processes: capital allocation (device development, clinical trials), commercial rollout (target geographies and customer segments), and corporate development (M&A pipeline screening). Use the model’s scenario outputs to stress-test revenue projections under differing reimbursement and adoption timelines and to prioritize investments that de-risk early-commercialization phases.
Closing guidance — the strategic horizon to watch
Two themes will dominate decision-making as 2026 unfolds: first, the conversion of regulatory approvals into commercial reality — approvals reduce uncertainty but do not guarantee uptake without aligned reimbursement; second, the economics of adoption — purchasers will favor solutions demonstrably lowering total episode cost or markedly improving clinical outcomes. Firms that can marry compelling clinical evidence with operational interoperability and flexible commercial models will capture outsized share in a market that is growing steadily but selectively.
Next steps
PW Consulting’s Lumpectomy Market report is designed to be a working tool for CXOs, strategy leads, and business development teams. The preview above highlights strategic implications and competitive context; full access includes detailed models, proprietary segmentation, and an actionable roadmap tailored for 2026 execution. For complete data access, scenario downloads, and to schedule a tailored briefing, please visit our report page or contact PW Consulting’s Lumpectomy Market team.
For detailed analysis of this topic, please visit the official page: Lumpectomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com