

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVD Coaters Market to Hit USD 167.8M by 2032, Growing at 6.2% CAGR

PVD Coaters Market — Strategic Brief for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a concise yet forward-looking orientation to inform boardroom decisions on Physical Vapor Deposition (PVD) coaters in 2026. This brief synthesizes macro trajectories, competitive positioning, regulatory and raw-material forces, and the tactical levers that will matter most in the immediate planning window. The companion PVD Coaters Market report provides the full datasets, segment-level analytics, and executable playbooks; this article intentionally signals depth while reserving granular tables for the full publication.
PVD (Physical Vapor Deposition) Coaters Market
Why 2026 Is a Pivotal Year
The PVD coater market is on a multi-year growth path driven by structural demand across semiconductor, automotive, aerospace, and engineered tooling segments. Using 2025 as the base year and a 6.2% compound annual growth rate (CAGR) for the forecast horizon, the market shows a consistent expansion from the prior half-decade and meaningful acceleration through the late 2020s. For executives planning capex cycles, supplier negotiations, or M&A activity in 2026, these macro dynamics create a narrow window to position for scale or strategic specialization before competitive responses consolidate advantage.
PVD (Physical Vapor Deposition) Coaters Market
Market Trajectory — What the Numbers Suggest
-
Durable mid-single-digit CAGR: A 6.2% CAGR through the forecast period implies steady demand rather than a boom-bust cycle. That profile favors investments in flexible, modular equipment that can be repurposed across adjacent applications as end markets shift.
PVD (Physical Vapor Deposition) Coaters Market -
Momentum from 2020–2025 provides a credible baseline: historical recovery and expansion create a stronger justification for multi-year investments compared with cyclical equipment markets.
-
Forecast lift through 2032 signals opportunities for technology upgrades, aftermarket services, and consumables revenue streams—areas where OEMs and system integrators can grow margins beyond initial equipment sales.
Competitive Landscape — Who to Watch and Why
The PVD coater ecosystem is moderately consolidated: the top three and top five vendors capture a meaningful share of the market while leaving room for regional specialists and niche innovators. That competitive balance produces both partnership opportunities and acquisition targets for firms seeking rapid scale or capability fill-ins.
-
VaporTech (Longmont, Colorado) — Known for advanced PVD and PECVD/DLC systems, their product breadth across batch and specialty models positions them well for industrial and consumer-facing OEMs. Their emphasis on configurable platforms supports customers demanding rapid changeovers.
-
PVD Products, Inc. (Wilmington, Massachusetts) — A historically engineering-driven supplier of magnetron sputtering, pulsed laser deposition, and thermal evaporation systems. Their capability to deliver custom production-scale solutions is an asset for contract manufacturers and specialized production lines.
-
Vergason Technology, Inc. (Van Etten, New York) — Now integrated into a larger tribology portfolio following acquisition activity, their vacuum metalizing and wear-resistant PVD systems gain new distribution and service scale under the HEF Groupe ownership.
-
Hauzer Techno Coating B.V. (Venlo, Netherlands) — Modular batch and inline systems plus digital configuration tools (recently launched) make them representative of a new breed of vendors blending hardware with cloud-enabled configuration and support.
-
Oerlikon Balzers Coating AG (Pfäffikon, Switzerland) — High-performance platforms targeted at tooling, automotive, and decorative markets; their deep installed base and aftermarket network matter for service-led business model transitions.
Recent vendor developments—such as strategic acquisitions and product-platform digitization—are reshaping competitive advantage by accelerating scale and by embedding services into equipment value propositions. Executives should view vendor roadmaps not only as procurement options but as potential strategic partners or acquisition candidates.
Operational and Supply-Chain Dynamics
PVD equipment performance is tightly coupled with supply dynamics for sputtering target materials. The availability and price volatility of materials—ranging from base metals to rare or strategically sensitive elements—directly affect operating cost, qualification timelines, and technology choice for end-users.
-
Material concentration risk: Certain high-performance target materials have geographically concentrated supply chains. Procurement diversification and strategic inventory policies can shield production from episodic shocks, but these actions require capital and lead time to implement.
-
Qualification timelines: For semiconductor and high-reliability applications, material changes trigger lengthy qualification cycles that can delay product launches and make rapid supplier swaps impractical. Buyers should weigh supplier resilience as a procurement criterion.
-
Consumables as recurring revenue: For OEMs, bundling consumable supply contracts (targets, liners, process gases) with equipment sales creates sticky revenue and mitigates buyer capex sensitivity.
Regulation, Sustainability, and Technology Shifts
Regulatory pressures and sustainability trends are accelerating the adoption of PVD as a preferred alternative in several contexts. New and evolving policies—especially in the EU and U.S.—are reshaping allowable chemistries and process emissions:
-
Environmental regulation: Phase-outs and stricter limits (including restrictions on certain hexavalent chromium processes and lower VOC limits introduced in recent regulatory cycles) are increasing the relative attractiveness of PVD solutions that avoid hazardous chemistries and effluent-heavy process stages.
-
Compliance-driven retrofits: Facilities operating legacy plating or chromium-based lines are evaluating retrofit vs. replace decisions. These capital allocation choices will drive a wave of selective modernization that favors suppliers offering low-effluent, high-throughput systems.
-
Design for sustainability: Buyers and OEMs increasingly prioritize life-cycle impacts; equipment that demonstrably reduces waste, energy consumption, and hazardous byproduct streams will secure preferential adoption in regulated and high-visibility industries.
What the PW Consulting Report Delivers (Practical, Actionable Content)
Our full PVD Coaters Market study is a practitioner’s manual for 2026 strategy. Highlights include:
-
Robust macro market sizing and forecast model anchored to a 2025 base, with scenario-level sensitivities for material shocks and policy shifts.
-
Technology deep dives comparing sputtering, evaporation, and arc processes—capability matrices, typical throughput ranges, and suitability by end-market.
-
Competitive playbooks for OEMs and service providers: capability maps, go-to-market options, and partnership archetypes that reduce time-to-revenue.
-
Capex and TCO calculators tailored to plant-level comparisons (new build vs. retrofit), including payback ranges under different utilization assumptions.
-
Supply-chain mitigation strategies focused on target-material sourcing, including supplier heatmaps and contractual structures to manage price and availability risk.
-
Regulatory impact matrix translating REACH, RoHS, EPA and other regional regulations into operational triggers and investment thresholds.
-
M&A intelligence and screen of attractive targets by capability gap, geographic footprint, and aftermarket scale.
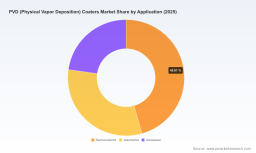
Note: the report contains the granular segmentation tables, regional and application splits, and downloadable models. In line with this brief’s “trailer” purpose, those detailed numeric slices are accessible in the full report.
Priority Strategic Recommendations for 2026
-
Near-term (0–12 months): Lock in supply agreements for critical sputtering targets and diversify sourcing geographies. Negotiate bundled consumable contracts with preferred OEMs to secure pricing and lead times. Prioritize retrofit pilots for lines that face immediate regulatory risk.
-
Medium-term (12–36 months): Invest in modular platforms that support both batch and inline operations to capture demand across decorative, automotive, and semiconductor use cases. Build service and spare-parts capability to monetize installed base and shorten payback on equipment sales.
-
M&A and Partnerships: Target regional specialists with strong local aftermarket presence or suppliers that fill material or process gaps. Consider minority investments in digital-configuration or remote-support providers to accelerate service revenue growth.
-
Regulatory Strategy: Map facility portfolios against regulatory thresholds and prioritize conversions where compliance risk and potential revenue impact are highest. Use compliance roadmaps to secure government funding or incentives where available.
Concluding Perspective
The PVD coater market in 2026 is neither a high-risk frontier nor a mature, static industry. It is a strategically inflectional market where procurement choices, supplier partnerships, and targeted investments in sustainability will produce outsized advantage over a five- to seven-year horizon. For executives, the challenge is less about whether to participate and more about how to participate: choose specialization or scale, own consumable flows or outsource them, and move fast on compliance-driven modernization before rivals consolidate customer relationships.
For boards and strategy teams preparing 2026 budgets, the full PW Consulting PVD Coaters Market report supplies the quantitative backbone—detailed forecasts, segment and regional analytics, supplier dossiers, regulatory impact mapping, and executable playbooks—to convert these strategic directions into concrete, fundable initiatives. Access the complete study to unlock the specific segment metrics, company scoring matrices, and downloadable financial models that underpin these recommendations.
To request the full report and dataset, please visit the PW Consulting market publications page or contact our analyst team for a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: PVD (Physical Vapor Deposition) Coaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com