

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrolyzer Market to Reach USD 5.45B by 2032 at 6.98% CAGR

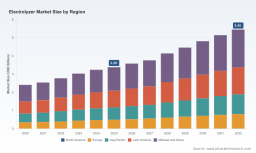
Electrolyzer Market — 2026 Strategic Brief
As corporations and investors finalize budgets and project pipelines for 2026, the choices made now about technology, partners and capital allocation will determine competitive position for the next decade. PW Consulting’s Electrolyzer Market study synthesizes proven market-sizing, scenario modeling and commercial playbooks into an operational guide for executives. At a macro level, the market for electrolyzers expanded from approximately USD 2.42 billion in 2020 to USD 3.39 billion in 2025 and — under our base case — is projected to grow to roughly USD 5.45 billion by 2032, implying a compound annual growth rate of about 6.98% across the 2026–2032 forecast window. This strategic brief highlights the study’s value to 2026 decision cycles while preserving the granular segmentation and proprietary datasets that drive our models (those detailed tables and subsegment figures are intentionally reserved for the full report).
Electrolyzer Market
Why this study matters for 2026 decisions
- Capital allocation: Selectively increasing or deferring electrolyzer investments will materially affect levelized hydrogen cost and first-mover economics; our models quantify the sensitivity to plant scale, technology choice, and CAPEX deflation paths.
- Technology selection & integration: The study clarifies where pressurized alkaline, PEM and emerging variants deliver best-fit economics across project scales and grid conditions — enabling procurement specs that reduce total cost of ownership.
- Supply-chain contracting: With manufacturing capacity ramping rapidly, timing of long-lead equipment orders, offtake clauses and warranty terms determine project outcomes; we provide contract levers and hedging strategies for 2026 commitments.
- M&A and partnership screening: For corporates seeking capability fill or scale, our deal-screening matrix prioritizes targets by technology stack, manufacturing footprint and pipeline quality.
- Regulatory and standards risk: New standards and public targets materially change compliance obligations and eligibility for subsidized support; our impact assessment aligns regulatory timelines with procurement and commissioning windows.
Report contents — practical and operational
The full PW Consulting study is deliberately operational in orientation. Key deliverables include:
Electrolyzer Market
- Market sizing and bottom-up forecasts (historical 2020–2025; forward 2026–2032) with scenario outputs for conservative, base and accelerated adoption cases.
- Transparent methodology and worked examples for LCOH (levelized cost of hydrogen) including sensitivity to CAPEX, stack lifetime, electricity mix and electrolyzer load-factor.
- Technology cost curves and roadmaps that map current offerings to anticipated performance improvements and cost deflation under different policy and manufacturing ramp scenarios.
- Supply-chain mapping and bottleneck risk register, including critical component lead times, supplier concentration indices and mitigants for procurement teams.
- Competitive benchmarking and procurement playbooks (RFP templates, acceptance criteria, service-level KPIs and financing structures).
- Commercial due diligence dossiers for top suppliers and project developers, plus actionable M&A screening filters and synergy calculators.
- Project-level commissioning checklists, commissioning acceptance tests and an insurance/risk-transfer framework tailored to electrolyzer projects.
Note: This preview demonstrates the study’s practical orientation. The full report provides the granular, downloadable datasets, model workbooks and regional/application splits that underpin the recommendations — intentionally withheld here to encourage direct engagement with the complete deliverable.
Electrolyzer Market
Market dynamics shaping 2026 strategy
- Manufacturing scale-up and learning curves: Global electrolyzer manufacturing capacity reached an estimated 61 GW by mid‑2025, creating both price pressure and lead-time distortion; firms that secured capacity early captured cost advantage in 2024–2026 procurement cycles.
- Policy targets compress timelines: Public targets and technical goals — notably the U.S. Department of Energy’s updated 2026 target for liquid alkaline electrolysis aimed at enabling hydrogen production at roughly $2/kg — force accelerated validation and piloting for technologies that can meet those cost thresholds.
- Standards and safety: The International Organization for Standardization’s new electrolyzer safety standard (published July 2025) raises compliance imperatives for equipment design, factory acceptance testing and site commissioning windows — a material consideration when scheduling first-of-a-kind projects.
- Economies of scale favor pressurized designs at megawatt+ scale: Manufacturer announcements indicate pressurized alkaline systems deliver significant installed-cost reductions for high‑power projects — a structural advantage for industrial offtakers targeting triple-digit megawatt deployments.
- Market concentration: The supply base shows meaningful consolidation at the top end — our concentration indices show that a limited set of suppliers controls the dominant share of large-system backlog — creating supplier power in pricing and project delivery. This dynamic increases the value of multi-supplier strategies and firm contractual protections.
Technology pathways — trade-offs and tactical choices
Every practical deployment decision in 2026 will rest on three interdependent choices: electrolyzer technology, modular vs scale model, and integration with renewable supply and grid services. Broadly:
- Pressurized alkaline platforms are being optimized for industrial, high-capacity deployments. Manufacturer claims and product announcements indicate meaningful installed-cost benefits at scale; these platforms are rapidly moving from demonstration to 10s–100s of MW commercial projects.
- Containerized and modular alkaline systems (1 MW class) are becoming the default for fast deployments, refueling stations and early-stage demonstrations — they reduce time-to-operation but can have different lifetime and balance-of-plant characteristics compared with large plants.
- PEM systems retain advantages for flexibility and dynamic operation with variable renewables; decisions that prioritize grid services or bidding into ancillary markets should weigh PEM’s operational responsiveness against its cost trajectory.
- Stack and system innovation is accelerating: product launches in early 2026 demonstrate competitiveness across the envelope — from containerized 1 MW installs to new 50 MW outdoor-rated pressurized solutions — meaning procurement specs must be technology-agnostic and outcome-based.
Competitive landscape — who matters and why
The competitive field combines established industrial engineering houses with rapid-scale manufacturers and technology-first entrants. Key archetypes and supplier moves to watch:
- Large industrial integrators with gigawatt ambitions: Companies with established engineering, procurement and global project delivery capabilities and multi‑GW backlogs are well positioned to win large, complex industrial offtake projects where integration risk is higher.
- Focused electrolyzer OEMs advancing scale-performance: Several specialist OEMs have unveiled next‑generation pressurized alkaline platforms and larger unit ratings in early‑to‑mid 2026, signaling the move from pilot to large-scale commercialization.
- Modular & containerized system suppliers: A set of suppliers are focusing on rapid-deploy, containerized units to capture refueling, microgrid and early decarbonization projects — a valuable route to market for offtakers seeking staged scale-up.
- Regional manufacturers scaling capacity: Manufacturers in key supply geographies are expanding production and vertical integration to lower cost and secure procurement for domestic projects; this regionalization trend affects global procurement strategies.
Examples of recent moves that illustrate these dynamics:
- March 2026 — A leading Japanese OEM began installing a 1 MW-class containerized system at a hydrogen refueling site in Finland, underlining the role of modular units in near-term deployments.
- April 2026 — A German systems developer launched a 50 MW rated outdoor pressurized alkaline system targeted at industrial projects, highlighting the push toward large-unit ratings and site-optimized designs.
- May 2026 — A Norwegian OEM introduced a simplified next‑generation pressurized alkaline platform focused on cost-efficiency for renewable hydrogen, reflecting a shift to designs optimized for manufacturability.
Strategic implications and a 2026 playbook
For executives preparing decisions this year, our recommended playbook prioritizes optionality, contractual protection and staged exposure to scale risk:
- Adopt staged procurement: Start with modular deployments to derisk technology and site integration, then scale to larger pressurized units once demonstrated performance and supply reliability are proven.
- Negotiate capacity protections: Securing manufacturing slots and logical options in long‑lead contracts is often as valuable as price alone; include performance milestones tied to manufacturing ramp.
- Insist on outcome-based specs: Define warranties, degradation curves and performance KPIs rather than prescriptive stack architectures — this preserves flexibility as technologies evolve.
- Hedge raw-material and logistics risk: Include pass-through triggers and hedging instruments where rare materials and long supply chains create exposure to cost shocks.
- Prioritize integration economics: Model the combined renewable-electrolyzer-PTX (power-to-x) system — not isolated electrolyzer CAPEX — to understand LCOH sensitivity and grid interaction value.
- Prepare for standards compliance: Map ISO and national certification requirements into procurement and commissioning timelines to avoid costly retrofits.
- Assess M&A targets on deliverable pipelines: For corporates pursuing inorganic growth, prioritize sellers with validated manufacturing processes, backlog and service capability over pure IP plays.
How PW Consulting supports execution
Our full Electrolyzer Market report couples the strategic narrative above with the operational instruments that teams need in 2026: downloadable model workbooks, supplier scorecards, procurement templates, regulatory impact maps and prioritized deal targets. Clients subscribing to the full study receive an interactive forecast model, sensitivity dashboards calibrated to their project assumptions, and a workshop package to align commercial, technical and legal stakeholders ahead of procurement decisions.
To access the full dataset, granular segmentation, and bespoke scenario outputs that underpin the recommendations summarized here, please consult the PW Consulting report page for the Electrolyzer Market (the preview intentionally omits subsegment tables and proprietary datasets). For teams ready to translate these insights into 2026 project approvals, we offer tailored advisory engagements, rapid procurement audits, and transaction due diligence focused on electrolyzer technology and supply-chain risk mitigation.
For detailed analysis of this topic, please visit the official page: Electrolyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com