

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
RFoF Market to Reach USD 1,085.62M by 2032 at 8.57% CAGR – PW Consulting

RF-over-Fiber (RFoF) Market: Strategic Outlook for 2026 Decision-Makers
Executive teaser
The RF-over-Fiber (RFoF) market is moving from tactical niche deployments toward strategic infrastructure status in telecom, defense, aerospace, and broadcast architectures. Our PW Consulting market study—anchored on a 2025 base year and a seven-year forecast to 2032—documents a clear expansion path: the addressable market has expanded steadily through the historical period (2020–2025) and is projected to grow at a compound annual growth rate (CAGR) of 8.57% over the 2026–2032 forecast window. By 2026 the market enters a higher-velocity phase, and by 2032 total market scale more than doubles relative to its early-decade baseline. For executives making capex, R&D, and M&A decisions in 2026, RFoF is no longer experimental—it is a category with quantifiable economics and operational levers. This article highlights the study’s strategic value while intentionally holding back the granular segment tables and proprietary vendor scoring housed in the full report.
RF-over-Fiber (RFoF) Market
Why 2026 is a strategic inflection
-
Convergence of infrastructure policy and technology. Public programs that prioritize fiber-based backhaul, combined with increasing demand for secure, low-EMI links in defense and space programs, are aligning regulatory and procurement incentives toward RFoF. These policy forces shorten the runway for fiber-centric deployments and increase the return on early investments in RFoF-enabled architectures.
RF-over-Fiber (RFoF) Market -
Commercial acceleration. Mobile densification, higher-band 5G rollouts, and expanded satellite ground segments are driving demand for solutions that transport wideband RF signals over long distances with low loss and minimal electromagnetic interference.
RF-over-Fiber (RFoF) Market -
Cost arbitrage and lifecycle economics. In many deployment scenarios RFoF achieves materially lower infrastructure cost per connected endpoint than satellite or long-haul microwave alternatives, particularly when measured across multi-year lifecycle and regulatory compliance costs.
-
Rising integration vectors. Drone platforms, distributed antenna systems, and centralized radio architectures are increasingly designed with RFoF as the preferred transport layer, opening new, cross-sector use cases.
Market trajectory (high level)
Our topline analysis shows a steady historic climb from the early-2020s into the mid-decade, followed by an accelerated forecast path driven by both commercial and defense demand. With 2025 as the analytical base year, the market’s projected CAGR of 8.57% through 2032 implies a meaningful uplift in absolute market scale and capital flows into component, subsystem, and integrated-systems segments. This trajectory substantiates near-term investment in manufacturing scale and longer-term bets on platform-level integration.
Market structure and competitive dynamics
The RFoF market exhibits moderate concentration: the three largest suppliers account for a substantial share of the market, and the top five firms consolidate the majority of revenue—creating an environment where established incumbents maintain pricing power in core segments while specialized vendors capture premium niches. This structure supports multiple strategic plays for corporates: partner with incumbents for scale deployments, or back specialists to win high-margin, application-specific contracts.
Key vendor landscape (strategic read)
-
HUBER+SUHNER AG (Switzerland) — Strengths: deep aerospace and defense credentials, broad RFoF product lines, and high-frequency capability up to tens of GHz. Strategic implication: preferred supplier for regulated, mission-critical programs where proven qualification and lifecycle support are decisive buying criteria.
-
RFOptic Ltd. (Israel) — Strengths: focused product suites for 5G, C-band, and EW applications, with new high-frequency “Ultra” offerings. Strategic implication: attractive partner for integrators pursuing higher-frequency, performance-differentiated solutions in congested RF bands.
-
Optical Zonu Corporation (United States) — Strengths: carrier-grade transceivers and a cross-domain perspective (wireless, data centers, aerospace, drones). Strategic implication: a go-to for converged deployments where operator-grade reliability and platform integration matter; also an early thought leader on drone-enabled RFoF use cases.
-
ViaLite Communications (United States) — Strengths: long-distance links and satcom-focused systems. Strategic implication: suitable for satellite ground-segment and long-haul telemetry, especially where single-provider accountability for long-distance transport is needed.
-
Global Foxcom (Israel) — Strengths: wideband transport systems for distributed satellite and broadcast architectures. Strategic implication: relevant for system integrators deploying distributed RF networks requiring cost-efficient, large-scale signal transfer.
-
Wisycom (Italy) — Strengths: innovative antenna matrices and portable RFoF solutions. Recent developments include an April 2026 wideband MATF antenna matrix launch and a firmware-enabled expansion of multichannel IFB capability. Strategic implication: strong partner for complex broadcast and audio-over-RF installations where flexibility and on-site configurability are differentiators.
-
Pharad LLC (United States) — Strengths: high-dynamic-range photonic transceivers and aviation/SATCOM focus. Strategic implication: offers performance advantages in environments that demand high linearity and extended dynamic range, such as avionics and critical SATCOM uplinks.
These vendor profiles are summary-level. The full PW Consulting report provides vendor scorecards, product capability matrices, certification status, and procurement advisories to support vendor selection and negotiation—material we exclude here to preserve the value of the full dataset.
Regulatory and programmatic tailwinds & headwinds
-
Policy tailwinds: National broadband initiatives that emphasize fiber backhaul (notably policy moves since 2024) and defense/space program standards increasingly favor RFoF for its low-EMI characteristics. These create near-term procurement pipelines for both commercial and government buyers.
-
Regulatory complexity: A heterogeneous global compliance landscape—varying spectrum licensing rules, signal-level thresholds, and EMC requirements—adds procurement friction and extends sales cycles for multi-jurisdiction vendors. Dual-compliance strategies are cost-intensive but often required for cross-border deployments.
-
Standards and assurance: NATO and leading space launch providers are increasingly referencing RFoF in interface expectations, raising the bar for supplier qualification, testing, and documentation.
Report practicalities — what’s inside (high level)
PW Consulting’s RFoF market study is designed as a hands-on strategic playbook for operators, vendors, and investors. Key deliverables include:
- Topline market sizing and multi-scenario forecasts anchored to a 2025 base year (historical back to 2020; forward to 2032).
- Policy and regulatory impact assessments with actionable compliance checklists and procurement timelines.
- Vendor benchmarking and procurement scorecards (product capabilities, certification status, TCO indicators).
- Deployment economics: cost models and TCO calculators for common architectures (centralized radio, distributed antenna, satellite ground segments), plus sensitivity analyses for spectrum fees and fiber access costs.
- Technology roadmaps and interoperability matrices to guide R&D prioritization and standards engagement.
- Go-to-market playbooks for incumbents and challengers, including channel strategies, partnership archetypes, and M&A screens.
- Risk matrices covering regulatory, supply chain, and geopolitical scenarios, with mitigation playbooks and contract-language templates.
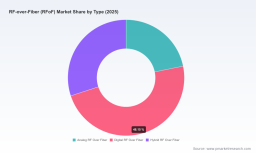
Note: the public overview intentionally omits our full breakouts by region, application, and type. Those granular forecasts and the proprietary vendor scoring methodology are available in the subscriber report.
Strategic actions for 2026—what to do now
-
Audit infrastructure roadmaps against RFoF readiness: map existing fiber routes and latency budgets, and identify where RFoF can immediately substitute or augment microwave and satellite links to reduce cost and improve performance.
-
Prioritize regulatory-first procurement: for programs crossing borders, lock in certification and test plans early. Expect longer lead times for dual-compliance items and embed that into procurement schedules.
-
Segment vendor engagement: for scale deployments prefer incumbents with system-level warranties; for performance-critical or experimental programs select specialist vendors with demonstrable high-frequency or high-dynamic-range credentials.
-
Start small, plan big: deploy targeted pilots that validate integration, lifecycle cost assumptions, and maintenance models—then scale via standardization and repeatable bundles.
-
Use RFoF as a strategic wedge in product roadmaps: integrate RFoF-ready interfaces into next-generation radio units and satellite ground stations to capture lifecycle lock-in and post-sales service pools.
-
Prepare M&A screens: with moderate market concentration and accelerating growth—as evidenced by the market’s near-term CAGR—bolt-on acquisitions can accelerate capability and geographic reach faster than organic scaling.
Why PW Consulting’s study matters to your 2026 plan
Decisions made in 2026 about network architecture, supplier selection, and regulatory compliance will shape competitive position for the remainder of the decade. Our study translates market growth assumptions (8.57% CAGR across the forecast window), concentration dynamics, and regulatory vectors into executable strategies—backed by deployment-level cost models, vendor scorecards, and risk mitigations. The report is deliberately practical: it does not stop at “what will happen,” it prescribes “what to do” with timing, budgets, and go/no-go triggers aligned to realistic procurement cycles.
Next step
For executive teams preparing 2026 budgets and mid-term strategic plans, the full PW Consulting RFoF report contains the granular forecasts, vendor rankings, and playbooks required to convert insight into action. The summary above signals the scale and levers of opportunity; the complete study provides the operational blueprints—available to subscribers and clients seeking a rapid, low-risk path to deploy RFoF at scale.
For detailed analysis of this topic, please visit the official page: RF-over-Fiber (RFoF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com