

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PET Market to Reach USD 66.1B by 2032 at 6.2% CAGR

Polyethylene Terephthalate (PET) Market 2026: Strategic Imperatives for Decision-Makers
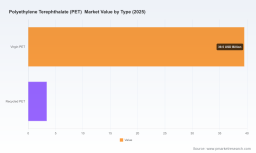
As global supply chains recalibrate and sustainability imperatives mature, the PET (Polyethylene Terephthalate) market is re-entering a period of strategic realignment. PW Consulting’s latest PET market study — base year 2025, historical window 2020–2025, with a forecast horizon through 2032 — synthesizes market-scale dynamics, raw-material shocks, regulatory shifts, and competitive positioning to equip executive teams for high-stakes decisions in 2026. The market we modelled expands from approximately USD 42.9 Billion in 2025 to an expected USD 66.1 Billion by 2032, with a compound annual growth rate of 6.2% across the forecast window. This briefing highlights the study’s strategic value while reserving the granular segment detail for the full report.
Polyethylene Terephthalate (PET) Market
Why this report matters for 2026 decisions
-
Timing of capital allocation: With a clear trajectory from 2025 to 2032, the report helps capital planners decide on greenfield projects, debottlenecking, or strategic pauses. We show when IRR sensitivity to feedstock pricing and utilization shifts becomes decisive.
Polyethylene Terephthalate (PET) Market -
Feedstock and margin preservation: Volatility in purified terephthalic acid (PTA) and monoethylene glycol (MEG) has become a driver of short- and medium-term margin compression. Our modelling ties PTA/MEG price scenarios to EBITDA sensitivities across plant types.
Polyethylene Terephthalate (PET) Market -
Regulatory and trade risk: Tariff regimes and recycling mandates can re-price markets faster than capacity additions. The report lays out plausible regulatory outcomes and the operational responses that preserve market access and margin.
-
Competitive advantage from circularity: Advanced mechanical and chemical recycling investments, and differentiated rPET product stacks, are now strategic levers. The study quantifies when recycled content becomes not just compliant but profitable under likely cost curves.
Market trajectory and what the headline numbers conceal
The market expanded strongly through the 2020–2025 period and enters the forecast with momentum: our model estimates USD 42.9 Billion in 2025 and projects steady growth to USD 66.1 Billion by 2032 at a 6.2% CAGR. These headline figures mask heterogeneous dynamics beneath the surface — geographic pockets of faster demand, application-level bifurcation between commodity and specialty use cases, and materially different margin structures between integrated and merchant producers.
Importantly, the market is neither perfectly consolidated nor atomistic: the top three firms account for a material share of the market and the top five consolidate a majority position. This concentration shapes pricing power, regional response to disruptions, and the strategic value of scale in downstream customer relationships.
Key forces shaping PET through 2032
-
Raw-material volatility: PTA and MEG price swings in 2025–2026 have translated into sudden cost pressure for many producers. The report includes price-path scenarios (base, upside, downside) and maps them to plant-level break-evens to highlight short-run vulnerability and long-run hedging needs.
-
Trade policy and tariffs: Recent reintroduction and strict application of reciprocal tariffs in key markets altered competitive dynamics in late 2025. The report evaluates how tariff-induced arbitrage opportunities and import-cost shocks re-route flows and affect utilization by region.
-
Circularity and advanced recycling: Large upstream investments in advanced recycling capacity and scale-ups in mechanical recycling are closing the technology-cost gap. The report models the tipping points where recycled content becomes both a compliance advantage and a differentiator for premium customers.
-
Customer segmentation evolution: Major consumer-packaged-goods companies are intensifying recycled-content mandates, creating premiumization pathways for rPET and novel copolyesters. The study maps these demand signals to product-level value creation opportunities.
-
CAPEX and capacity cycling: Facility closures and resumptions in 2025–2026, including high-profile project pauses and restarts, keep near-term capacity growth lumpy. We provide an incremental capacity tracker and scenario view on how these moves alter near-term supply balance.
Competitive landscape — what to watch
The PET industry features global incumbents with highly integrated value chains and regional players with localized advantages. The full report includes company profiles, strategic intent assessments, and scenario-based competitive positioning heat maps. Highlights:
-
Indorama Ventures: The world-scale incumbent with multi-million-ton capacity and a broad product mix across virgin, recycled, and bio-based PET. Their global footprint and ongoing large-scale projects — including a near-complete facility pause/resume in the United States — are pivotal to global capacity dynamics.
-
Alpek and regional producers: Large integrated resin producers with multi-country operations that can flex production between bottle-grade and industrial PET. Operational adjustments, including facility closures announced in 2025, demonstrate how regional capacity moves can re-balance local markets quickly.
-
Integrated petrochemical players (e.g., SABIC, Reliance): Their vertical integration into PTA/MEG affords feedstock cost advantages in integrated markets; this vertical control is a competitive moat in price-stressed environments.
-
Specialty and differentiated producers (Eastman, M&G, Far Eastern, Nan Ya, Lotte): These firms are competing on specialty copolyesters, high-performance grades, and recycled offerings. Their R&D and product bundling strategies define the premium segment and mitigate some commodity cyclicality.
Recent disruptive moves — implications for 2026
-
Facility closures and resumptions: Plant closures or long pauses compress supply locally and can induce short-term price spikes; conversely, resumptions of large projects shift forward-supply expectations. Buyers and sellers must model these one-off supply shocks against multi-year demand trajectories.
-
Feedstock shocks: PTA prices have shown meaningful upward moves in 2025–2026, with rapid month-on-month inflation in some markets. Producers with feedstock integration or hedging strategies were materially more resilient to these swings; downstream buyers faced margin squeezes unless they re-priced contracts or shifted sourcing.
-
Recycling investments: Major investments by oil majors and chemical companies into advanced recycling accelerate capacity for feedstock substitution and create new supply channels for high-quality recycled content.
What the full PW Consulting PET study delivers (operational takeaways)
-
Practical decision tools: Plant-level breakeven matrices, utilization sensitivity dashboards, and short-to-medium term price scenarios to stress-test portfolio choices.
-
Commercial playbooks: Contractual strategies for buyers and sellers under tariff volatility and recycled-content mandates, including sample clauses and negotiation levers.
-
Investment prioritization: A prioritized pipeline of CAPEX options, ranked by NPV sensitivity to feedstock price scenarios and regulatory outcomes.
-
Competitive plays: Tailored strategic options for global players, regional champions, and specialty producers — including vertical integration, JV frameworks for recycling, and premium-product development roadmaps.
-
Risk register and contingency plans: Actionable checklists for supply disruption, rapid feedstock inflation, and market access shocks tied to policy change.
Strategic recommendations for 2026
-
Prioritize feedstock security: Short-run integration, long-run offtake agreements, and tactical hedging should be evaluated against flexibility needs. Scenario planning should assume multiple PTA/MEG price paths.
-
Accelerate circularity where it creates defensible margins: Invest selectively in mechanical or chemical recycling routes that match your product portfolio and customer commitments. Partnerships with converters and brand owners can derisk adoption and demand build-out.
-
Use M&A strategically to de-risk supply or gain technology: Bolt-on acquisitions that increase feedstock control, add rPET capability, or unlock new specialty grades will often be more value-accretive than greenfield green-hats in the current cycle.
-
Harden commercial contracts: Build escalation clauses, feedstock pass-through mechanisms, and flexibility provisions into mid-term contracts to preserve margins without sacrificing market share.
-
Monitor policy and trade developments closely: Tariff shifts and recycled-content mandates can change economics rapidly — incorporate policy triggers into investment decision gates.
What we intentionally withhold in this briefing
To preserve the practical value of our analysis for subscribers, this overview omits the detailed numeric splits and granular tables — including precise regional shares, application-level revenue breakdowns, and per-region price curves. Those core segmentation data, plant-level unit economics, and proprietary scenario-model outputs are available in the full report and interactive dashboards on our site. The summary above is designed as a strategic teaser: it demonstrates the depth of our modelling and the types of actionable recommendations we deliver while pointing decision-makers to the decisive data required for execution.
Next steps
For leadership teams preparing capital plans, procurement redesigns, or M&A strategies in 2026, the PW Consulting PET study provides the specific inputs and decision frameworks needed to move from intent to execution. Contact our advisory desk to schedule a briefing and to obtain the full dataset, interactive model, and tailored scenario walkthroughs that convert these strategic imperatives into measurable action.
For detailed analysis of this topic, please visit the official page: Polyethylene Terephthalate (PET) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com