

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rumen Bypass Fat Market to Reach USD 1,556M by 2032 at 6.5% CAGR

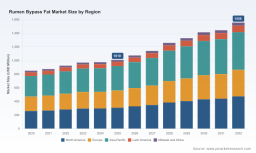
Rumen Bypass Fat Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As global dairy systems enter a phase of intensified productivity and regulatory scrutiny, rumen bypass fats are shifting from niche nutritional adjuncts to strategic line-items in farm P&Ls and corporate procurement strategies. Our latest market model (base year 2025) shows the global rumen bypass fat market at roughly 1.01 billion USD, following a steady rise from the start of the decade and forecasting a compound annual growth rate (CAGR) of about 6.5% through the 2026–2032 horizon. By 2032 the market is projected to exceed mid‑single billion thresholds, driven by intersecting forces in productivity economics, feedstock dynamics, sustainability regulation and consolidation among suppliers.
Rumen Bypass Fat Market
Why this study matters for 2026 strategic planning
- Operational economics are changing fast: Dairy operators and integrators are increasingly treating feed inputs as leverageable margin drivers rather than passive cost categories. Bypass fats offer a clear, measurable pathway to energy-dense rations that lift milk yield per cow and improve feed efficiency; the evolving ROI calculus is now a board-level issue for large cooperatives and commercial dairies.
- Regulatory and market-access imperatives: Sustainability frameworks (notably in developed markets) are re-shaping which inputs qualify a producer for premiums and market access. Compliance with reporting regimes and carbon pricing mechanisms is translating into demand for nutritional strategies that demonstrably reduce enteric emissions — bypass fats are part of that toolkit.
- Supply-side concentration amplifies competitive tactics: The category exhibits meaningful concentration among a limited set of global suppliers. This structural reality amplifies the importance of supplier strategy, long-term contracts, co-development agreements and feedstock security for buyers.
Market dynamics and key growth levers
The market’s mid-single-digit CAGR reflects several durable drivers. First, dairy productivity targets in both established and high‑growth production systems are incentivizing energy-dense ration components to protect yields in high-yielding and transition cows. Second, sustainability-linked premiums and the need to meet increasingly stringent environmental reporting are making bypass fats attractive where they can be shown to reduce enteric methane emissions. Third, manufacturers that secure reliable, cost-advantaged plant-based feedstocks are better positioned to manage pricing pressure in competitive feed markets.
Rumen Bypass Fat Market
That said, demand growth is not uniform — it is paced by farm economics, feedstock availability and regulatory regimes. Volatility in vegetable oil and animal fat feedstock prices has been material (notably multi‑tens of percent swings over recent years), creating acute procurement and margin management imperatives for both manufacturers and large-scale buyers.
Rumen Bypass Fat Market
Risk vectors that should be on every 2026 board agenda
- Feedstock price shock: Historical feedstock volatility has triggered margin compression at key points. Firms that lack hedging frameworks or multi-source supply strategies exposed themselves to episodic cost inflation and ration reformulation risk.
- Regulatory divergence: While some markets incentivize emissions-reducing inputs, others impose stricter rules on feed additives and ingredient labeling. Strategic players need a regulatory matrix to evaluate product approvals, claims substantiation and market-entry timelines.
- Channel and farmer economics: Adoption curves are shaped by how product value is captured — on-farm yield gains, contract pricing, co-funding for trials, and demonstrable ROI tools. Without credible farm-level economics, adoption stalls even where technical efficacy exists.
- Consolidation and supplier power: With a sizeable share of supply concentrated among the leading firms, buyers face both the risk of supplier-driven price scenarios and the opportunity to leverage strategic partnerships for R&D, formulation exclusivity, and integrated service offerings.
Competitive landscape — what the leaders are doing
The category is anchored by a mix of global oil‑and‑ingredient integrators, specialty oleochemical producers and animal nutrition houses. Leading players are deploying three principal playbooks:
- Vertical integration and feedstock control: Companies with upstream access to refined oils or integrated oilseed processing are using procurement scale to stabilize cost and ensure formulation consistency across markets.
- Product differentiation through formulation and services: Vendors are pairing technical formulations with farmer-facing tools — ROI calculators, herd-level modeling, and field trial datasets — to shorten sales cycles and demonstrate financial outcomes.
- Regional go‑to‑market depth: Several suppliers combine local manufacturing or co‑packing with established distribution partnerships to minimize logistic friction and react quickly to regional feedstock shifts and regulatory changes.
Representative strategic profiles (selected leaders):
- Integrated ingredient players: Firms with broad oilseed processing or oleochemical portfolios are leveraging feedstock scale to offer competitive pricing and route-to-market advantages in the Americas and Asia.
- Specialty formulators and co‑ops: European and regional specialists are focusing on custom formulations and close cooperation with dairy cooperatives, emphasizing compliance with local sustainability standards and traceable sourcing.
- Service-led nutrition houses: Nutrition-centric companies augment product sales with data, support services and digital ROI tools to win share among progressive farms and integrators.
Recent vendor-level developments illustrate this dynamic: upgraded digital ROI tools and farmer economic calculators have been launched to help quantify the case for supplementation — signaling an industry shift toward evidence-based, service-enabled sales models.
What the full report delivers — tactical outputs for 2026
Our full research package is built as an operator’s playbook for procurement, product, and corporate strategy teams. Highlights include:
- Market sizing and a detailed demand model (historical and forecast through 2032) calibrated to production economics and regulatory scenarios.
- Supply-chain maps and feedstock-sensitivity models — including price-shock and hedging scenarios — to inform procurement and manufacturing location decisions.
- Commercialization playbooks for formulation differentiation, trial design, and farmer economics communication (templates for ROI messaging and KPIs).
- Regulatory and sustainability matrices by market segment, with actionable steps to translate emissions-reduction benefits into market access and premium capture.
- Competitor dossiers and strategic heatmaps that identify partnership, co-development, and M&A opportunities — matched to capability and geographic footprints.
- Near-term scenario planning tools to stress-test pricing, feedstock availability, and adoption rates to guide capex and inventory strategies for 2026 and beyond.
How to use this intelligence in 2026 planning cycles
We recommend three immediate actions for organizations shaping 2026 budgets and strategy:
- Stress-test procurement and hedging plans: Build a dual-track feedstock strategy that pairs long-term purchase agreements with flexible spot sourcing and inventory buffers; run the report’s price-shock scenarios against your existing supplier book.
- Embed evidence-based ROI tools into the sales funnel: Field pilots should be designed with standardized KPIs and economic templates so that commercial teams can translate technical benefits into clear P&L outcomes for farmers and integrators.
- Align product and sustainability narratives: Where regulatory frameworks create premium opportunities, link product claims to documented emissions outcomes and third-party reporting standards to accelerate premium capture and market access.
Where this research sits in the competitive intelligence stack
Think of the report as a decision-grade bridge between scientific literature and commercial execution: it compiles technical efficacy data, market economics, supplier analysis and regulatory context into actionable options. We intentionally limit detailed segment-level disclosure in this preview: the full dataset — including granular regional and application-level demand curves, supplier share details, and modeled farm economics — is available in the complete study for clients and subscribers.
Final strategic takeaway
Bypass fats are no longer an optional enhancement for progressive farms — they are becoming an integral lever within a broader strategy that links productivity, sustainability reporting and supply-chain resilience. The market’s steady growth trajectory (backed by a 6.5% CAGR through the forecast window) and concentrated supplier base create both risks and high-value opportunities for companies that act decisively in 2026: secure diversified feedstocks, operationalize farm-level ROI evidence, and structure commercial agreements that convert technical efficacy into reliable margin improvement.
For procurement directors, nutrition teams and corporate strategists preparing budgets and M&A playbooks in 2026, this study provides the market architecture and tactical instruments to move from hypothesis to executable plans. To access the full segmentation models, supplier dossiers, and scenario tools referenced here, please consult the primary report page linked in our release.
For detailed analysis of this topic, please visit the official page: Rumen Bypass Fat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com