

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Quinoa Seed Market to Reach USD 1,490M by 2032 at 7.8% CAGR

Quinoa Seed Market — 2026 Strategic Preview
Executive snapshot
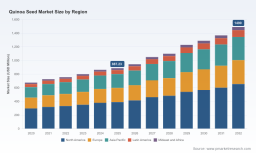
As companies plan for 2026, the quinoa seed market presents a balanced mix of rapid growth, geographic shifts in production, and rising regulatory scrutiny. Our PW Consulting analysis uses a 2025 base year and projects the market forward to 2032. The sector is forecast to grow at a compound annual growth rate (CAGR) of 7.8% over the 2026–2032 period, taking an estimated global market size from roughly USD 887 million in 2025 to about USD 1.49 billion by 2032. Those headline dynamics underscore why executives need actionable scenario options now — not later — to capture value across breeding, production, processing and trade corridors.
Quinoa Seed Market
Why this research matters for 2026 decision-making
- Resource allocation with confidence: A clear, data‑driven forward view allows firms to prioritize R&D and capex for new seed lines, conditioning facilities and origin partnerships with calibrated timing.
- Risk-adjusted sourcing strategies: With supply volatility and disease pathway concerns rising, buyers and processors must design layered procurement strategies that combine origin diversification, forward contracts and in-region multiplication.
- Regulatory and certification readiness: Evolving seed certification standards and new disease-management guidance mean compliance investments can become competitive differentiators rather than cost centers.
- Go-to-market and product innovation: Opportunities for premiumization, organic certification and regionally adapted varieties will determine whether players capture margin or remain commodity‑priced.
What PW Consulting’s full report delivers (practical, operational outputs)
- Market sizing and demand model with transparent methodology (2020–2025 historical calibration and 2026–2032 forecasts), enabling custom scenario runs.
- Driver decomposition and sensitivity analysis: yield, acreage, price, processing throughput and consumer uptake vectors isolated for strategic planning.
- Supply-chain mapping and unit-cost build-ups from seed multiplication through cleaning, grading and logistics — farm-to-retail cost models usable for sourcing negotiations.
- Regulatory and seed-certification playbook, including compliance checklists and time-to-certification timelines by major markets.
- Actionable competitor playbooks with strengths/weaknesses, partnership fit matrices and potential M&A targets.
- Decision-grade risk register and mitigation playbooks (biosecurity, climate, trade, input costs) with contingency triggers for 2026 procurement cycles.
- Commercial roadmaps for product managers: SKU rationalization, premium positioning, co-branding and route-to-market sequencing.
Headline market dynamics shaping 2026 strategies
Three interlocking dynamics will determine winners and laggards in 2026:
Quinoa Seed Market
- Accelerating demand and above‑average growth: The market’s mid‑single-digit pickup into the forecast window drives urgency. Even small increases in yield or processing efficiency translate into material competitive advantage.
- Public policy and institutional funding: Significant public investment in 2025 has already altered research and soil‑health projects; the USDA and other agencies have committed material funds to variety evaluation and agronomy programs, catalyzing faster varietal improvement and uptake.
- Regulatory tightening and biosecurity focus: Recent updates to seed certification standards in important producing jurisdictions and new technical guidance on seed-borne diseases mean that compliance timelines — not just price — will govern market access for new suppliers.
Recent developments to factor into 2026 plans
- Varietal breakthroughs: National breeding programmes released new varieties following multi-site trials that demonstrate higher yield potential and adaptability to marginal environments. These releases indicate accelerating varietal turnover in origin countries and new licensing opportunities for seed multipliers and distributors.
- International development partnerships: Collaborations between national governments and multilateral agencies are expanding capacity for sustainable quinoa value chains in emerging producing regions, creating new supplier pools and localized processing capacity.
- Regulatory and technical resources: Seed certification frameworks and technical chapters on disease identification/management have been published by authorities — these will raise the bar for incoming seed lots and increase the value of vertically integrated quality assurance.
Competitive landscape — what leading players reveal about strategic options
The market structure is neither a pure commodity oligopoly nor a highly fragmented cottage industry. The top incumbents control a meaningful but not overwhelming portion of the market, leaving room for specialists and agile entrants. Key competitive archetypes and their strategic implications are:
Quinoa Seed Market
- Adaptive specialist innovators (example: Adaptive Seeds)
Firms focused on organic, open‑pollinated varieties and breeding for short-season climates are driving premium product categories and enabling cultivation in non-traditional regions. Adaptive Seeds’ portfolio expansion and certified-organic positioning suggest an opportunity for partnerships to scale northern production and capture premium retail channels.
- Large-origin and ingredient suppliers (example: NorQuin)
Producers and processors that offer both seed and finished ingredient lines provide buyers with reliable volumes and integrated quality control. These players are natural partners for co-development of variety traits that support processing efficiencies and ingredient specifications.
- Regional distributors and specialty merchants (examples: British Quinoa Company; The Real Seed Collection)
Channel specialists and heritage seed collections play a vital role in diversification and retail penetration. They are important for market testing of niche varieties and premium labels, and can be acquisition targets for scaling brand-led strategies.
- Origin-focused exporters and co-operatives (examples from Peru and Bolivia)
Traditional Andean suppliers remain core sources of genetic diversity and bulk supply. Their value lies in provenance, traditional agronomy expertise and established export networks; strategic engagements can secure raw material while enabling traceability and sustainability certification programs.
- Diversified seed houses (example: Hancock Seed Company)
Companies that distribute quinoa alongside other seed categories provide access to broader grower networks and multi-crop extension channels, which can help accelerate geographic diffusion of new varieties.
Strategic implications for 2026
- Prioritize varietal adaptability and certification: Invest in or partner for access to varieties proven in target climates, and build certification timelines into project plans to avoid market access delays tied to updated regional standards.
- Design layered procurement: Combine anchored volume contracts with optionality clauses and local multiplication agreements to reduce single‑source exposure.
- Embed biosecurity and disease surveillance: Operationalize new technical guidance into seed testing protocols and supplier audits to reduce recall and rejection risk.
- Segment product strategy: Separate portfolios for commodity supply, certified-organic, and specialty seed lines. Use origin provenance to justify premiums and mitigation of supply risk through multiple origins.
- Explore vertical or horizontal consolidation selectively: Pursue bolt‑on acquisitions or exclusive supplier agreements to capture scale economics in processing and packaging while retaining agility in varietal R&D.
Risks you cannot ignore in 2026
- Biosecurity incidents and seed-borne diseases that can disrupt planting and trade windows.
- Regulatory misalignment across producing and importing jurisdictions that creates certification bottlenecks.
- Climate-induced yield variability that increases working capital needs and complicates fixed-price contracts.
- Supply-chain concentration risks if too much purchasing is centralized with a small number of origin suppliers.
How to use the full PW Consulting report
This preview demonstrates the analytic depth and practical orientation of our work while deliberately withholding detailed segment-level share tables and granular regional/application splits to preserve the value of the full study. The comprehensive report includes time-series datasets, scenario tools and supplier scorecards you can operationalize in procurement, product and M&A workflows for 2026.
Closing recommendation — an executive checklist for Q1–Q2 2026
- Secure varietal access agreements or licensing options for climate‑adapted lines before planting windows open.
- Audit and upgrade seed‑certification readiness against the latest standards and disease-management guidance.
- Allocate a portion of R&D budget to rapid on-farm trials in target regions to validate processing yields.
- Engage potential origin partners and multilateral programs to lock in sustainable supply corridors and leverage public funding opportunities.
- Commission the full PW Consulting report to obtain the detailed segmentation, supplier-level metrics and downloadable datasets required to execute the steps above.
For firms that want to convert the market’s projected growth into durable advantage in 2026, the critical choices will be made around varietal control, certification velocity, and supply-chain design. PW Consulting’s full study is structured to turn those choices into executable roadmaps — from board-level investment decisions to field-level agronomy plans.
For detailed analysis of this topic, please visit the official page: Quinoa Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com