

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Artificial Grass Turf Market to Reach USD 12.4B by 2032 at 8.3% CAGR

Artificial Grass Turf Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
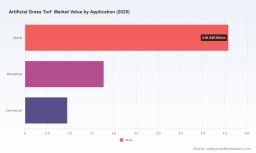
As organizations plan capital allocation, product roadmaps and market entry strategies for 2026, the artificial grass turf sector presents a blend of structural growth and transitional risk. Our research shows the global market expanding from roughly USD 5.2 Billion in 2020 to USD 7.3 Billion in 2025, and is forecast to reach approximately USD 12.4 Billion by 2032 — representing a compound annual growth rate of about 8.3% over the forecast period. Those headline dynamics reflect rising demand across sports, residential and commercial applications, continued material innovation, and evolving sustainability and regulatory pressures that will shape competitive positioning through the remainder of the decade.
Artificial Grass Turf Market
Why this briefing matters for 2026 strategic decisions
-
Timing of investments: With market growth accelerating into the latter half of the 2020s, 2026 is a pivotal year to decide whether to accelerate capacity expansion or prioritize modular, lower-capex product pilots that can be adapted as regulatory and material constraints evolve.
Artificial Grass Turf Market -
Regulatory inflection points: Policy developments (regional bans, chemicals scrutiny and tariff reclassifications) are shifting product design and supply-chain priorities. Companies that align product roadmaps and procurement strategies to anticipated regulation will preserve margin and access to high-value markets.
Artificial Grass Turf Market -
Competitive differentiation: While the top-tier manufacturers retain scale advantages, the market remains sufficiently open for differentiated propositions — particularly around infill-free systems, recycled-content narratives, and verification against emerging health and microplastics standards.
-
Risk-managed growth: Growth is robust, but concentrated in specific channels and product types. Pragmatic scenario planning and supplier-risk audits are essential to avoid overexposure to raw-material or regulatory shocks.
What this PW Consulting report delivers (practical, action-oriented content)
-
Financial baselines and forecasts: A rigorously back-tested market model with historical tracking (2020–2025) and detailed forecasts (2026–2032) to underpin capex and revenue planning. The model is provided in downloadable format for sensitivity testing against price, substitution and regulatory scenarios.
-
Decision frameworks: Ready-to-use frameworks for market-entry prioritization, product portfolio rationalization, and M&A screening that map financial metrics to strategic outcomes.
-
Regulatory playbooks: Practical checklists and compliance roadmaps tailored to major jurisdictions, including contingency templates for substitution of granular infill, material certifications and label claims.
-
Supplier and raw-material risk analytics: Heatmaps of supply concentration, import-classification and tariff exposures, plus actionable mitigation levers (dual-sourcing, strategic safety-stock sizing, nearshoring options).
-
Commercial go-to-market tools: Channel-specific pricing elasticity insights, procurement negotiation talking points, and a phased sales plan for rolling out new low-infill or infill-free products.
-
M&A and partnership agendas: A prioritized shortlist of target archetypes, valuation sensitivities and post-acquisition integration checklists focusing on synergies in manufacturing, distribution and specification leadership.
-
Data annex (gated): Granular segmentation tables and modeled scenarios by type, application and region — reserved for subscribers and those who download the full report.
Industry dynamics shaping strategic choices in 2026
-
Regulatory divergence and timing uncertainty: Policymaking is the primary non-market variable. The European Union’s regulatory movement on granular infill, together with state-level chemical scrutiny in jurisdictions such as California, is forcing two simultaneous responses: rapid product re-engineering for markets with imminent restrictions, and robust compliance documentation to retain access to conservative buyers elsewhere. Notably, a high-profile authoritative review in 2026 concluded that specific crumb-rubber chemicals did not present significant aggregate health risk; this shifts the debate from absolute prohibition to risk-managed use and documented stewardship in some markets.
-
Material evolution and product architecture: Companies are competing along two axes — fiber technology (durability, playability) and infill strategy. Infill-free systems and advanced fiber formulations are becoming decisive differentiators where bans or buyer preference demand lower microplastic release or recycled-content narratives.
-
Supply-chain and trade considerations: Updated import classifications and tariff rulings have altered landed-cost calculations for a portion of global trade. Procurement teams must re-evaluate freight, classification and bonded-warehouse strategies to preserve margin in price-sensitive channels.
-
Raw-material concentration and circularity pressures: The sector’s historic reliance on recycled crumb rubber — which can require tens of thousands of passenger-car tire equivalents per athletic surface — creates both circular-economy storytelling opportunities and vulnerability if feedstock availability changes or is constrained by regulation. Anticipating alternative feedstocks and validated recycling streams is an immediate operational priority.
-
Market structure: Market concentration is moderate; the top three and top five firms capture measurable shares but do not preclude new entrants or regional champions from securing niche leadership. This creates opportunities for both bolt-on M&A and organic innovation plays.
Competitive landscape — what to watch among established players
-
FieldTurf (Montreal) — A pioneer in infilled synthetic systems and an installation leader globally. Their installed-base scale is an advantage for specification leadership and lifecycle service offerings. Strategic focus: leverage installation scale into service contracts and validated maintenance programs that monetize existing fields while piloting infill alternatives.
-
Tarkett (Paris) — A major supplier positioning through brand and integrated manufacturing. Strategic focus: integrate sustainability credentials and certification to protect access to stringent public-sector bids across Europe and elsewhere.
-
SYNLawn (United States) — Emphasizes plant-based and residential-oriented solutions. Strategic focus: capitalize on premium consumer channels and commercial landscaping opportunities where environmental marketing can command price premiums.
-
TenCate Grass (Netherlands) — Known for materials innovation and infill-free systems. Strategic focus: scale advanced-fiber platforms into mainstream sports and municipal tenders in markets seeking lower lifecycle environmental impact.
-
Smart Turf (California) — Wholesale manufacturer with North American reach. Strategic focus: cost leadership and channel partnerships to serve regional installers and retail channels; opportunity to extend private-label agreements under shifting tariff regimes.
-
Sprinturf (United States) — Integrated polyethylene turf manufacturer focused on athletic performance. Strategic focus: defend sports-spec market share by coupling performance-certified products with warranty and testing services.
-
Southern Turf Co. (Austin) — Regional supplier of sports and landscaping solutions. Strategic focus: strengthen local municipal and school-district relationships where procurement cycles are less price-elastic but more compliance-sensitive.
-
GeoSurfaces (St. Gabriel) — Designer-installer for high-performance sports surfaces. Strategic focus: leverage technical installation know-how as a moat against commoditized product-only competition; grow integrated service offerings for stadium and institutional clients.
Recent developments that materially change the playbook
-
Authoritative reviews in 2026 addressing crumb rubber chemicals have reduced a certain class of health-safety uncertainty in some jurisdictions, enabling operational continuity for products using recycled-tire infill where regulators accept the findings.
-
Regulatory timelines such as announced bans on granular infill in certain markets have created a clear runway for R&D and pilot deployment of infill-free or alternative-infill technologies — companies that begin deployment now will enjoy specification advantages when prohibitions become effective.
-
Tariff and import-classification changes have altered landed costs and supplier calculus for manufacturers that rely on cross-border supply chains; reclassification actions are most impactful for players without diversified manufacturing footprints.
Actionable strategic options for 2026
-
Fast-follower product strategy: Launch pilot product lines of infill-reduced or infill-free systems in selected geographies while preserving legacy offerings where permitted. Test pricing strategies and build certified performance dossiers for public procurement.
-
Supply-chain resilience program: Execute dual-sourcing for critical fibers and secure recycled feedstock contracts with volume-flex clauses. Re-evaluate customs classification and duty mitigation plans to protect margins.
-
Service-led monetization: Convert installed-base scale into recurring revenue through maintenance contracts, testing services and warranty programs — particularly valuable for players with significant sport-field footprints.
-
M&A and partnership playbook: Prioritize bolt-ons that add proprietary fiber technology, verified recycling streams, or regional installation capacity that accelerates compliance with local regulations.
-
Stakeholder engagement: Proactively engage regulators, public-health agencies and procurement bodies to influence standards and to ensure company testing protocols are aligned with emerging certification expectations.
Next steps and how to access the full intelligence
This briefing is a strategic “trailer”: it highlights the growth trajectory, the essential risk vectors and the executable options decision-makers must weigh in 2026. The full PW Consulting Artificial Grass Turf Market report contains the granular segmentation datasets, country and channel-specific forecasts, supplier scorecards, and downloadable financial models you will need to convert insight into action. For procurement teams, product leaders and corporate strategists planning capital commitments this year, the gated annexes and scenario models are the essential inputs for board-level investment memos.
If you are preparing a 2026 investment, procurement or M&A decision in the artificial turf space, our report provides the reproducible data and tactical playbooks to shorten time-to-decision and to de-risk execution. Visit our report page to download the full dataset and the PW Consulting playbooks that translate these market dynamics into concrete operational steps.
For detailed analysis of this topic, please visit the official page: Artificial Grass Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com