

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ear Plugs Market to Grow at 5.9% CAGR, Reaching USD 2,142.8M by 2032

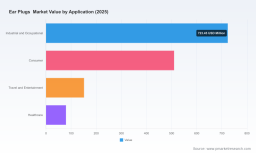
Ear Plugs Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-oriented preview of our full Ear Plugs Market research (base year 2025, historical 2020–2025, forecast 2026–2032). This synopsis highlights the strategic implications executives must act on in 2026 while deliberately withholding the granular segment tables and proprietary spreadsheets that drive our valuation models — those are available in the full report.
Ear Plugs Market
Market at a Glance
- The global ear plugs market has shown resilient expansion through the early 2020s, increasing from an early-decade baseline to an estimated market size at the 2025 base year (figures presented in USD Million in the full report).
- Our forecast horizon (2026–2032) models growth at a compound annual growth rate (CAGR) of 5.9%, with the market continuing to broaden across industrial, consumer and specialty medical contexts.
- Competitive concentration is meaningful but not prohibitive: the top three firms command a measured share of the market, and the top five firms represent roughly half of industry revenue, creating opportunities for mid-sized players and new entrants that can differentiate on technology, compliance or service.
Why this research matters for 2026 decisions
- Regulatory inflection points are already changing procurement and product roadmaps. Industry stakeholders must reconcile classical PPE positioning with evolving medical-device pathways and quality system alignment.
- Macro industry signals point to steady demand growth and rising expectations for measurable performance (fit, attenuation verification, comfort) — which correlates with higher willingness to pay in several buyer segments.
- Margin pressures from raw material and labor cost dynamics mean manufacturers need targeted pricing strategies, product-mix optimization and manufacturing footprint decisions early in 2026 to protect profitability through the forecast period.
Regulatory and Standards Dynamics — immediate 2026 implications
- Hearing conservation guidance: NIOSH guidance to derate labeled Noise Reduction Ratings (NRR) for high-noise environments underscores an industry-wide need to provide end-user education, fit-check services and validated attenuation data to preserve product credibility in occupational settings.
- Regulatory classification: earplugs that make hearing-protector claims are subject to premarket pathways in leading markets. The FDA’s 510(k) requirement for hearing protectors under product code EWD is an actionable gate for U.S. market access and claims.
- Quality system harmonization: the QMSR-driven alignment with ISO 13485:2016, effective from February 2026, raises the bar for manufacturers pursuing medical or clinical positioning — creating certification hurdles and potential market access advantages for compliant players.
- Employer obligations: OSHA mandates that employers provide hearing protectors free to employees exposed to specified noise thresholds. This sustains demand in industrial channels but increases price sensitivity and supplier selection scrutiny among procurement teams.
Market Dynamics & Strategic Tensions
Three structural tensions will shape competitive advantage over the next 18–36 months:
Ear Plugs Market
- Performance vs. Cost: Disposable foam products preserve low upfront costs, but reusable and custom-molded solutions offer lifetime value and differential margins. Buyers with long-term exposure profiles increasingly weigh total cost of ownership.
- Standardized attenuation vs. individualized fit: technology that combines high attenuation with comfort (and ideally validated through fit-testing) commands a premium in both occupational and premium consumer segments.
- Scale vs. specialization: consolidated industrial buyers and large distributors favor scale partners, while specialized OEM, audiology and D2C consumer channels reward nimble, innovation-led firms.
Competitive Landscape — what to watch in 2026
The market comprises established multinational PPE manufacturers, specialized hearing-protection brands, and a set of regional players with deep B2B relationships. The CR3 and CR5 metrics indicate moderate concentration: market leadership exists, but meaningful share is available to differentiated challengers.
Ear Plugs Market
- 3M Company (St. Paul, MN, USA) — continues to anchor the industrial and professional segments. Recent trade fair activity showcased integrated PPE solutions pairing ear protection with broader safety ecosystems.
- Honeywell International Inc. (Charlotte, NC, USA) — pursues scale and channel partnerships; its portfolio strategy reinforces procurement-driven wins in large corporate and industrial accounts.
- Moldex-Metric, Inc. (Culver City, CA, USA) — focuses on fit and performance differentiation for professional users and audiology services.
- Loop BV (Antwerp, Belgium) and Alpine Hearing Protection (Netherlands) — represent consumer-centric innovation paths emphasizing comfort, aesthetics and lifestyle positioning.
- E.A.R. Inc., Etymotic Research, UVEX Safety Group, Hellberg Safety and Elvex — together these players span markets from audiological specialties to industrial PPE with regional strengths and niche technical competencies.
- Recent industry signaling: 3M’s prominent presence at A+A 2025 and uvex’s participation at Interschutz 2026 indicate management focus on product visibility, channel engagement and standards alignment in 2026.
What the full PW Consulting report delivers (practical, operational)
Our full deliverable is designed to be immediately actionable for strategy, product and commercial leaders. Highlights include:
- Comprehensive market model (historical 2020–2025; forecast 2026–2032) with scenario layers that stress-test outcomes against raw material shocks, regulatory shifts and channel disruption.
- Go-to-market playbooks tailored to industrial procurement, healthcare buyers, travel/entertainment OEMs and premium consumer channels (including pricing ladders and negotiation points for corporate procurement teams).
- Competitive profiles and capability matrices for leading and challenger firms, including product roadmaps, recent R&D investments, channel footprints and patent/technology indicators.
- Regulatory compliance matrix covering global premarket pathways, quality system expectations (including QMSR/ISO 13485 pathways), and employer-translated obligations (e.g., OSHA equivalence).
- Unit economics and margin benchmarks by product class (disposable, reusable, custom) and tactile templates for manufacturing-sourcing decisions, nearshoring tradeoffs and contract manufacturing evaluation.
- Actionable M&A and partnership playbooks highlighting target archetypes, valuation approaches and integration risks for 2026 deal activity.
Priority strategic moves for 2026 (recommended sequencing)
- Short term (0–6 months): Audit regulatory posture — prioritize 510(k) strategy where applicable, confirm QMSR/ISO alignment, and prepare labeling/fitspec updates to reflect NIOSH derating guidance.
- Near term (6–18 months): Rationalize product portfolio to optimize the mix between low-cost disposables and higher-margin reusables/customs. Pilot fit-validation services that can be cross-sold to large industrial accounts.
- Medium term (12–36 months): Execute channel-specific investments — e.g., direct supply agreements with large employers, expand D2C and premium consumer branding, or pursue bolt-on acquisitions that add audiology or molding capability.
- Cross-cutting: Implement a data-driven pricing framework that captures total cost of ownership, supports value-based pricing for clinical/occupational claims, and prepares for sustainability messaging linked to end-of-life programs.
Use cases: how different executives should act
- CEOs and Strategy Leads: Use the report’s scenario suite to stress-test M&A targets and decide whether to pursue scale or specialization by segment.
- Product and R&D Heads: Prioritize investments in fit-validating technologies and comfort-focused materials that can command a premium and reduce return rates in premium channels.
- Regulatory and Quality Heads: Fast-track ISO 13485 alignment where clinical claims are strategic, and embed FDA 510(k) timelines into product release plans for the U.S. market.
- Commercial and Procurement Teams: Rebuild supplier scorecards to include fit-verification capability, regulatory compliance certifications and lifecycle cost metrics rather than purchase price alone.
What we intentionally omit here — and why
To preserve the full strategic value of PW Consulting’s primary research and proprietary models, we have intentionally withheld the granular segmentation tables (regional, product-type and application-level sub-splits) and the underlying company-level revenue attachments. This preview surfaces trends, regulatory inflection points and executable recommendations while directing decision-makers to the full dataset for contract negotiations, valuation multiples and channel-level playbooks.
Next steps
For procurement-ready datasets, a downloadable competitive playbook, and the full 2026–2032 scenario suite with sensitivity analytics, access the PW Consulting Ear Plugs Market 2026 report. If you would like a bespoke briefing — a 60–90 minute executive session where we apply our model to your company’s product portfolio and go-to-market options — contact our research team to schedule a private workshop.
For detailed analysis of this topic, please visit the official page: Ear Plugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com