

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Earbuds Market Eyes USD 45.5B by 2032 with 9.45% CAGR

Earbuds Market 2026: Strategic Imperatives for Market Leaders and Challengers
As PW Consulting’s lead industry analyst, I present a forward-looking synthesis of our Earbuds Market research that is calibrated for executive decision-making in 2026. The category that once began as a niche accessory has evolved into a multi-dimensional platform—audio, health sensing, wireless connectivity, and device ecosystems—whose commercial trajectory is both rapid and structurally transformative. This briefing highlights the strategic value of our full study for 2026 corporate planning while deliberately withholding the granular segment tables and regional splits that are reserved for the full report.
Earbuds Market
Why 2026 Is an Inflection Year
The earbuds market has shown extraordinary expansion: from a modest base in 2020 to a substantial installed revenue base in our 2025 base year, and continued acceleration into the 2026–2032 forecast window. Our model projects a compound annual growth rate (CAGR) of 9.45% over the forecast period and a market size moving meaningfully higher by 2032. That growth is not linear; it reflects inflection points tied to connectivity standards (e.g., Bluetooth 6.0 and Auracast), broader ecosystem enablement, product-class innovation (active noise cancellation, open-ear/bone-conduction options), and regulatory shifts, particularly in Europe.
Earbuds Market
For any executive deciding resource allocation in 2026, the question is no longer whether the market grows, but where along the product, channel, and regional continuum they should place bets to maximize return and strategic positioning.
Earbuds Market
Strategic Implications for 2026 Decision-Makers
-
Portfolio Prioritization: Leaders must distinguish high-return product tiers (flagship performance, premium ANC, and ecosystem-integrated models) from high-volume entry tiers where margin compression and supply concentration dominate. Our analysis identifies marginal returns on incremental hardware improvements versus value captured through services and ecosystem lock-in—an essential input for R&D and pricing allocation.
-
Platform vs. Point Product Thinking: As earbuds converge with voice assistants, health telemetry, and spatial audio services, winners will be those who move from hardware-centric P&Ls to hybrid models that capture recurring revenue (subscription audio services, premium features, enterprise provisioning for remote-work kits).
-
Supply Chain Resilience: Component innovation (balanced armature drivers, multi-driver dual-driver layouts, miniaturized ANC circuits) and new wireless standards drive supplier selection and inventory strategies. Our research highlights how partnership choices—especially with specialist suppliers—affect product differentiation timelines and cost of goods sold in 2026.
-
Regulatory and Trade Risk: Recent EU and transatlantic developments have material implications for hardware design, certification timelines, and go-to-market sequencing. Firms that front-load compliance and capitalize on regulatory windows can accelerate relative market share gains in affected markets.
-
M&A and Partnership Playbook: Consolidation signals—reflected in market concentration metrics—suggest targeted bolt-ons (driver specialists, firmware/security firms, or regional distribution platforms) are an effective route to accelerate capability build rather than organic development alone.
Operationally Actionable Content in the Full Report
Our full study contains utility-first deliverables tailored for executives and product teams preparing for the 2026 planning cycle:
- Decision frameworks for portfolio prioritization that map projected demand elasticities against R&D and marketing investment thresholds.
- Practical go-to-market playbooks for different channel strategies—direct-to-consumer, carrier bundles, retail, and enterprise distribution—that include timed launch sequences to minimize cannibalization and maximize SKU coverage.
- Supplier and component scorecards (technical capability, capacity, lead-time sensitivity) with scenario-based sourcing strategies to mitigate single-source risk.
- Regulatory compliance checklists and a timeline for EU-specific requirements (charging, batteries, digital market access) that materially affect product specs and certification calendars.
- Product roadmap prioritization templates that incorporate Bluetooth/Auracast readiness, lossless codec implementation, spatial audio, and emergent low-latency requirements for mixed reality use cases.
- M&A screening matrices and integration playbooks for earbud-related acquisitions—hardware, firmware, or service-oriented—designed for near-term impact.
Competitive Landscape: What the Leading Players Reveal About Market Structure
The competitive field is a mix of vertically integrated platform giants, audio-first specialists, fitness- and lifestyle-focused brands, and component masters whose capabilities diffuse across multiple OEMs. Market concentration is moderate; our concentration metrics show that the top three and top five groups collectively control under two thirds of the market—enough to indicate power centers, but with meaningful room for challengers that can innovate or exploit niche adjacencies.
-
Platform Integrators: Companies with tightly integrated device ecosystems translate software-hardware synergies into higher Per-User Revenues. Their strengths include seamless pairing, system-level optimizations, and monetization pathways (services, ecosystem accessories). In the current environment, regulatory forces compel these players to rethink access models to maintain ecosystem control while complying with digital market rules.
-
Audio Specialists: Long-standing audio brands continue to leverage acoustic heritage and signal-processing IP to justify premium pricing in flagship categories. Their roadmap choices center on differentiated ANC, spatial audio experiences, and premium materials.
-
Value and Mid-Market Innovators: Aggressive cost engineering, frequent refresh cycles, and narrower feature-focused SKUs define success here: battery life, fit and form, IP ratings for active users, and the ability to rapidly adopt new BT codecs or Auracast broadcasting.
-
Component and IP Suppliers: Balanced armature drivers, micro-electro-acoustic components and battery-cell sourcing power the innovation chain. Strategic suppliers who secure multi-client contracts can accelerate new form factors into the market, effectively shaping OEM roadmap timelines.
Recent product introductions in early 2026 underscore these dynamics. Several firms launched open-ear and compact ANC earbuds while others pushed Bluetooth 6.0, Auracast support, and lossless codecs into more accessible price points. These moves compress product cycles and shorten feature parity timelines for mid-market entrants—an important tactical consideration for 2026 launches.
Regulatory and Trade Shifts: Practical Consequences
Regulation has moved from a background risk to a market-shaping force. Key developments include harmonized charging requirements in parts of the EU, evolving rules on battery removability for wearables, and legal obligations under large digital markets frameworks that change how platform players must support third-party devices. Additionally, recent tariff agreements and clarifications on portable battery exemptions alter landed costs and channel pricing strategies.
For 2026 planning, companies must:
- Embed regulatory compliance into the product development lifecycle rather than treating it as a pre-launch checkbox.
- Evaluate dual-design pathways for markets with differing legal requirements to avoid costly redesigns late in the cycle.
- Reassess OS-level partnerships and pairing mechanisms to ensure access to key value features on major platforms without being dependent on proprietary hooks that regulators may require to be exposed.
Where to Focus Investment in 2026
- Short-term: Accelerate fit-and-function upgrades (improved ANC, battery optimizations, IP ratings) for SKUs that can be refreshed without major hardware retooling; lock supply for high-value components.
- Medium-term: Invest in services tied to user experience (spatial audio profiles, tailored hearing profiles, enhanced call clarity) and firmware update capabilities that can be monetized or used to raise switching costs.
- Long-term: Build software and platform-level competencies—including low-latency codec pipelines and Auracast broadcast services—that position the company as a partner rather than a price-competitive supplier.
Conclusion: The Strategic Value of the Full PW Consulting Study
For 2026 corporate planning, our Earbuds Market study functions as a decision-acceleration tool. It translates top-line growth projections and concentration dynamics into executable strategies across product development, supply chain, regulatory compliance, go-to-market sequencing, and M&A prioritization. The high-level numbers tell you the market is growing at a near-double-digit CAGR; the operational frameworks in the full report tell you how to convert that growth into defensible margin and market share gains.
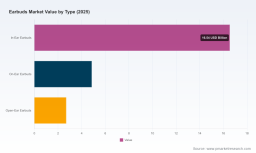
Note: To preserve competitive advantage and adhere to the “trailer” approach, detailed segment-level tables—regional, by-type, by-application breakdowns, and the granular unit-price matrices—are available exclusively in the full report and accompanying data pack.
Next Steps
- Request the complete report and data pack for the full segmentation, scenario models, and supplier scorecards.
- Schedule a strategy workshop with PW Consulting to translate the findings into a 90-day action plan tailored to your organization’s capabilities and risk appetite.
PW Consulting stands ready to convert these market insights into executable plans. The macro direction is clear: earbuds are a platform business in formation. Firms that align product, supply, and regulatory strategy in 2026 will disproportionately capture the next phase of value creation in this expanding category.
For detailed analysis of this topic, please visit the official page: Earbuds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com