

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Yeast Market Hits USD 9.65 Billion by 2032 at 6.9% CAGR

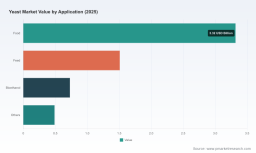
Yeast Market 2026: Strategic Intelligence for Decision-Makers
As global supply chains normalize from pandemic-era disruptions and industry players recalibrate for sustainability and efficiency, the yeast market is entering a decisive phase. PW Consulting’s Yeast Market study — anchored on a 2025 base year and projecting through 2032 — quantifies that transition: the global market grew from roughly USD 4.3 billion in 2020 to approximately USD 6.05 billion in 2025 and is forecast to approach about USD 9.65 billion by 2032, reflecting a compound annual growth rate of 6.9% across the 2026–2032 forecast window. For executives plotting investments, supply strategies or M&A in 2026, this report converts macro momentum into operational levers, risk-mapped scenarios and transaction-ready intelligence.
Yeast Market
Why this study matters for 2026 strategic planning
-
Market inflection point: Growth is broad-based but shaped by rapidly changing feedstock availability, evolving regulatory complexity and shifting end-market demand profiles (food, feed, biofuel and specialty applications). Understanding where demand accelerates vs. where margin compression occurs is critical to capital allocation decisions in 2026.
Yeast Market -
Supply-side volatility: Recent reductions in key sugar feedstocks and a reduced supplier willingness to absorb raw-material price volatility mean procurement strategies that worked historically will underperform. The study models these dynamics and offers contract and hedging templates tailored to different risk appetites.
Yeast Market -
Regulatory and certification friction: Tighter food-safety and organic certification regimes across multiple jurisdictions increase time-to-market and operational overhead for new product introductions and for smaller manufacturers seeking cross-border expansion. The report provides a prioritized compliance roadmap for market entry and scale.
-
Fragmentation presents opportunity: With market concentration low by global ingredient standards, there are distinct niches where scale, specialization or vertical integration unlock outsized returns. We highlight playbooks for both scale-seeking incumbents and fast-moving challengers.
What the report delivers — practical, transaction-ready intelligence
-
Transparent market-sizing and trend decomposition: A verified historical base (2020–2025) and granular forecasting framework (2026–2032) with scenario variants (base, downside, upside) tied to raw-material availability, regulatory shifts and adoption curves across end uses.
-
Value-chain cost curves and margin benchmarks: Comparative unit economics across fermentation platforms, drying technologies and downstream processing options to inform CAPEX and product-pricing decisions.
-
Supplier and buyer playbooks: Negotiation checklists, contract clauses for raw-material pass-through, contingency sourcing matrices and supplier risk-scoring to reduce procurement exposure.
-
Regulatory and certification matrix: Country-by-country practical requirements, timelines and estimated compliance costs — and an action plan to accelerate organic/specialty labeling or feed approvals.
-
Commercial expansion blueprints: Channel prioritization, pricing pilots, private-label vs. co-manufacturing decision guides and sales-force resource models for agrifood and industrial buyers.
-
M&A and partnership dossiers: A short-list of targets by strategic rationale (scale, technology, feedstock access, geographic reach), backed by valuation frameworks and integration risk assessments.
-
Interactive tools: Scenario models, sensitivity dashboards, and an executive one-page strategy template to use in board-level decision sessions.
Competitive landscape — who to watch and why
The yeast market remains relatively fragmented: our concentration analysis shows that the top three players account for less than a quarter of total market share, and the top five for around a quarter. That fragmentation creates distinct battlegrounds — scale advantages in commodity baking yeast, and differentiated upside in specialty and beverage yeasts.
-
Lesaffre — Global reach and breadth across baking, brewing and nutritional segments position Lesaffre as the default scale operator. Their premium brands and extensive product formats make them a natural consolidator in markets where distribution efficiency matters.
-
Lallemand — Known for specialty yeast and fermentation inputs, Lallemand’s strategic acquisition activity (notably a recent tuck-in that broadens its bio-ingredients portfolio) signals an ambition to accelerate capabilities in high-value segments and vertical integration in fermentation inputs.
-
Angel Yeast — Rapid capacity expansion and a strong position across food and feed markets from a China base make Angel Yeast a pivotal supply-side actor. New specialty facility ramps demonstrate a playbook focused on cost-competitive scale plus product diversification for local and export markets.
-
AB Mauri / Associated British Foods — The combination of AB Mauri’s brand portfolio and Associated British Foods’ manufacturing footprint (dozens of global plants) gives this group resilience in supply reliability and route-to-market for baking ingredients.
-
Fermentis (Lesaffre’s beverage arm) — A focused player in beverage yeast and fermentation solutions, Fermentis illustrates the pull toward specialization where technical service and strain portfolios command premium pricing.
Strategic implication: expect selective consolidation and continued parallel paths — scale players expanding into specialties through acquisitions, and agile specialists pursuing geographic expansion or partnerships to access new feedstocks and channels.
Market dynamics and near-term shocks to model
-
Feedstock pressure : USDA reporting in 2026 highlighted a meaningful downshift in beet sugar production versus the prior year. That decline tightens molasses and sugar-based substrate availability and raises input-cost volatility for conventional yeast production. Companies must stress-test models for both price and availability shocks.
-
Supplier contract inertia : Manufacturers are increasingly unwilling to absorb raw-material volatility into annual fixed-price contracts. Expect a shift to shorter-term indexing, variable pass-through clauses and supplier co-investment in risk-mitigation (e.g., forward purchases, strategic storage).
-
Regulatory complexity : Tighter food safety regimes and multi-region organic/certification barriers slow time-to-market, particularly for small and mid-sized producers seeking cross-border growth. In contrast, stringent feed quality standards in key markets (for example, the UK) are creating premium niches for certified feed yeast products.
-
Demand-side evolution : Consumer preferences for clean-label, non-GMO and sustainably produced ingredients favor manufacturers able to demonstrate traceability and low-carbon credentials. At the same time, industrial demand (bioethanol, feed) will continue to anchor base volumes.
Strategic playbook for 2026
-
Rebuild procurement agility: Move from annual fixed-price contracts to mixed-tenor approaches (short-term indexed + hedged forward volumes). Build optionality into feedstock sourcing and consider tolling or co-location with sugar/refinery partners to secure substrate access.
-
Prioritize product and market bifurcation: Allocate R&D and commercial resources across two tracks — (1) high-margin specialty yeasts and fermentation solutions with technical services; (2) efficiency-driven commodity production optimized for scale and low-cost feedstocks.
-
Targeted CAPEX and asset-light expansion: For 2026, prefer modular capacity investments and co-investment models (JVs, off-take-linked facilities) to reduce execution risk and accelerate time-to-market.
-
M&A discipline: Pursue acquisitions that immediately fill capability gaps (strain libraries, drying or culturing technology, feedstock contracts) rather than trophy assets that require lengthy integrations. Our M&A playbook ranks targets by synergy potential, integration complexity and cash conversion timelines.
-
Compliance and certifications as commercial levers: Invest selectively in certifications that unlock premium channels — especially feed and certain food segments where buyers are willing to pay for assurance.
-
Sustainability and traceability: Develop a low-carbon narrative grounded in measurable interventions (energy efficiency in drying, waste-to-energy valorization, feedstock diversification) to protect pricing and meet buyer ESG criteria.
-
Digital and process optimization: Deploy process analytics to improve yield, reduce batch variability and shorten fermentation cycles — cost advantages that compound quickly at scale.
Conclusion — how to use this study in 2026
For boards and executive teams making allocation decisions in 2026, the difference between value creation and underperformance will be the quality of scenario planning and the speed with which procurement, product and regulatory strategies are executed. PW Consulting’s Yeast Market study supplies both the macro roadmap (verified market size and growth trajectory) and the micro playbooks (cost curves, contract templates, M&A shortlists and compliance matrices) required to translate strategy into execution.
We intentionally present high-level directional signals here; the full study contains the detailed segmentation dashboards, scenario models, supplier heatmaps and transaction-target dossiers that will enable decisive action. To access the complete dataset, interactive models and tailored strategy workshops for your team, visit our report page or contact our lead industry advisors.
For detailed analysis of this topic, please visit the official page: Yeast Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com