

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Viscose Fiber Market Poised for 5.2% CAGR Through 2032 — PW Consulting Insight

Viscose Fiber Market — 2026 Strategic Preview for Executive Decisions
Introduction: why this preview matters for 2026
The global viscose fiber market has entered a phase where sustainability, regulation and supply-chain economics intersect with medium-term demand growth. Our base-year analysis shows the market expanding from roughly USD 10.2 billion in 2020 to USD 16.9 billion in 2025; the outlook through the 2026–2032 forecast window implies a continued compound annual growth at approximately 5.2%, reaching an estimated USD 24.0 billion by 2032. For corporate leaders planning capital allocation, procurement contracts, portfolio premiumization or M&A activity in 2026, this research functions as a decision-grade intelligence product: it translates market dynamics into actionable choices and prioritized risks.
Viscose Fiber Market
What’s changing now — the high-impact drivers
-
Raw-material economics: Pulp price volatility is an immediate margin lever. Recent price observations (Northern bleached softwood kraft pulp averaging around USD 1,590/tonne in North America and USD 1,656/tonne in Europe, as of April 2026) materially affect viscose cost curves and contract negotiations across the value chain.
Viscose Fiber Market -
Regulatory tightening: Authorities are moving beyond guidance into prescriptive requirements. The EU Best Available Techniques (BAT) framework for viscose/modal manufacturing now mandates environmental performance audits and closed-loop process systems — a move that will reshape capital investment programs and operating cost profiles for European-based or Europe-serving facilities.
Viscose Fiber Market -
Sustainable feedstock and certification: The industry is already scaling certified forest-based feedstocks — Textile Exchange data shows that a majority of MMCF production used FSC- or PEFC-certified feedstock in 2024. That scale creates both supply opportunities and compliance thresholds for brands and fiber producers.
-
Market structure and competitive pressure: The market exhibits measurable concentration at the top: the leading three and five suppliers together control a majority share, giving them pricing and technology-leverage advantages. Yet meaningful white space and niche-specialty opportunities remain for vertically integrated and specialty-focused players.
What the full report delivers — practical, transaction-ready content
Our full PW Consulting Viscose Fiber Market report is designed as a tool-kit for 2026 decision cycles. Highlights include:
-
Market sizing and validated forecast model (base year 2025; historical series 2020–2025; forecast 2026–2032) — with downloadable scenario modules that let you re-run the outlook under alternate pulp-price, demand and regulatory trajectories.
-
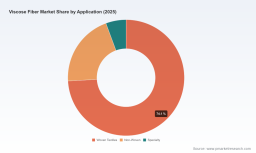
Segmentation that matters to commercial strategy: by region, product type (staple vs. filament), and application (textiles, nonwovens, specialty uses). The preview intentionally omits detailed split tables to preserve research value; however, the full dataset includes decomposed revenue, volume and unit-price assumptions to support channel-level decisions.
-
Supplier cost-stack and margin analytics — including a sensitivity matrix highlighting the breakeven impact of +/- 10–20% pulp-price moves on typical viscose grades.
-
Regulatory and permitting playbook — country- and region-level timelines for BAT-equivalent implementation, compliance capex estimates and operational milestones that procurement and compliance teams must track.
-
Go-to-market modules for value-capture: product premiumization, brand partnerships for certified feedstock, route-to-market for specialty nonwoven and hygiene segments, and price-setting guidance for blended recycled / virgin mixes.
-
Commercial diligence packages for M&A and JV activity: target screening, scorecards, synergy levers, and integration risk checklists designed for rapid execution in 90–120 day windows.
Competitive landscape — who matters and why
The market mix combines global integrated incumbents, regional champions and specialty producers. Top-tier players leverage scale, proprietary specialty grades and certification credentials to defend margins; mid-tier and regional producers focus on cost-advantaged feedstocks and proximity to textile clusters. Notable strategic profiles we track include:
-
LENZING AG (Austria) — A clear leader in premium and specialty sustainable viscose (LENZING™ ECOVERO™). Their strategy in 2025–26 emphasizes premiumization and portfolio rationalization; management actions include strategic reviews of selected assets (e.g., Indonesian site considerations) to sharpen competitiveness and margin profile.
-
Grasim Industries Limited / Birla Cellulose (India) — Large-scale production capability with a focus on diversified viscose staple fiber and specialty grades for apparel and activewear. Their operating model combines scale with backward integration into pulp and raw materials.
-
Sateri (China) — Integrated upstream-to-downstream viscose producer investing in footprint expansion while emphasizing lower environmental impact grades to serve hygiene and apparel customers.
-
Kelheim Fibers (Germany) — Specialist in hygiene-focused viscose, maintaining a strategic position in tampon and menstrual product fiber markets; their product focus insulates them from pure commodity cycles.
-
Asahi Kasei Corporation (Japan) — Technology-led producer with modal and high-tenacity viscose grades, positioned to capture technical textile applications and higher-margin specialty channels.
-
China-based integrated players (e.g., Xinjiang Zhongtai, Tangshan Sanyou Xingda, Xinxiang Bailu) — These companies combine export orientation with increasing sustainability partnerships. Recent activity includes strategic alliances to commercialize recycled pulp and certify feedstocks; for example, Tangshan Sanyou announced a commercialization partnership with Circulose to accelerate recycled-pulp integration.
Recent moves to watch (implications for 2026 planning)
-
Lenzing’s late-2025 strategic review of selected production sites signals that premium players will reallocate capital toward specialty lines and services, and away from low-margin commodity capacity unless efficiency or feedstock improvements are realized.
-
Tangshan Sanyou’s partnership to commercialize recycled pulp highlights a fast-emerging supply plurality: recycled or waste-derived feedstock will no longer be experimental but a near-term sourcing modality that affects long-term feedstock contracts.
-
Market concentration metrics (leading 3 players ~56% and top 5 ~60%) indicate a stable top-tier influence, but they also expose the market to tactical disruption if a major incumbent changes pricing, certifications or feedstock strategy.
Strategic implications and recommended 2026 actions
-
Procurement and commercial hedging — Treat pulp pricing as a core operational exposure. Negotiate indexed contracts with suppliers, test forward purchases for high-certification batches, and include pass-through clauses tied to published pulp indices.
-
Compliance-first CapEx planning — If operating or selling into Europe, prioritize BAT-equivalent retrofits for existing lines and design closed-loop systems into any greenfield projects. Factor BAT timelines into project IRR and permit risk assessments.
-
Product and margin strategy — Accelerate premiumization of branded and certified viscose lines where brand customers are willing to pay for documented sustainability and lower lifecycle impact. Preserve commodity positions via cost-leadership in low-margin channels.
-
M&A and JV playbook — Focus on targets that deliver either feedstock security (pulp assets, certified supply chains), technology differentiation (recycled pulp, closed-loop chemistry), or strategic access to high-growth application verticals (hygiene, technical nonwovens).
-
Operational resilience — Build near-term contingencies for supply-chain disruption (export restrictions, logistic bottlenecks) and develop dual-sourcing strategies in both certified and conventional pulp supplies.
KPIs and early-warning signals executives should track weekly/monthly
-
Pulp price indices and inventory days at key tier-1 suppliers.
-
Certification share of feedstock in supplier disclosures (FSC/PEFC penetration rates), R&D milestones for recycled feedstock commercialization.
-
Regulatory milestones and BAT audit schedules by jurisdiction; permit backlogs for new-build or retrofits.
-
Capacity announcements and strategic reviews from major players (M&A signals, capacity closures or divestments).
How to use this preview and next steps
This preview intentionally demonstrates the analytical depth available while preserving the report’s proprietary segment-level detail. The full PW Consulting Viscose Fiber Market report contains the decomposed regional and application splits, downloadable financial models, supplier-level cost curves, scenario stress-tests and a prioritized list of 20+ investment and sourcing actions tailored to different company archetypes (brand, fiber producer, trader, private equity). For teams preparing 2026 budgets, supplier negotiations, or acquisition screens, the report offers transaction-ready annexes and a 90-day execution playbook.
In 2026, decisions made on procurement terms, compliance capital, and product positioning will determine who captures the next wave of value as the market grows and its regulatory and sustainability contours harden. Use data-driven triggers, not anecdotes, to sequence spend — and treat certified feedstock access and closed-loop capability as strategic assets, not compliance overhead.
For detailed analysis of this topic, please visit the official page: Viscose Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com