

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Snow Helmet Market to rise from USD 320M (2025) to USD 405.53M by 2032 at 3.5% CAGR

Snow Helmet Market — 2026 Strategic Brief for Commercial Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a concise, practitioner-focused preview of our full Snow Helmet Market study. This briefing distills the macro dynamics, competitive geometry, and near-term strategic imperatives that will determine winning positions through 2026 and beyond. The objective is to convey the report’s strategic value for boardrooms and commercial teams while preserving the detailed segmentation and proprietary models that are available in the full report.
Snow Helmet Market
Why this study matters for 2026 decisions
Snow helmets are no longer a niche protective accessory; they sit at the intersection of consumer safety regulation, materials innovation, and experiential sports retailing. Our base-year assessment (2025) and multi-year forecast (2026–2032) show a market that has recovered from early-decade volatility and is tracking steady, mid-single-digit compound growth. In revenue terms (USD Million), the market expanded from an estimated 250.0 in 2020 to 320.0 in 2025, with a projected trajectory into the late 300s by the end of the current forecast window. The modeled compound annual growth rate for 2026–2032 is 3.5% — a reliable growth corridor but one that conceals meaningful variation by product architecture, channel, and regulatory exposure.
Snow Helmet Market
For executive teams planning product roadmaps, manufacturing capacity, channel investments, or M&A through 2026, this report translates that macro growth into prioritized, actionable options that balance upside capture with downside protection.
Snow Helmet Market
Market snapshot: trajectory and structural signals
-
Historical pattern: The market shows cyclical sensitivity tied to participation rates, travel and tourism activity, and equipment replacement cycles. After a dip in the early 2020s, recovery has been evident through 2024–2025 as consumer confidence and resort attendance normalized.
-
2025 vantage point: The 2025 base-year establishes a platform for planning — companies should treat it as the operational baseline for inventory, product launches, and certification timelines.
-
Forecast frame: Our 2026–2032 projection, underpinned by a 3.5% CAGR, anticipates incremental demand drivers (technology adoption, premiumization, safety regulation) offset by persistent headwinds (supply chain cost pressure, substitution in budget segments).
-
Market concentration: Top-tier players command a meaningful share of market value, with the three- and five-firm concentration metrics indicating moderate-to-high concentration. This structure rewards differentiated product features, channel control, and brand cachet.
Key dynamics shaping 2026 outcomes
-
Regulatory tightening and certification harmonization: Safety standards remain a market anchor. In core markets, ASTM F2040 and CE EN 1077 continue to define minimum acceptance. New country-level mandates (for example, a recently introduced national skiing helmet requirement in Italy) and retailer certification checks reinforce demand for compliant, test-documented SKUs. For manufacturers and distributors, certification lead times and compliant documentation are now material go/no-go constraints for market entry.
-
Technology migration — MIPS and beyond: Rotational-impact mitigation systems have migrated from premium niches to mainstream consideration. Pairing these systems with lighter shells and ventilation systems is the current engineering frontier. Players who can demonstrate validated, field-proven impact performance gain negotiating leverage with specialty retailers and rental operators.
-
Materials and sustainability: The market shows rising interest in recycled content and alternative polymers, driven by consumer preferences and upstream supplier commitments. Material selection affects weight, cost-to-manufacture, and recyclability; each is a trade-off with clear commercial consequences.
-
Channel bifurcation: Retail remains split between specialty brick-and-mortar, direct-to-consumer digital, and the public rental channel. Each demands a distinct product set and pricing structure: rental fleets emphasize durability and cleanability, specialty retail emphasizes fit and tech features, and DTC emphasizes margin and brand storytelling.
-
Experience-driven premiumization: Consumers are willing to pay premiums for comfort, integration (goggle/helmet systems), and features such as ventilation and audio compatibility — but willingness is skewed toward experienced skiers and snowboarders rather than casual participants.
Competitive landscape — positioning and strategic options
The market is populated by well-established technical brands and performance-oriented incumbents. The competitive set includes firms with strong R&D pedigree and differentiated brand equity. Notable competitors and their strategic postures include:
-
Smith Optics (Vail, Colorado): Strong product breadth with backcountry and full-face certified options; leverages MIPS integration and winter-sport heritage to command specialty retailer support.
-
Giro (Portland, Oregon): Emphasizes lightweight, performance-driven designs that target alpine and freestyle consumers; attractive to demographic segments seeking weight-to-protection trade-offs.
-
POC Sports (Örnsköldsvik, Sweden): Differentiates on rotational protection and visibility; premium safety messaging enables higher ASPs in targeted channels.
-
Salomon (Annecy, France) and Atomic (Dusseldorf, Germany): Strong winter-sport OEM/brand positioning linked to integrated equipment systems (skis/boots/helmets) — cross-selling is a core advantage.
-
Bern Helmets and Pret Helmets (U.S.): Niche players with sustainability narratives and community-driven design paths that resonate with younger, eco-conscious consumers.
-
Sweet Protection, Oakley, Bolle Safety: Each brings a specific strength — lightweight engineering, integration with optical systems, and safety certification emphasis, respectively.
Strategic implications: incumbents benefit from scale in certification, channel relationships, and co-marketing with resorts and specialty retailers. Medium-sized players can outflank by owning product niches (e.g., youth, backcountry, rental-grade durability) and by rapid adoption of verified safety tech.
Actionable recommendations for 2026
-
Prioritize certification pipeline and compliance as a first-order operational metric. For any market entry or product refresh in 2026, build certification timelines into the product-launch Gantt with contingency buffers for testing iterations.
-
Segment product architecture by channel: allocate R&D and inventory differently for rental fleets (durability, cost per use), specialty retail (fit and premium features), and DTC (margin optimization and personalization). Avoid a one-size-fits-all SKU strategy.
-
Invest in validated impact technology partnerships. Licensing or co-development of rotational-impact systems and lightweight shell composites delivers both technical differentiation and retailer credibility.
-
Make sustainability a measurable product attribute, not a marketing adjective. Define recycled-content thresholds, end-of-life take-back pilots, and supplier traceability standards — these factors materially affect procurement decisions by chains and specialty retailers in 2026.
-
Optimize pricing through channel-level economics analysis. Use tiered pricing disciplines that preserve rental margins while enabling aspirational pricing for direct-to-consumer premium offerings.
-
Consider bolt-on acquisitions to expand category depth or secure proprietary tech. Given the market’s moderate concentration, targeted M&A can accelerate access to certifications, distribution, or material technology without requiring scale-built organic growth.
-
Mitigate supply-chain exposure by dual-sourcing critical components (liners, MIPS rings, visor interfaces) and holding safety-stock tied to certification cycles rather than shipment dates.
What the full PW Consulting report delivers
-
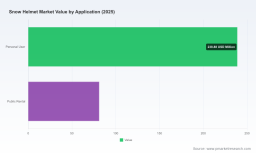
Granular, actionable dashboards that map revenue pools by product type, distribution channel, and buyer persona (note: the full report contains the detailed segmentation tables and revenue breakdowns that informed our strategic recommendations).
-
Validated competitive benchmarking, including SKU-level comparisons, certification matrices, and go-to-market strength scores for the principal firms named above.
-
Operational playbooks: SKU rationalization templates, certification project plans, and rental-fleet procurement models designed for immediate adoption by product and commercial teams.
-
Scenario-based financial models that stress-test pricing, raw-material inflation, and demand shocks across the forecast horizon (2026–2032) — enabling CFOs to evaluate CAPEX and working-capital implications.
-
Risk and compliance register focused on evolving regulatory regimes and retailer procurement standards — prescriptive mitigation steps for each identified regulatory exposure.
Methodology and confidence
This study uses a mix of primary interviews, channel checks, retailer compliance sampling, and PW Consulting’s proprietary demand-supply model calibrated to base-year 2025. The 2026–2032 projection rests on a 3.5% CAGR scenario that incorporates conservative participation-growth assumptions and explicit downside stress cases. Market concentration metrics reflect revenue-based shares among the largest competitors and are used to identify pockets of competitive advantage and consolidation opportunities.
Closing and how to use this intelligence
For 2026 planning cycles, our analysis shows that companies who align product certification, material innovation, and channel-specific SKUs will gain disproportionate returns relative to peers who apply broad, undifferentiated product strategies. The full Snow Helmet Market report from PW Consulting translates the macro numbers and competitive insights summarized here into executable roadmaps — from SKU-level launch checklists to M&A target screens and financial sensitivity tables. If you are preparing budgets, supply-chain commitments, or product-launch calendars for 2026, this is the actionable intelligence you should anchor to.
To access the complete dataset, segmentation matrices, and the operational toolkits referenced above, please visit the PW Consulting report page — the full analysis contains the segment-level figures and models essential for transaction due diligence and operational implementation.
For detailed analysis of this topic, please visit the official page: Snow Helmet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com