

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
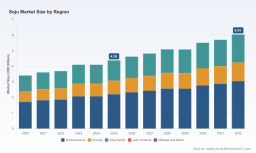
PW Consulting: Soju Market to Reach USD 6.04 Billion by 2032 (CAGR 4.42%)

Soju Market 2026: Strategic Imperatives for Growth, Differentiation and Resilience
As leading consultants at PW Consulting, we present an executive primer to our full Soju Market study designed to influence the most consequential commercial decisions companies will make in 2026. The global soju market has evolved from a regionally concentrated spirit into a commercially dynamic category shaped by premiumization, flavor innovation, cross-border distribution partnerships, and regulatory complexity. Our full report—built on a 2020–2025 historical baseline and a 2026–2032 forecast—quantifies these dynamics and translates them into actionable choices for brand owners, distributors, investors and contract manufacturers.
Soju Market
Why this study matters for 2026 decision-makers
-
Timing: The industry stands at an inflection point. With the market recovering and expanding from recent years, leaders must align commercial strategy to capture structural growth rather than temporary spikes.
Soju Market -
Clarity: Our modelling shows continued market expansion through the forecast horizon at a compound annual growth rate (CAGR) of approximately 4.42%. The global market base (2025) sits in the low single-digit billions (USD), with a projected progression toward north of USD 6.0 billion by 2032—clear evidence that soju is no longer a niche export curiosity but an investible beverage category.
Soju Market -
Strategic levers: The next wave of value accrues to actors who can combine export channel engineering, product-line sophistication (premium and low‑alcohol offerings), and operational scale—while navigating entrenched distribution rules in key origin markets.
What the full report delivers (practical, deal-ready content)
-
Quantified market sizing and forecast model (2020–2032) with sensitivity scenarios tied to export tariffs, ingredient cost inflation and channel-mix shifts.
-
Revenue-by-segment modelling (product type, consumption occasion and geography) and a downloadable dataset for use in internal planning tools and investor diligence.
-
Value chain unit economics and cost-to-serve analyses that identify where margin compression is most acute—from raw-material exposure to distribution intermediaries.
-
Commercial playbooks for five corporate archetypes: global incumbent, regional challenger, craft distiller, private-label/OEM specialist and retail-led importer/distributor.
-
Regulatory & compliance radar with mitigation strategies for markets where mandatory intermediary distribution or licensing creates entry friction.
-
Opportunity maps for partnership, capacity expansion and M&A—prioritized by ROI, execution complexity and time-to-market.
Market dynamics and the competitive landscape
The category is concentrated but evolving. Leading producers retain meaningful share thanks to scale in production, established domestic channels and growing export networks. Measured concentration metrics indicate a market where the top three players capture a significant share of overall volume, while the top five broaden that dominance—creating both entry barriers and consolidation opportunities.
Core competitive behaviors to watch in 2026:
-
Capacity expansion outside of Korea as a strategic hedge. Large incumbents are investing in manufacturing footprints in Southeast Asia to diversify cost exposure and accelerate supply to growing export markets.
-
Premiumization and ingredient transparency. Premium distilled soju and organic/rice‑based variants are being positioned as cross-over spirits for Western cocktail culture, supported by carefully curated provenance and higher ABV options.
-
Flavor-driven extension and health positioning. Low-alcohol and flavored variants continue to proliferate, appealing to younger and health-oriented consumers—an axis of growth that supports higher SKU counts and retail listings.
-
Private-label and OEM activity. Specialist suppliers are leveraging artisanal flavor libraries and contract manufacturing to supply international retailers and challenger brands.
Profiles in strategy: what leading companies reveal
-
HiteJinro (Seoul) remains the archetype of scale-led expansion—balancing domestic leadership with export acceleration. Its targeted capex to increase annual output in external facilities demonstrates an industry tendency to move production footprint nearer to growth geographies and favorable input markets.
-
Lotte Chilsung Beverage leverages formulation innovation (e.g., alkaline-reduced water processes) and distribution breadth—illustrating how incremental product science and channel strength can defend share and open premium shelf space.
-
Specialist players such as Muhak, Hwayo and Minhwa Spirits showcase differentiated positioning: low-alcohol and fruit-flavored mainstream extensions, and premium rice-distilled variants aimed at cocktail and gifting segments. These firms validate the category’s bifurcation between volume and value plays.
-
Woongjin Foods and other flavor-focused brands highlight the importance of trade-show visibility and cross-border showcase strategies for entering foodservice and international retail networks.
-
US- and export-oriented entrants (e.g., Yobo Soju) emphasize ingredient provenance and organic claims—tactics that accelerate acceptance in Western markets where consumers prize traceability.
-
Realtrade and other private-label specialists underline a growing channel for retailers and restaurants seeking bespoke SKUs without incurring the R&D and CAPEX of production facilities.
Regulatory and input-cost headwinds—implications for strategy
Two structural constraints are shaping choices in 2026. First, distribution regulation in some origin markets mandates intermediary stages that restrict direct-to-consumer and direct-import approaches, preserving margins for licensed wholesalers and raising market-entry costs for small-scale producers. Second, feedstock and neutral‑spirit sourcing drive production cost variability. Historical constraints around rice distillation and continued reliance on ethanol from alternative sources (potatoes, tapioca, sugarcane) leave manufacturers exposed to commodity cycles.
Strategic responses we outline in the report:
-
Channel engineering: build hybrid distribution models that combine local wholesale compliance with exporter contracts and digital DTC where regulation permits.
-
Input hedging and co‑sourcing: diversify raw-material suppliers and evaluate co-location of key inputs to lower landed cost and protect margins.
-
Manufacturing footprint selection: use production sites in trade-friendly jurisdictions to capture tariff arbitrage and reduce lead times for high-growth export markets.
Commercial playbook: five priority moves for 2026
-
Prioritize premium and functional variants in new listings. Shelf competition is shifting from price to storytelling—brands that can credibly position rice-distilled or organic credentials will secure higher per-unit margins.
-
Close the distribution gap to the US and Europe. Recent trade partnerships and tariff improvements have accelerated exports; companies that convert export interest into permanent distribution agreements will outperform peers.
-
Scale selectively with contract manufacturers. Use OEM partners to trial new flavors and low‑alcohol SKUs before committing manufacturing capex—this reduces time-to-market and preserves cash during concept validation.
-
Invest in supply-chain resilience. The combination of labor and capital intensity in distillation requires preventive maintenance regimes and contingency plans for feedstock shocks.
-
Use M&A tactically to fill capability gaps: distribution networks, local regulatory know-how, or flavor R&D labs—especially in high-growth export corridors.
Case examples that illustrate execution risk and opportunity
-
Plant expansions targeted for operation in the mid-to-late 2020s show how capacity plays are used to defend global ambitions—yet timing and construction risk can create temporary oversupply or missed market windows.
-
Trade-show activations and limited-edition product launches demonstrate low-cost routes to test premium positioning and build awareness ahead of broader rollouts.
-
Private-label manufacturers with broad flavor portfolios offer a low-risk path to retail penetration for importers and supermarkets—however, margin and brand control trade-offs must be negotiated carefully.
Where our dataset will be most valuable
Executives will find the full dataset and scenario tools especially useful for:
-
Investment committees assessing capex for new facilities or cross-border M&A.
-
Commercial teams building pricing and promotion plans by channel and occasion.
-
Product teams prioritizing SKUs and roadmap sequencing (e.g., flavored lines vs. premium distilled launches).
-
Supply-chain managers optimizing sourcing and hedging strategies to buffer feedstock volatility.
Concluding perspective: positioning for durable advantage
Soju’s expansion from a regionally anchored spirit into a category with multi-market growth potential is no accident. The category combines a broad consumer appeal—driven by approachable flavor profiles and increasing premiumization—with attractive routings into cocktails, retail and foodservice. Yet the path to durable advantage is neither automatic nor uniform. In 2026, boards and executive teams must choose between competing pathways: volume-led scale, margin-led premiumization, or partnership-driven geographic expansion. Our research codifies the trade-offs, quantifies the returns and maps the playbooks for each choice.
This primer highlights the strategic contours. The full PW Consulting Soju Market report contains the granular segment tables, scenario outputs and templates that companies need to translate these insights into investment decisions and operational roadmaps. For market entrants and incumbents alike, the question in 2026 is not whether the category grows—the data is clear—but how you structure your activities now to capture the disproportionate share of that growth.
For detailed analysis of this topic, please visit the official page: Soju Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com