

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gabion Boxes Market to Reach USD 269.98 Million by 2032 at 5.3% CAGR

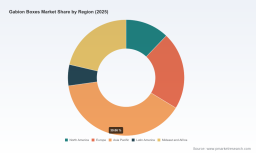
Gabion Boxes Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our Gabion Boxes Market study designed to guide capital allocation, procurement strategy, and product development decisions in 2026. The market’s trajectory is clear: after an expanding 2020–2025 base, the gabion boxes market continues to grow into the next decade. Our modelling shows the industry expanding from an estimated USD 188.02 Million in 2025 to roughly USD 270.0 Million by 2032, at a compound annual growth rate (CAGR) of 5.3% across the 2026–2032 forecast horizon. This preview synthesizes the dynamics that will matter to executives — regulations and standards, input-cost sensitivity, competitive positioning, and pragmatic playbooks that transform insight into action — while reserving the granular segment and regional tables for the full report.
Gabion Boxes Market
Why this market matters to 2026 corporate strategy
-
Infrastructure momentum. Governments and large owners continue to prioritise erosion control, hydraulic infrastructure, and resilient roadside assets. The gabion segment sits at the intersection of civil engineering and landscape architecture, creating stable demand from both heavy civil and light landscaping projects.
Gabion Boxes Market -
Standards-driven procurement. New and updated standards are reframing procurement specifications, tightening mechanical, coating and installation requirements. Buyers that react early to these changes preserve margin and reduce specification risk.
Gabion Boxes Market -
Input-cost exposure. Gabion manufacturing is steel- and labour-intensive: raw material price swings, coating-cost volatility, and logistics inflation materially affect unit economics. Firms that embed forward-looking material-price hedges and lean processing see disproportionate margin resilience.
-
Concentration and consolidation opportunity. The market exhibits a moderate level of concentration among established suppliers. This opens options for both consolidation and regional disintermediation: larger buyers can secure preferred pricing through supplier rationalisation; niche players can specialise in higher-value architectural or marine-grade offerings.
Market momentum: the numbers you can act on
We anchor strategic planning in reliable macro magnitudes. After incremental growth through 2020–2025, our base-year calibration (2025) and forward-looking scenario workpoint to sustained mid-single-digit annual growth (CAGR 5.3%) through 2032. That trajectory supports multi-year investments in capacity, specification-focussed product lines, and targeted commercial expansion — assuming firms manage material-cost exposure and compliance changes. Market concentration metrics indicate that the top three suppliers account for just over half of total industry revenue, while the top five approach two-thirds of the market — an important signal when considering scale-based bidding and distribution partnerships.
Regulation, standards, and procurement dynamics
-
Standards update risk/opportunity: The October 2025 Austroads ATS-5150-25 specification (edition 1.1) and ongoing references to ASTM and EN regime requirements are reshaping public and private tender specifications. Buyers will increasingly demand traceable compliance and documented installation methodologies when awarding civil works contracts.
-
Specification-driven differentiation: Suppliers that can demonstrate compliance with ASTM A974/A975 and relevant EN standards, and that can present installation guides and QA documentation, win longer-term framework agreements with DOTs and infrastructure owners.
-
Procurement friction: Municipal and park RFQs are now common; recent public procurement activity in conservation and park infrastructure shows administrators are prepared to change supplier lists if a clear life-cycle cost advantage exists.
Cost structure and material dynamics
Operational modelling from independent plant studies shows raw materials account for the dominant share of production cost. This concentration implies that even modest swings in steel price, zinc-plating premiums, or PVC-coating input costs materially affect margins. Our scenario work includes sensitivity runs across realistic steel and coating price paths, enabling procurement teams to stress-test supplier quotes and contractual clauses across multi-year frameworks.
Competitive landscape — who matters and why
The competitive field is a mix of specialised OEMs, regional producers, and distributors. Key players differentiate along four vectors: standards compliance and specification pedigree; product breadth (welded vs woven; mesh finishes; marine-grade); channel reach (national distribution vs local manufacturing); and value-add services (cut-to-size, fastening systems, installation accessories). Highlights from our company analysis include:
-
Gabion Supply (US) — Known for ASTM-compliant welded and woven baskets and a strong civil-contract channel serving DOTs and forest services. Their emphasis on DuraWeld/DuraFlex product lines secures large, standards-focused accounts.
-
Gabion Pros (US) — Positions with branded welded/woven systems and marine-grade options; competitive where customised finishes and architectural cladding intersect with civil projects.
-
Ferguson Waterworks (US distributor) — Acts as an important channel for established OEMs, enabling scale distribution of legacy brands into erosion-control and hydraulic projects.
-
Fine Mesh Metals (UK) — UK/European compliance specialist producing Galfan-coated welded units to EN and national transport standards; strong in coastal and defence applications.
-
Regional manufacturers across India, China, Middle East — offer competitive pricing and local supply advantages for large-volume infrastructure programmes; several are expanding capabilities and, in some cases, listing publicly to fund capacity growth.
Collectively, these firms illustrate the spectrum of competitive moves: compliance-led premium supply, distribution-led scale plays, and low-cost regional manufacturing. Each profile in the full report includes capability matrices, recent contracts, and suggested engagement strategies for buyers and potential investors.
Recent developments that should influence your 2026 playbook
-
Standards publication and tender signals (Austroads ATS-5150-25, Oct 2025) have changed minimum supply and installation expectations for rock-filled gabions — review technical specs now to avoid being disqualified in public tenders.
-
Public procurement notices in conservation and park infrastructure point to fresh demand pockets where life-cycle cost arguments (stability, low maintenance) are persuasive.
-
Market entrants and capital moves (public listings and capacity expansions) indicate continued industry investment; mapping which entrants are scaling high-quality production vs. low-cost volume is critical to sourcing decisions.
-
Independent analyses show material-coating choices and pre-treatment routes are changing buyer preferences in coastal and chemical environments; product managers should prioritise tested corrosion-resistance solutions in high-exposure tenders.
What PW Consulting’s report delivers (practical content)
Our full study is designed to be operationally actionable for commercial, procurement, engineering, and M&A teams. Key inclusions are:
-
Validated market sizing and forward forecasts (2026–2032) with scenario bands that support budgeting and capacity planning.
-
Standard-compliance checklists and tender-ready specification templates mapped to ASTM, EN, and recent Austroads updates.
-
Raw-material sensitivity models allowing users to test margin outcomes under alternate steel and coating price pathways.
-
Supplier capability profiles and vendor scorecards with recommended negotiation levers and sample contract clauses to manage quality and lead times.
-
Commercial playbooks for manufacturers and distributors: premium-specification strategy, low-cost volume scale-out, and hybrid channel models into infrastructure procurement.
-
M&A target shortlist and diligence frameworks calibrated to the market’s concentration profile and margin dynamics.
How executives should use these insights in 2026
-
Procurement leaders: re-run supplier RFQs with the new standards checklist and include coating-specific lifecycle comparisons. Layer price quotes with our material-cost scenarios to evaluate true cost of ownership.
-
Product and engineering teams: prioritise development of offerings that simplify compliance (pre-certified assemblies, installation packs) and reduce site labor — these reduce whole-life costs and accelerate specification wins.
-
Investment and corporate development: consider selective consolidation in regions where scale delivers tender-winning economics, and pursue bolt-on capabilities that add specification compliance or onsite installation services.
-
Operations and sourcing: implement hedging or supplier commitments to mitigate raw-material swings, and evaluate nearshoring where lead-time sensitivity and freight costs erode margin.
Methodology and data confidence
The report’s base year is 2025, with historical reconciliation from 2020–2025 and forecast scenarios through 2032. PW Consulting synthesises public tender data, supplier financials, standards publications, proprietary installer surveys, and primary interviews across procurement, engineering, and manufacturing. We validate price and cost inputs with independent plant-build studies and third-party material-price feeds. For readers requiring model access or a custom scenario run, the full engagement includes an interactive spreadsheet and sensitivity dashboards.
Next steps — where to find the detailed intelligence
This preview provides the strategic framing and the decision levers you need for 2026. For granular regional splits, product-type forecasts, application-level demand tables, and downloadable vendor scorecards, download the full PW Consulting Gabion Boxes Market report. The complete package includes the underlying data model, customizable scenarios, and a supplier negotiation playbook crafted to convert these insights into measurable procurement and commercial outcomes.
For detailed analysis of this topic, please visit the official page: Gabion Boxes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com