

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
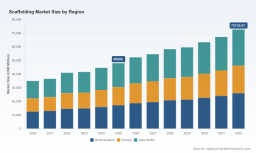
PW Consulting: Scaffolding Market set to hit USD 72,735.07 Million by 2032 at 6.18% CAGR

Scaffolding Market 2026: Strategic Imperatives for Decision‑Makers
Executive snapshot
As the scaffolding sector enters the next phase of expansion, PW Consulting’s latest market research — with base year 2025 and a historical lens covering 2020–2025 — provides the forward view companies need to plan through 2032. The market was sized at approximately USD 48 billion in 2025 and, at a compound annual growth rate of 6.18% for the 2026–2032 forecast horizon, is projected to approach the low‑seventies billion-dollar range by the end of the period. Those headline figures understate the strategic complexity beneath: the market blends equipment manufacturing, rental economics, engineering services, regulatory compliance and raw‑material exposure in ways that materially affect margin, capital allocation and competitive positioning.
Scaffolding Market
Why this matters for boards and operators in 2026
-
Capital allocation: investment decisions on fleet ownership versus rental are no longer binary. Equipment capex, total cost of ownership, service bundles and lifecycle replacement profiles all need to be stress‑tested against multi‑scenario demand paths.
Scaffolding Market -
Margin pressure from input costs: structural steel and aluminum price dynamics are a persistent margin lever. In 2026 structural steel escalation was observed in the mid‑single digits, and aluminum pricing remains a high‑visibility cost driver — both directly impacting OEM and rental networks’ cost bases.
Scaffolding Market -
Regulatory and safety compliance: legislative and standards updates (for example, recent OSHA clarifications and updated UK guidance) are increasing the cost of compliance and raising the bar for inspection, training and traceability — turning safety into a commercial differentiator.
-
Consolidation and concentration: the market shows clear consolidation among established global players alongside a fragmented long tail of regional providers. Competitive moves by large, vertically integrated firms create knock‑on effects for pricing, service standards and customer expectations.
What our report delivers — practical, transaction‑ready analysis
This study is structured to move leaders from insight to action. Key components include:
-
Robust market-sizing and scenario forecasts (base year 2025, historical trend 2020–2025, forecast 2026–2032) with demand drivers decomposed by macroeconomic, construction‑cycle and regulatory vectors.
-
Supply‑side diagnostics covering manufacturing capacity, material cost pass‑through mechanics, and rental fleet utilization models that quantify earnings sensitivity to utilization and pricing changes.
-
Go‑to‑market playbooks for manufacturers, rental providers and service specialists: channel economics, pricing strategy, bundling of engineering and inspection services, and aftermarket parts strategies.
-
Vendor assessment and competitive benchmarking featuring scorecards across technology, service breadth, geographic reach and balance‑sheet strength — designed for commercial diligence or partnership screening.
-
Regulatory and safety impact analysis, including the operational implications of recent OSHA provisions and updated industry guidelines, with checklists for audit readiness and training investments.
-
M&A and partnership blueprints: accretion/dilution models, integration risk heatmaps and suggested structuring options for bolt‑on acquisitions or strategic alliances.
-
Practical appendices: unit economics templates, fleet replacement calculators, and a prioritized investment roadmap by use case (new construction, maintenance, events/temporary staging).
Competitive landscape — who matters and why
The market is characterized by a mix of global system suppliers, specialized modular manufacturers and large rental & services networks. Top established names combine manufacturing scale with service capabilities; specialist players focus on rapid‑assembly systems and niche engineering. In practice, the top tier of providers collectively controls a majority of commercial activity, creating a competitive dynamic where scale, service differentiation and network reach matter as much as product innovation.
Representative strategic archetypes observed in the market:
-
Global access and service integrators: firms that pair rental fleets with engineering, forming & shoring and project management services. Their competitive edge is an end‑to‑end offering that reduces customer coordination costs on complex projects.
-
Modular systems innovators: manufacturers specializing in fast‑assembly, lightweight systems that reduce onsite labour and schedule risk — particularly attractive where downtime and speed are the primary constraints.
-
Formwork and scaffolding hybrids: suppliers that package formwork, scaffolding and associated engineering as a single solution, addressing large civil and infrastructure projects where integrated systems lower interface risk.
-
Regional rental specialists: operators with deep local market knowledge, offering tailored services for maintenance and retrofit segments; they compete on responsiveness and bespoke engineering services.
Case in point: BrandSafway’s global access & rental model, Layher’s focus on modular lightweight systems, PERI’s integrated formwork + scaffolding approach, and large rental networks that emphasize fleet scale and service (for example, networked rental platforms). Complementing these are specialist engineering and installation firms that win through technical complexity handling and local compliance expertise.
Recent market signals and their implications
-
Trade shows and industry forums (recent events across Europe and Asia) signal intensified competition on modular systems and productivity‑improving temporary equipment. These venues have become labs for product validation and partner discovery.
-
Raw material volatility: recent months have shown single‑digit percentage swings in structural steel pricing and persistent aluminum price sensitivity — both demanding flexible procurement strategies and, where possible, indexed contracting.
-
Regulatory tightening: updated guidance in key jurisdictions has accelerated demand for enhanced inspection regimes and digital traceability, making investment in inspection technologies and training a payback candidate under both safety and commercial lenses.
Strategic playbook — actions to prioritize in 2026
-
Reassess fleet economics: run scenario TCO analyses comparing ownership, long‑term lease and hybrid rental models. Prioritize flexible capital structures if utilization risks remain uncertain.
-
Hedge input cost exposure: negotiate indexed supply contracts, explore alloy substitutions where feasible, and quantify the elasticity of demand to pass‑through of material cost increases.
-
Product‑service bundling: differentiate by offering engineered packages (scaffolding + inspection + digital reporting) that command premium pricing and deepen customer stickiness.
-
Invest selectively in modular and lightweight systems: these deliver differentiated labor savings and schedule compression benefits that matter on high‑value projects.
-
Operationalize compliance as a sales asset: convert inspection and training investments into client value propositions (audit‑ready reports, certified crews, shorter onboarding).
-
Explore M&A to fill capability gaps: target bolt‑ons that add regional coverage, specialized engineering skills, or proprietary modular systems rather than chasing pure scale alone.
-
Adopt digital maintenance and IoT pilots: use sensorized platforms and digital inspection to increase fleet uptime, reduce unscheduled repairs and open new data monetization pathways.
Why PW Consulting’s report is different — depth without noise
Our study combines granular scenario modeling, primary interviews with owners and operators, and vendor scorecards calibrated to transaction use cases. We provide executable templates (fleet optimization models, price sensitivity matrices and integration checklists) so that executives can move from insight to investment decisions within board cycles. To maintain commercial utility for clients and preserve the value of proprietary segmentation, the executive overview above intentionally omits granular regional and application‑level splits — those high‑resolution datasets and interactive models are included in the full report and the accompanying client portal.
Next steps for decision‑makers
For leadership teams preparing 2026 budgets, the priority is to align capital allocation with scenario stress tests: stress test fleet utilization, lock in procurement terms for critical alloys, and convert compliance investment into differentiated services. If you are evaluating M&A or strategic partnerships, focus on bolt‑on capabilities that directly improve utilization, reduce labor risk, or expand higher‑margin service offerings.
To access the full dataset, vendor scorecards and interactive models that underpin these recommendations — including the regional and application segmentation, and the detailed forecasts by type and material — please visit our research portal. PW Consulting’s Scaffolding Market report was built to be the operational playbook for 2026: granular where you need it, strategic where it counts.
For detailed analysis of this topic, please visit the official page: Scaffolding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com