

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Contrast Medium Market to reach USD 10.78B by 2032 at 7.9% CAGR

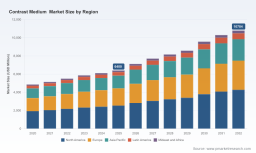
Contrast Medium Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As healthcare providers, imaging vendors, and life-sciences investors confront accelerating demand and shifting regulatory realities, the global contrast medium market stands at an inflection point. PW Consulting’s new Contrast Medium Market study (base year 2025) synthesizes historical trends and forward-looking scenarios to deliver the decision-grade intelligence executives need in 2026. At a macro level, the market expanded steadily from roughly USD 4.9 billion in 2020 to USD 6.4 billion in 2025, and our modeling projects growth to approximately USD 10.8 billion by 2032 — an implied compound annual growth rate (CAGR) of 7.9% across the 2026–2032 forecast window. This preview distills the practical strategic implications of those dynamics while preserving the report’s proprietary, segment-level detail for subscribers.
Contrast Medium Market
Why 2026 Is a Pivotal Year for Strategic Choice
Three converging forces make 2026 the year for decisive action: (1) resilient imaging volumes and demographic tailwinds, (2) technology and formulation innovation that reshapes clinical value, and (3) concentrated supply-chain investments and policy shifts that alter competitive advantage. For executive teams, the question is no longer whether the market will grow; it is how to capture disproportionate share and protect margins as competition intensifies and new entrants accelerate commercialization.
Contrast Medium Market
-
Market momentum: After consistent annual expansion through 2025, our forecasts show sustained mid-to-high single-digit growth. That trajectory supports capacity investments, but also raises the bar for operational rigor — winners will be those who align manufacturing scale with commercial precision.
Contrast Medium Market -
Clinical innovation: Beyond traditional iodinated and gadolinium agents, the pipeline and trial activity (including first-in-class manganese-based trials that entered Phase 2/3 under Fast Track designations in mid-2026) indicate an expanding product palette that will reframe modality economics and adoption curves.
-
Regulatory and access shifts: Recent approvals and first-generic rulings in major markets are compressing price dispersion and changing procurement dynamics — a mixed blessing for originators and an opportunity for agile manufacturers and contract partners.
Competitive Landscape: Incumbents, Specialists, and Regional Challengers
The market topology combines global platform players with specialized imaging firms and regional generic manufacturers. Established incumbents maintain broad modality portfolios and integrated channel relationships; specialist firms are leveraging formulation science and targeted clinical positioning; regional producers are pursuing cost-competitive strategies and regulatory footholds.
-
Platform incumbents: Large imaging companies continue to anchor the market through comprehensive portfolios and direct relationships with hospital systems. Recent strategic moves include substantial manufacturing investments to mitigate capacity risk and secure supply continuity, alongside late-stage clinical work to diversify modality options.
-
Specialists: Companies focused on macrocyclic agents and low-dose formulations are translating clinical differentiation into adoption in settings prioritizing patient safety and efficacy. Regulatory approvals in new jurisdictions during 2026 accelerated access for these products, supporting premium positioning.
-
Regional and generic players: Several manufacturers from Asia and other regions are expanding into key markets with cost-competitive generics and localized manufacturing that meets international standards. These entrants are changing tender dynamics and forcing incumbents to sharpen value-based contracting.
Recent company-level developments — from regulatory approvals in North America and India to clinical trial initiations and NMPA clearances — underscore a market where product life-cycle management and go-to-market agility matter as much as scale. Outsourced manufacturing partnerships and fill-and-finish contracts signed in 2025–2026 signal a structural shift: supply capacity is being reconfigured at pace with demand expectations.
Supply-Chain and Regulatory Dynamics: From Capacity Crunch to Contracting Power
Supply-chain rebalancing is now a central strategic variable. Large-scale investments in manufacturing capacity, including multi-million-dollar expansions in key European sites, reflect an industry response to projected doubling of certain product demand profiles. Simultaneously, contract manufacturing and fill-and-finish agreements are proliferating as firms optimize capital intensity and time-to-market.
-
Capacity planning: Companies that pre-emptively secure fill-and-finish partnerships or invest in flexible capacity will avoid costly stock-outs and protect customer relationships. Our report’s supply-risk matrix quantifies lead-time sensitivity and single-source exposure across the product portfolio.
-
Regulatory playbook: 2026 saw approvals for new indications and the first appearance of generics in previously protected categories. Strategic monitoring of regulatory lanes (e.g., approvals, first-generic timing, and label expansions) is essential for commercial forecasting and negotiation strategy.
-
Procurement shifts: With payers and large hospital systems pushing value-based procurement, pricing pressures will emerge in commoditized segments. Conversely, differentiated agents with demonstrable safety or workflow benefits will retain premium positioning if supported by evidence-generation and payer engagement.
Strategic Playbook for 2026 Executives
Leaders should adopt a dual-track strategy: shore up core operational resilience while investing selectively in differentiation. The following high-confidence actions are central to converting market growth into durable advantage.
-
Scenario-based capacity and procurement planning: Use multi-scenario demand curves to size capacity and secure critical supply contracts. Prioritize flexibility — modular fill-and-finish and regional sourcing reduce exposure to localized disruption.
-
Portfolio prioritization and evidence generation: Redirect development spend to agents with the strongest clinical and economic value prop, and accelerate post-market studies that demonstrate outcomes and workflow benefit to justify premium pricing.
-
Commercial segmentation and channel optimization: Differentiate go-to-market approaches by customer type (tertiary hospital vs. outpatient imaging centers) and by product value tier. Align sales incentives and contracting teams to value-based agreements.
-
Partnerships and M&A discipline: Consider bolt-on M&A and strategic manufacturing partnerships to accelerate time-to-market and close capability gaps. Our report includes an M&A screening framework and a prioritized shortlist of targets by strategic fit.
-
Regulatory and P&R (pricing & reimbursement) intelligence: Build a live regulatory tracker and a payer engagement roadmap to anticipate access constraints and optimize launch sequencing across jurisdictions.
-
Risk adjusted commercialization: Deploy risk-sharing and outcome-based contracts selectively for premium agents while defending volume through competitive pricing and supply guarantees for commoditized lines.
What PW Consulting’s Full Report Delivers
This preview intentionally emphasizes strategic direction and omits proprietary segment-level figures intended for subscribers. The full report is structured to be immediately operational and includes:
-
An interactive market model (2020–2032) with scenario toggles and sensitivity analysis that allow teams to stress-test volume, price, and substitution assumptions.
-
A granular supply-chain risk matrix covering raw materials, contract manufacturers, and fill-and-finish capacity by geography.
-
Regulatory timeline and approval risk scoring, mapping recent 2025–2026 developments to forecast windows and launch windows.
-
Company profiles and competitive positioning maps with go-to-market playbooks tailored to incumbents, specialists, and regional manufacturers.
-
M&A and partnership screening — prioritized by strategic rationale, integration risk, and value creation potential.
-
Practical toolkits: negotiation levers for procurement teams, a clinical-evidence roadmap for regulatory and market-access functions, and an implementation checklist for supply-chain resilience.
How to Use This Intelligence in 90, 180, and 360 Days
-
90 days: Establish a cross-functional war room to validate demand scenarios against internal projections, lock critical supply contracts, and prioritize immediate evidence-generation projects for high-value products.
-
180 days: Finalize capacity agreements (or partner arrangements), pilot value-based contracts with selected customers, and initiate targeted clinical or real-world evidence studies to support premium pricing.
-
360 days: Execute selective M&A or licensing deals identified through the report’s screening process, scale successful pilots, and transition to continuous-market intelligence to stay ahead of competitive or regulatory shocks.
Conclusion: The contrast medium market’s growth profile creates substantial opportunity, but capturing value requires rigorous scenario planning, disciplined portfolio management, and proactive supply-chain orchestration. PW Consulting’s full Contrast Medium Market study translates the market’s macro trajectory — from a USD 6.4 billion base in 2025 to an expected near–USD 10.8 billion by 2032 at a 7.9% CAGR — into actionable playbooks. For leaders preparing 2026 budgets, partnership strategies, and M&A pipelines, this is the intelligence that converts projection into executable advantage. Access the complete report to unlock the segment-level models, company scorecards, and implementation tools that underpin our recommendations.
For detailed analysis of this topic, please visit the official page: Contrast Medium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com